Showing posts with label renting. Show all posts

Monday, December 11, 2017

Want to buy your first home, but money is a bit tight? Would having a roommate work for you?


How to Save on a Mortgage Payment Whether Buying or Selling

How to Save on a Mortgage Payment Whether Buying or Selling | MyKCM
In Trulia’s recent report, Rent vs. Buy: Roommate Edition, they examined the impact that renting with a roommate has in determining whether it is more expensive to rent or buy. The study explains:
“Since we started keeping track in 2012, it’s been a better deal to buy than rent in America’s largest housing markets – and for much of that time it hasn’t been close.”
It then goes on to ask the question:
“But does the equation change for renters who share their rent with a roommate?”

The report reveals:

“While the standard rent vs. buy analysis reveals buying is cheaper than renting in all of the nation’s 100 largest metros, this doesn’t hold true for those choosing between renting with a roommate and buying a starter home.”
It seems obvious that sharing the cost of renting your living space by taking in a roommate dramatically decreases your housing expense (which is exactly what the report concluded), but it got us thinking.

What if you purchased a home and took in that same roommate?

The savings you would gain by adding a roommate would also occur if you purchased a home. This presents an opportunity for a list of possible purchasers. Here are two examples:
  1. The first-time buyer: As the report explains, many young adults already live with a roommate. If they purchased a new home, perhaps that roommate (or someone else) would be willing to rent a room in their new house. The rent could help offset the mortgage payment.
  2. The empty-nester seller looking to move: Their home may no longer fit their current lifestyle. They may now be looking for something a little smaller with all the bedrooms on the ground level. These families may be able to open a bedroom to an older family member (parents, aunts & uncles, etc.). This would kill two birds with one stone.
A smaller, move-down home is almost impossible to find in the current housing market. If the seller-turned-buyer takes on a tenant, they could buy a more expensive home knowing that the additional monies needed to pay the mortgage would be offset with the additional monies they receive in rent. Secondly, the older couple (ex. parents) could get a housing option that probably far surpasses anything else available to them in the current market.

Bottom Line

Considering the concept of renting a portion of your house to be able to purchase the perfect home may make sense to many families. You will need to decide if it is right for you.

Thursday, September 28, 2017

Building equity, while owning a home, helps increase your personal wealth...

How Your Home’s Value Grows Your Family’s Wealth

How Your Home’s Value Grows Your Family’s Wealth | MyKCM
Over the next five years, home prices are expected to appreciate 3.64% per year on average and to grow by 18.4% cumulatively, according to Pulsenomics’ most recent Home Price Expectation Survey.

So, what does this mean for homeowners and their equity position?

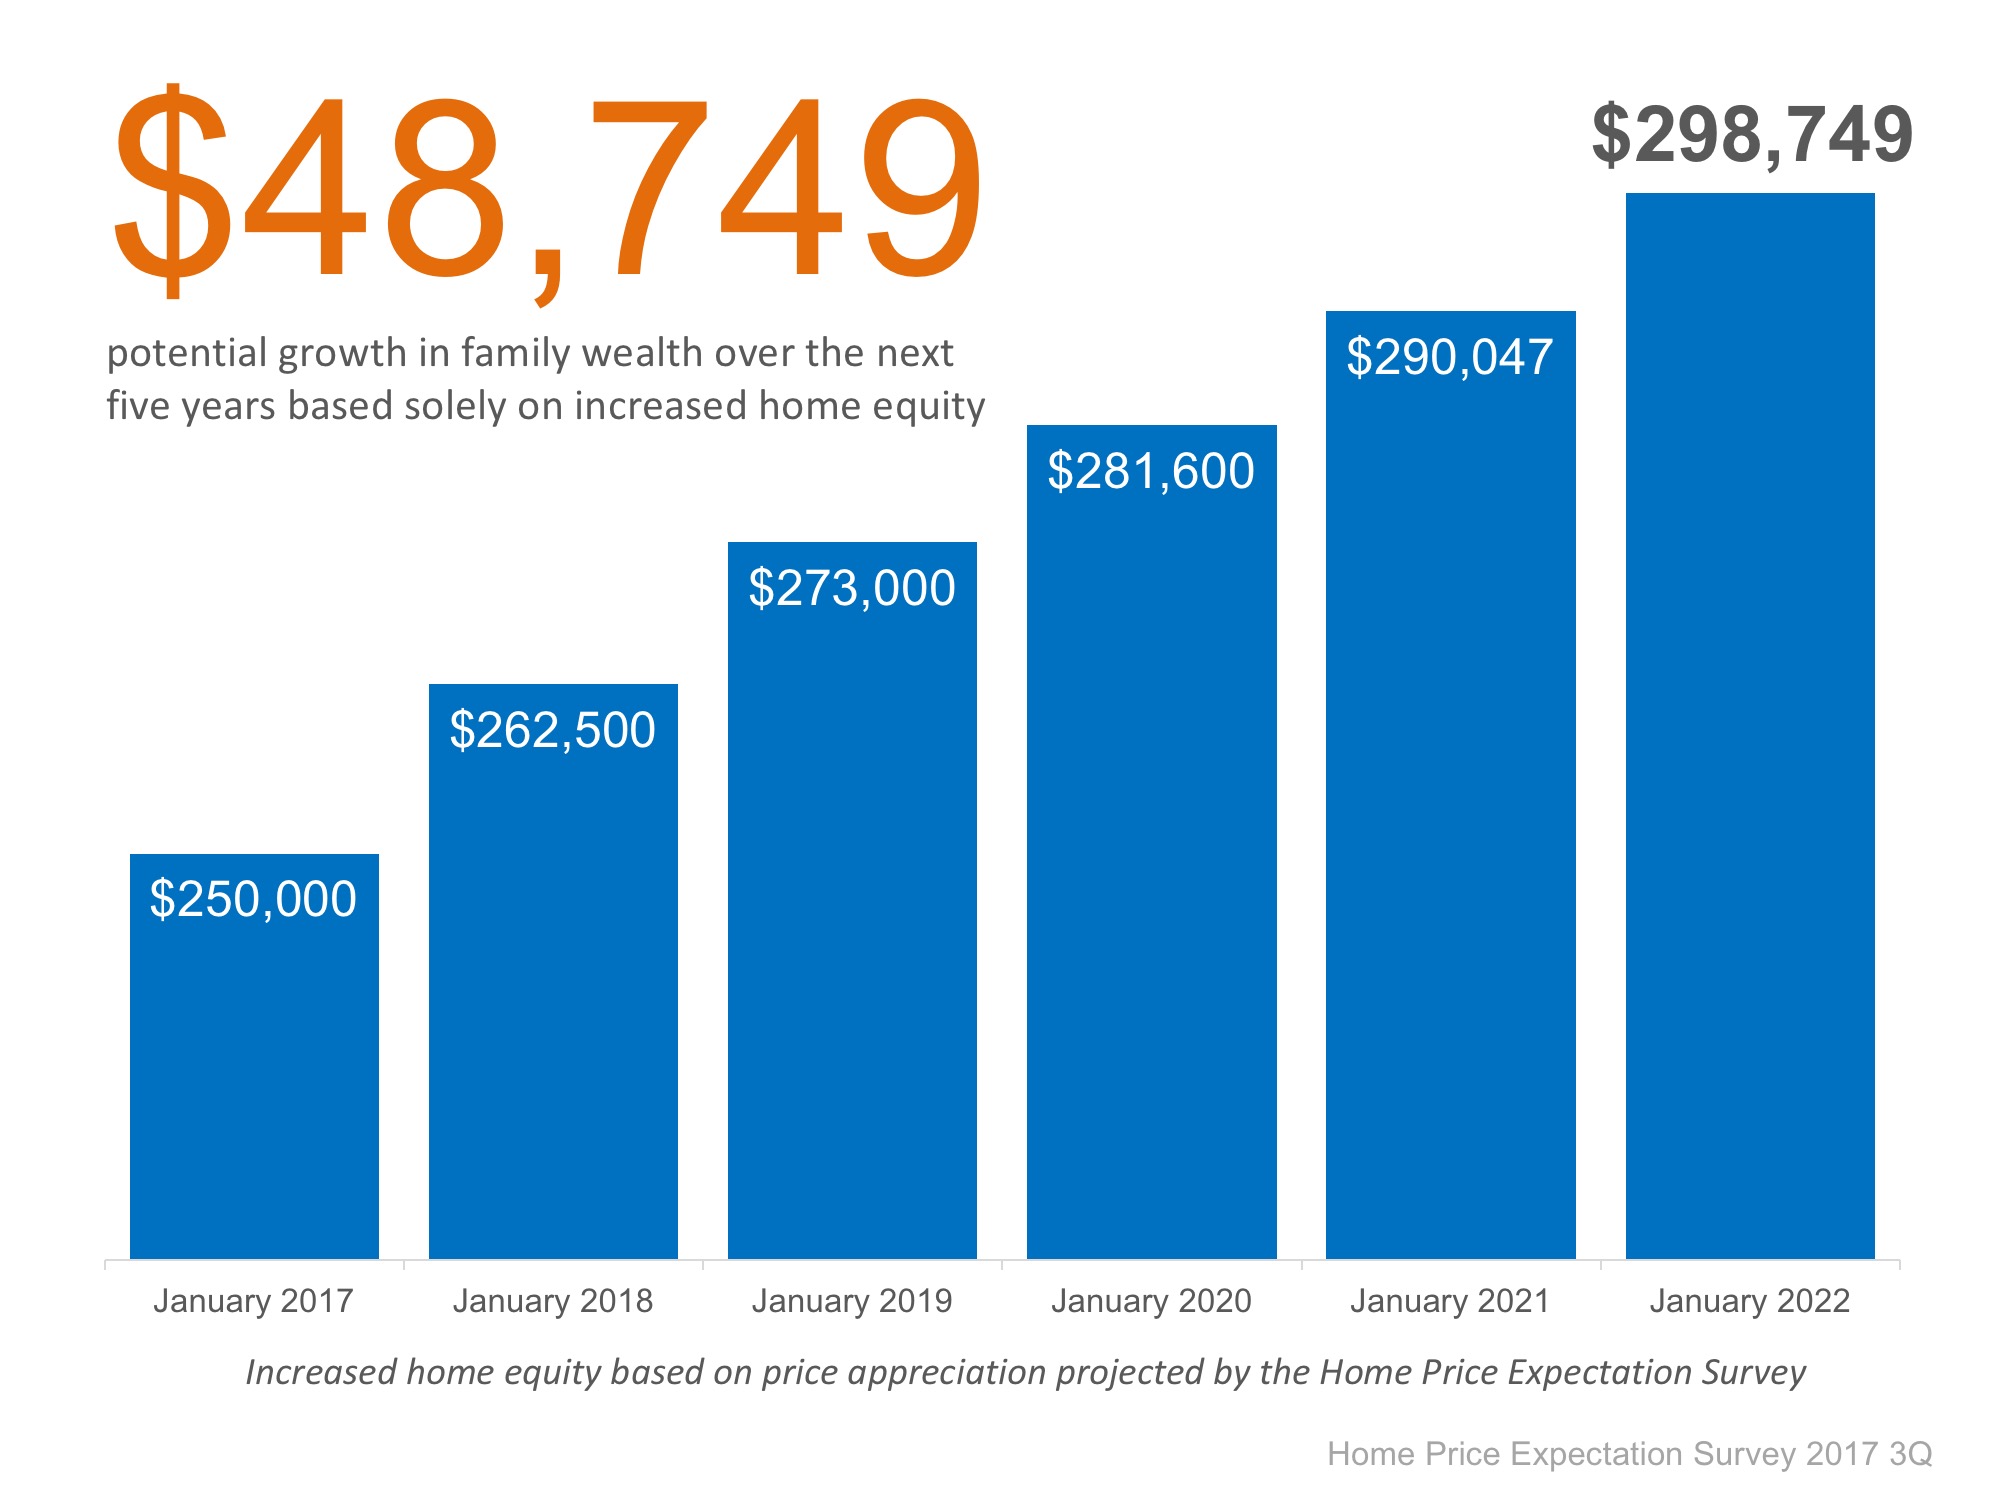
As an example, let’s assume a young couple purchased and closed on a $250,000 home in January. If we look at only the projected increase in the price of that home, how much equity will they earn over the next 5 years?
How Your Home’s Value Grows Your Family’s Wealth | MyKCM
Since the experts predict that home prices will increase by 5.0% this year alone, the young homeowners will have gained $12,500 in equity in just one year.
Over a five-year period, their equity will increase by nearly $49,000! This figure does not even take into account their monthly principal mortgage payments. In many cases, home equity is one of the largest portions of a family’s overall net worth.

Bottom Line

Not only is homeownership something to be proud of, but it also offers you and your family the ability to build equity you can borrow against in the future. If you are ready and willing to buy, find out if you are able to today!

Tuesday, September 12, 2017

Buy a home and start building your net worth.

Homeowner’s Net Worth Is Still Greater Than a Renter’s

Homeowner’s Net Worth Is Still Greater Than a Renter’s | MyKCM
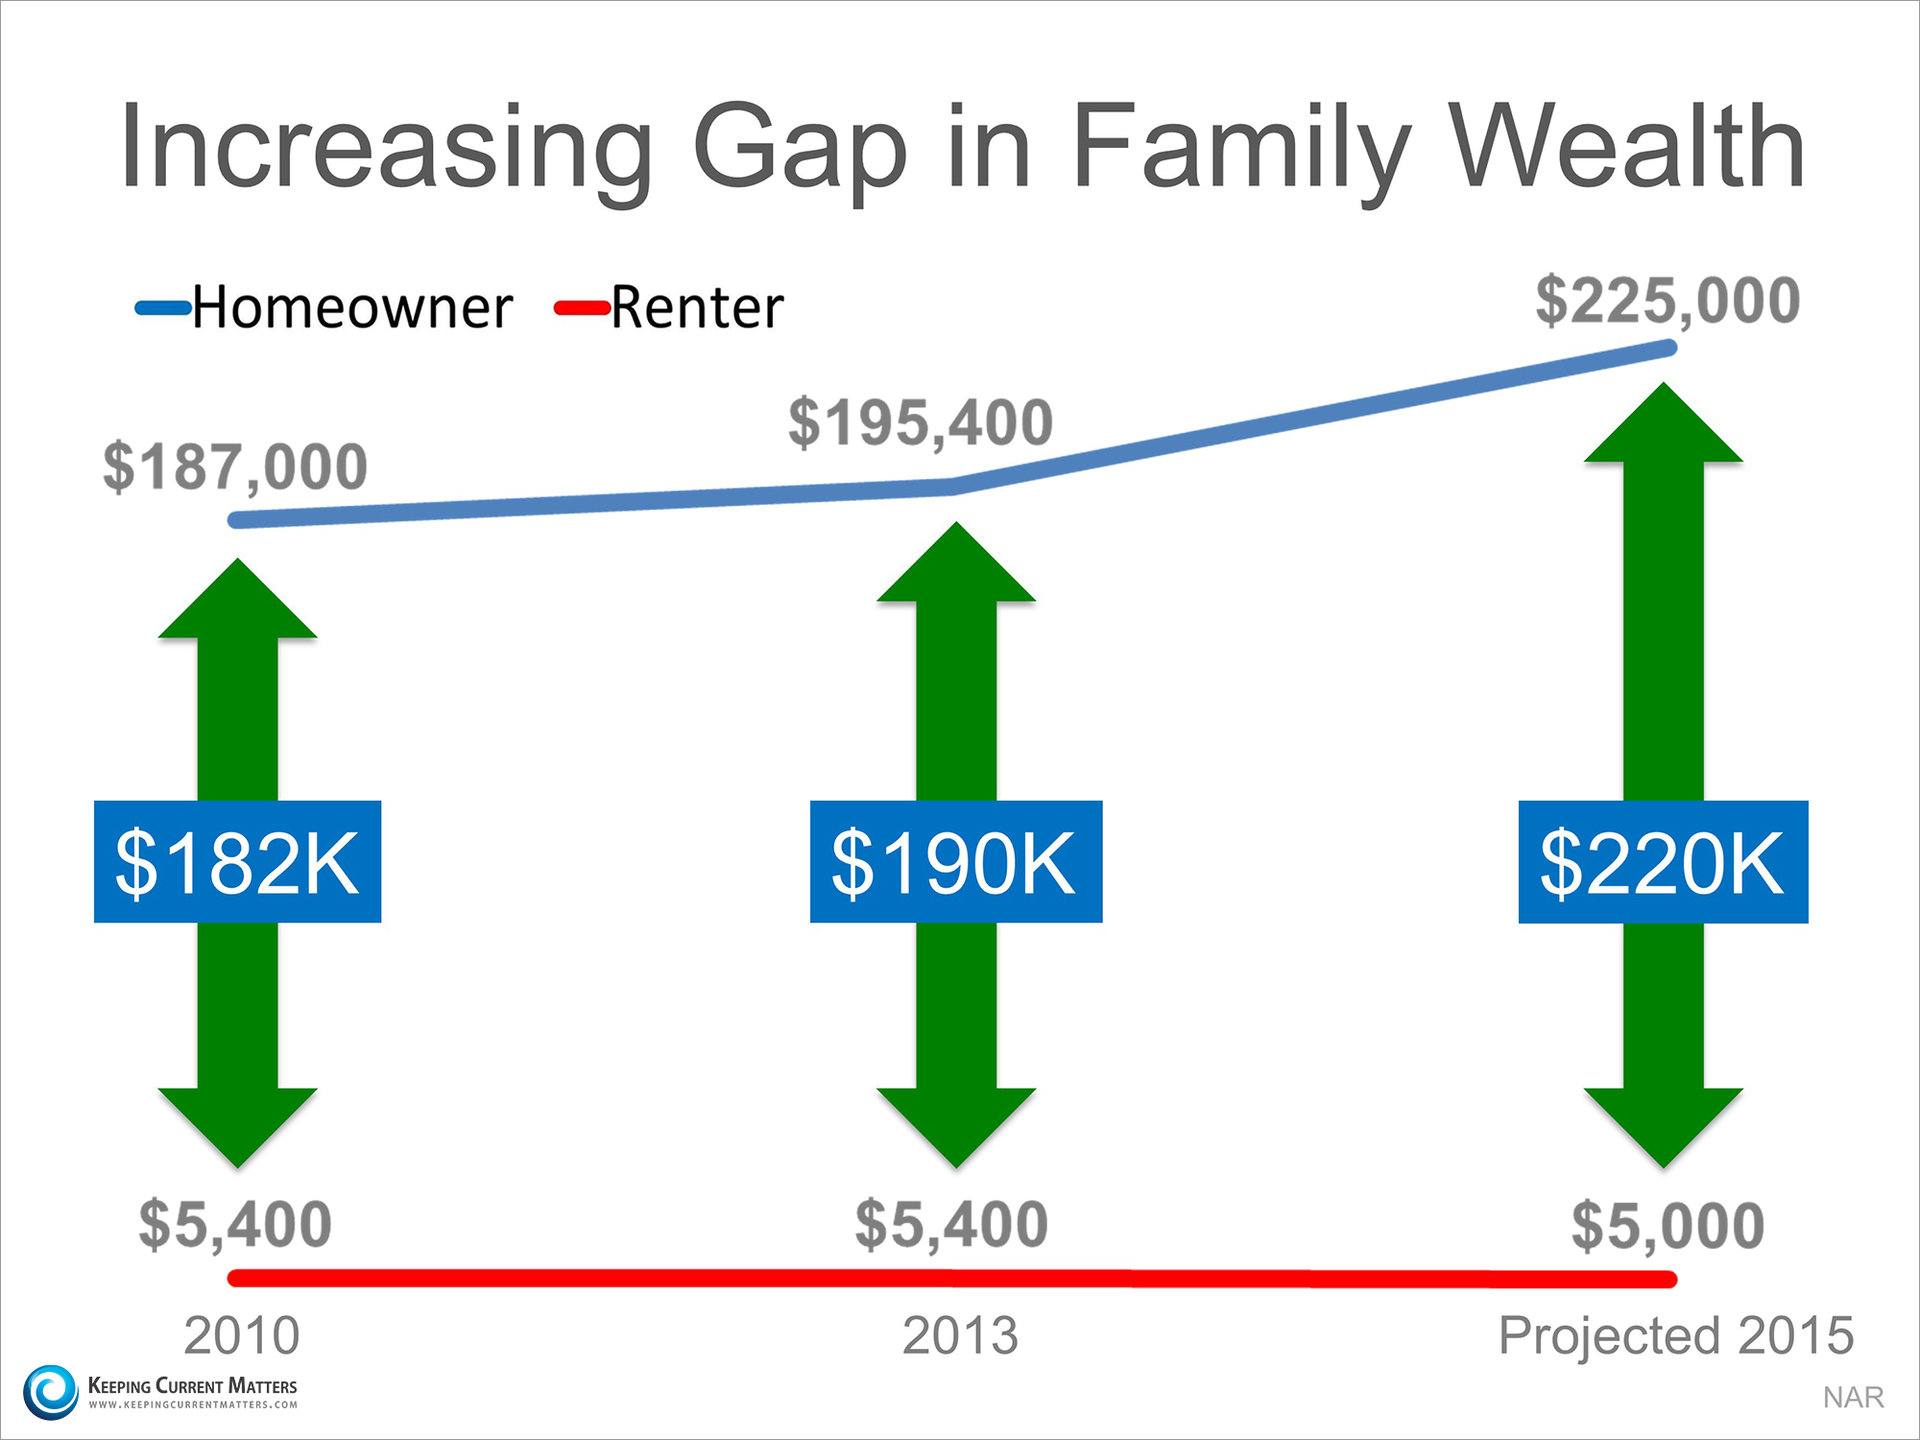
Every three years, the Federal Reserve conducts their Survey of Consumer Finances in which they collect data across all economic and social groups. The latest survey, which includes data from 2010-2013, reports that a homeowner’s net worth is 36 times greater than that of a renter ($194,500 vs. $5,400). 
The latest survey data, covering 2014-2016 will be released later this year. In the meantime, Lawrence Yun, the National Association of Realtors’ Chief Economist estimates that the gap has widened even further, to 45 times greater ($225,000 vs. $5,000)! 

Put Your Housing Cost to Work for You

As we’ve said before, simply put, homeownership is a form of ‘forced savings.’ Every time you pay your mortgage, you are contributing to your net worth. Every time you pay your rent, you are contributing to your landlord’s net worth.
The latest National Housing Pulse Survey from NAR reveals that 84% of consumers believe that purchasing a home is a good financial decision. William E. Brown comments:
“Despite the growing concern over affordable housing, this survey makes it clear that a strong majority still believe in homeownership and aspire to own a home of their own. Building equity, wanting a stable and safe environment, and having the freedom to choose their neighborhood remain the top reasons to own a home.” 

Bottom Line

If you are interested in finding out if you could put your housing cost to work for you by purchasing a home, let’s get together and evaluate your ability to buy today!

Tuesday, June 27, 2017

We hear this time and time again, homeowners tend to have a higher personal wealth than renters...

Homeownership Is a Good Financial Investment!

Homeownership Is a Good Financial Investment! | MyKCM
According to a recent report by Trulia, “buying is cheaper than renting in 100 of the largest metro areas by an average of 33.1%.” The report may have some people thinking about buying a home instead of signing another lease extension, but does that make sense from a financial perspective?
Ralph McLaughlin, Trulia’s Chief Economist explains:
“Owning a home is one of the most common ways households build long-term wealth, as it acts like a forced savings account. Instead of paying your landlord, you can pay yourself in the long run through paying down a mortgage on a house.”
The article listed five reasons why owning a home makes financial sense:
  1. Mortgage payments can be fixed while rents go up.
  2. Equity in your home can be a financial resource later.
  3. You can build wealth without paying capital gains.
  4. A mortgage can act as a forced savings account.
  5. Overall, homeowners can enjoy greater wealth growth than renters.

Bottom Line

Before you sign another lease, let’s get together and discuss all your options.

Monday, June 26, 2017

Should you buy or rent? That all depends...

The TRUTH Behind the RENT vs. BUY Debate

The TRUTH Behind the RENT vs. BUY Debate | MyKCM
In a blog post published last Friday, CNBC’s Diana Olnick reported on the latest results of the FAU Buy vs. Rent Index. The index examines the entire US housing market and then isolates 23 major markets for comparison. The researchers at FAU use a “‘horse race’ comparison between an individual that is buying a home and an individual that rents a similar-quality home and reinvests all monies otherwise invested in homeownership.”
Having read both the index and the blog post, we would like to clear up any confusion that may exist. There are three major points that we would like to counter:

1. The Title

The CNBC blog post was titled, “Don’t put your money in a house, says a new report.” The title of the press release about the report on FAU’s website was “FAU Buy vs. Rent Index Shows Rising Prices and Mortgage Rates Moving Housing Markets in the Direction of Renting.”
Now, we all know headlines can attract readers and the stronger the headline the more readership you can attract, but after dissecting the report, this headline may have gone too far. The FAU report notes that rising home prices and the threat of increasing mortgage rates could make the decision of whether to rent or to buy a harder one in three metros, but does not say not to buy a home.

2. Mortgage Interest Rates are Rising

According to Freddie Mac, mortgage interest rates reached their lowest mark of 2017 last week at 3.89%. Interest rates have hovered around 4% for the majority of 2017, giving many buyers relief from rising home prices and helping with affordability.
While experts predict that rates will increase by the end of 2017, the latest projections have softened, with Freddie Mac predicting that rates will rise to 4.3% in Q4.

3. “Renting may be a better option than buying, according to the report.”

Of the 23 metros that the study reports on, 11 of them are firmly in buy territory, including New York, Boston, Chicago, Cleveland, and more. This means that in nearly half of all the major cities in the US, it makes more financial sense to buy a home than to continue renting one.
In 9 of the remaining metros, the decision as to whether to rent or buy is closer to a toss-up right now. This means that all things being equal, the cost to rent or buy is nearly the same. That leaves the decision up to the individual or family as to whether they want to renew their lease or buy a home of their own.
The 3 remaining metros Dallas, Denver and Houston, have experienced high levels of price appreciation and have been reported to be in rent territory for well over a year now, so that’s not news…

Beer & Cookies

One of the three authors of the study, Dr. Ken Johnson has long reported on homeownership and the decision between renting and buying a home. The methodology behind the report goes on to explain that even in a market where a renter would be able to spend less on housing, they would have to be disciplined enough to reinvest their remaining income in stocks/bonds/other investments for renting a home to be a more attractive alternative to buying.
Johnson himself has said:
“However, in perhaps a more realistic setting where renters can spend on consumption (beer, cookies, education, healthcare, etc.), ownership is the clear winner in wealth accumulation. Said another way, homeownership is a self-imposed savings plan on the part of those that choose to own.” 

Bottom Line

In the end, you and your family are the only ones who can decide if homeownership is the right path to go down. Real estate is local and every market is different. Let’s get together to discuss what’s really going on in your area and how we can help you make the best, most informed decision for you and your family.

Monday, June 19, 2017

Renting? Did you know the median monthly rent has consistently increased since 1988?

Is Now a Good Time to Rent?

Is Now a Good Time to Rent? | MyKCM
People often ask if now is a good time to buy a home, but nobody ever asks when a good time to rent is. Regardless, we want to make certain that everyone understands that today is NOT a good time to rent.
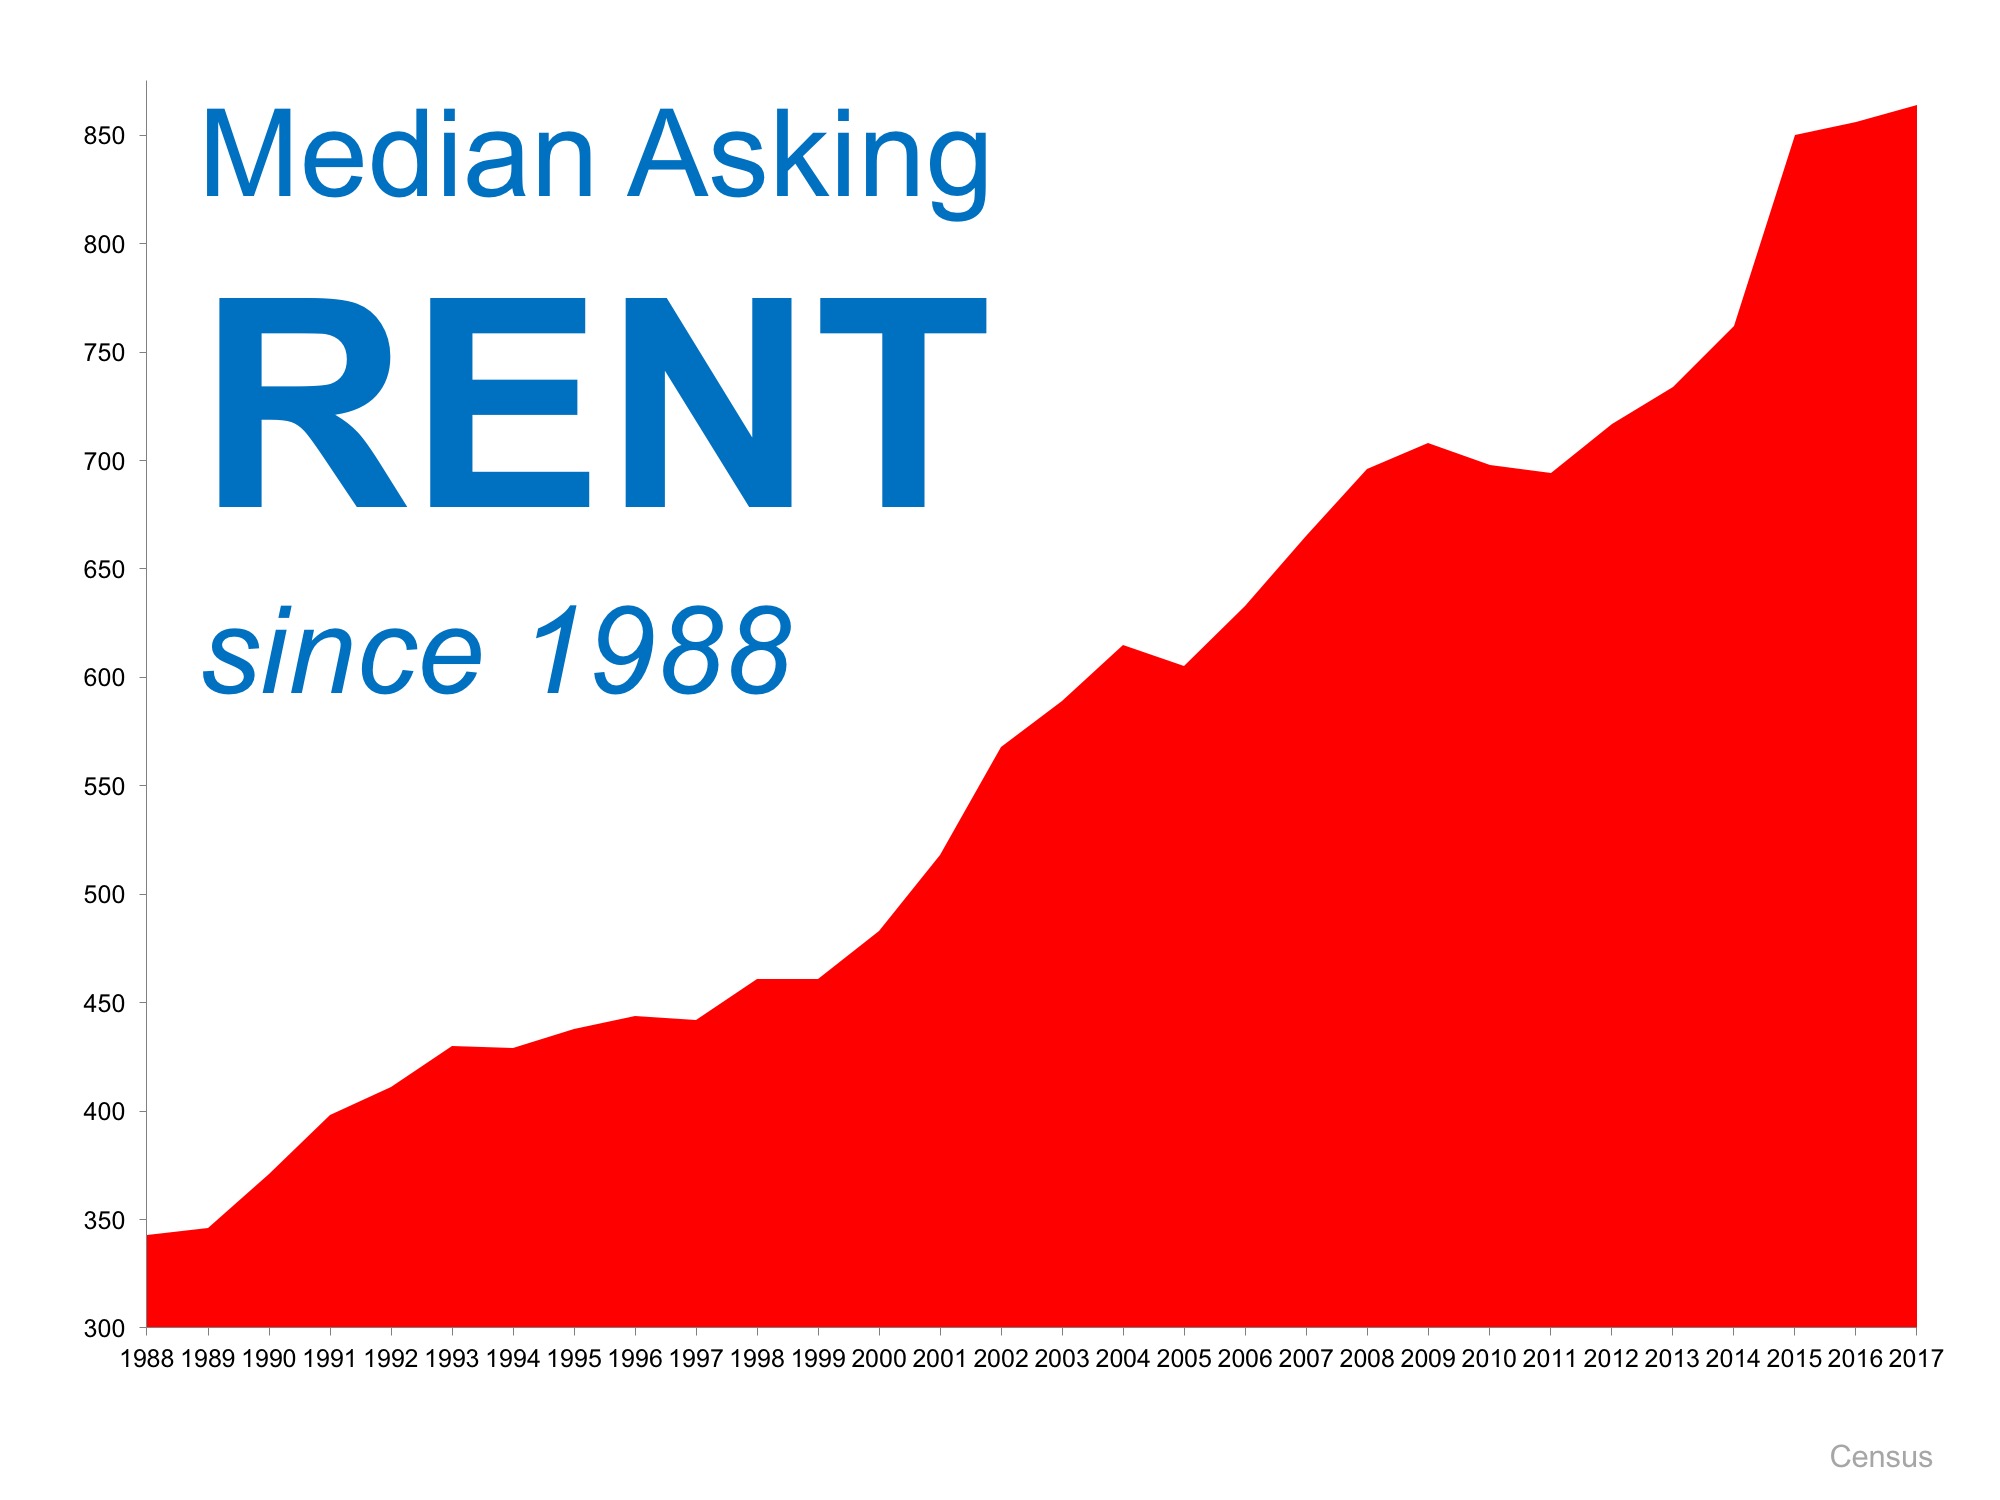
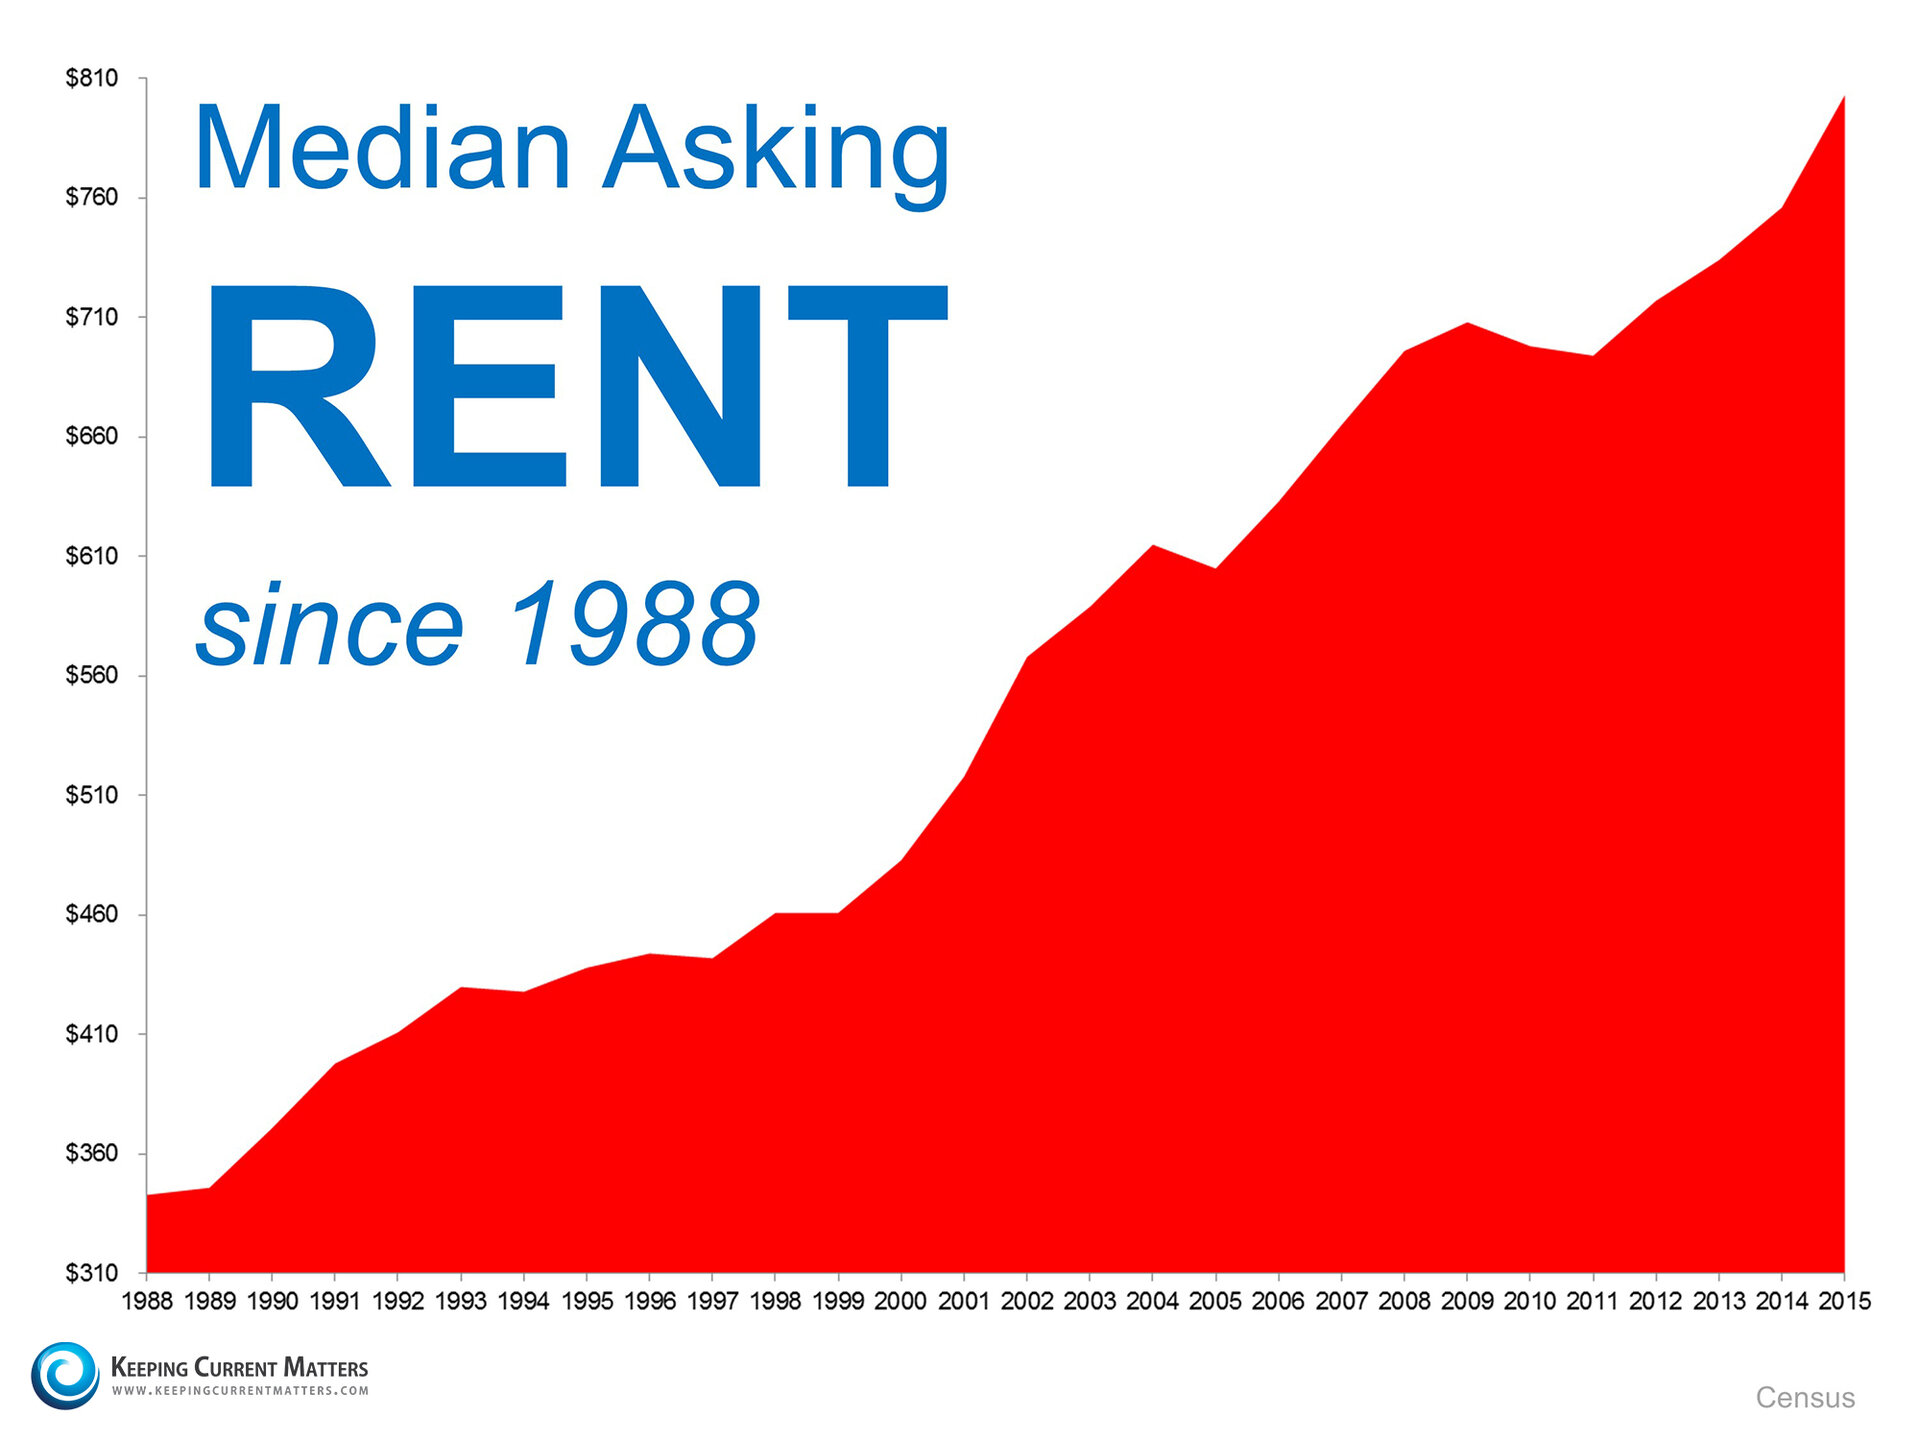
The Census Bureau recently released their 2017 first quarter median rent numbers. Here is a graph showing rent increases from 1988 until today:
Is Now a Good Time to Rent? | MyKCM
As you can see, rents have steadily increased and are showing no signs of slowing down. If you are faced with making the decision of whether or not you should renew your lease, you might be pleasantly surprised at your ability to buy a home of your own instead.

Bottom Line

One way to protect yourself from rising rents is to lock in your housing expense by buying a home. If you are ready and willing to buy, let’s meet to determine if you are able to today!

Friday, April 7, 2017

If you are going to be paying for housing, make sure it benefits you financially.

Renting or Buying… Either Way You’re Paying a Mortgage

Renting or Buying… Either Way You’re Paying a Mortgage | MyKCM
There are some people who have not purchased homes because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that, unless you are living with your parents rent-free, you are paying a mortgage - either yours or your landlord’s.
As Entrepreneur Magazine, a premier source for small business, explained this month in their article, “12 Practical Steps to Getting Rich”:
“While renting on a temporary basis isn't terrible, you should most certainly own the roof over your head if you're serious about your finances. It won't make you rich overnight, but by renting, you're paying someone else's mortgage. In effect, you're making someone else rich.”
Christina Boyle, Senior Vice President and head of the Single-Family Sales & Relationship Management organization at Freddie Mac, explains another benefit of securing a mortgage vs. paying rent:
“With a 30-year fixed rate mortgage, you’ll have the certainty & stability of knowing what your mortgage payment will be for the next 30 years – unlike rents which will continue to rise over the next three decades.”
As an owner, your mortgage payment is a form of ‘forced savings’ which allows you to build equity in your home that you can tap into later in life. As a renter, you guarantee the landlord is the person with that equity.
Interest rates are still at historic lows, making it one of the best times to secure a mortgage and make a move into your dream home. Freddie Mac’s latest report shows that rates across the country were at 4.23% last week.

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, now may be the time to buy.

Thursday, February 23, 2017

The real cost of renting is not just what you pay for rent...

Do You Know the Real Cost of Renting vs. Buying?

Do You Know the Real Cost of Renting vs. Buying? [INFOGRAPHIC] | MyKCM

Some Highlights:

  • Historically, the choice between renting or buying a home has been a close decision.
  • Looking at the percentage of income needed to rent a median-priced home today (30%), vs. the percentage needed to buy a median-priced home (15%), the choice becomes obvious.
  • Every market is different. Before you renew your lease again, find out if you could use your housing costs to own a home of your own!

Friday, February 3, 2017

Add throwing great Superbowl parties to your list of pros for owning a home versus renting...

5 Reasons Homeowners Throw Better Super Bowl Parties!

5 Reasons Homeowners Throw Better Super Bowl Parties! [INFOGRAPHIC] | MyKCM

Highlights:

  • Watching the Big Game at home with your friends & family offers many advantages.
  • There’s more room to entertain a large crowd, and you don’t have to worry about complaints to your landlord if you cheer too loudly!
  • The kitchen is big enough to make as many appetizers as you want, and if some of your guests are only there to watch the commercials, they can do so on a different TV in another room!

Tuesday, December 13, 2016

Analysts project significant appreciation in the housing market, over the next 5 years...

Home Prices: Where Will They Be in 5 Years?

Home Prices: Where Will They Be in 5 Years? | MyKCM
Today, many real estate conversations center on housing prices and where they may be headed. That is why we like the Home Price Expectation Survey.
Every quarter, Pulsenomics surveys a nationwide panel of over one hundred economists, real estate experts, and investment & market strategists about where they believe prices are headed over the next five years. They then average the projections of all 100+ experts into a single number.

The results of their latest survey:

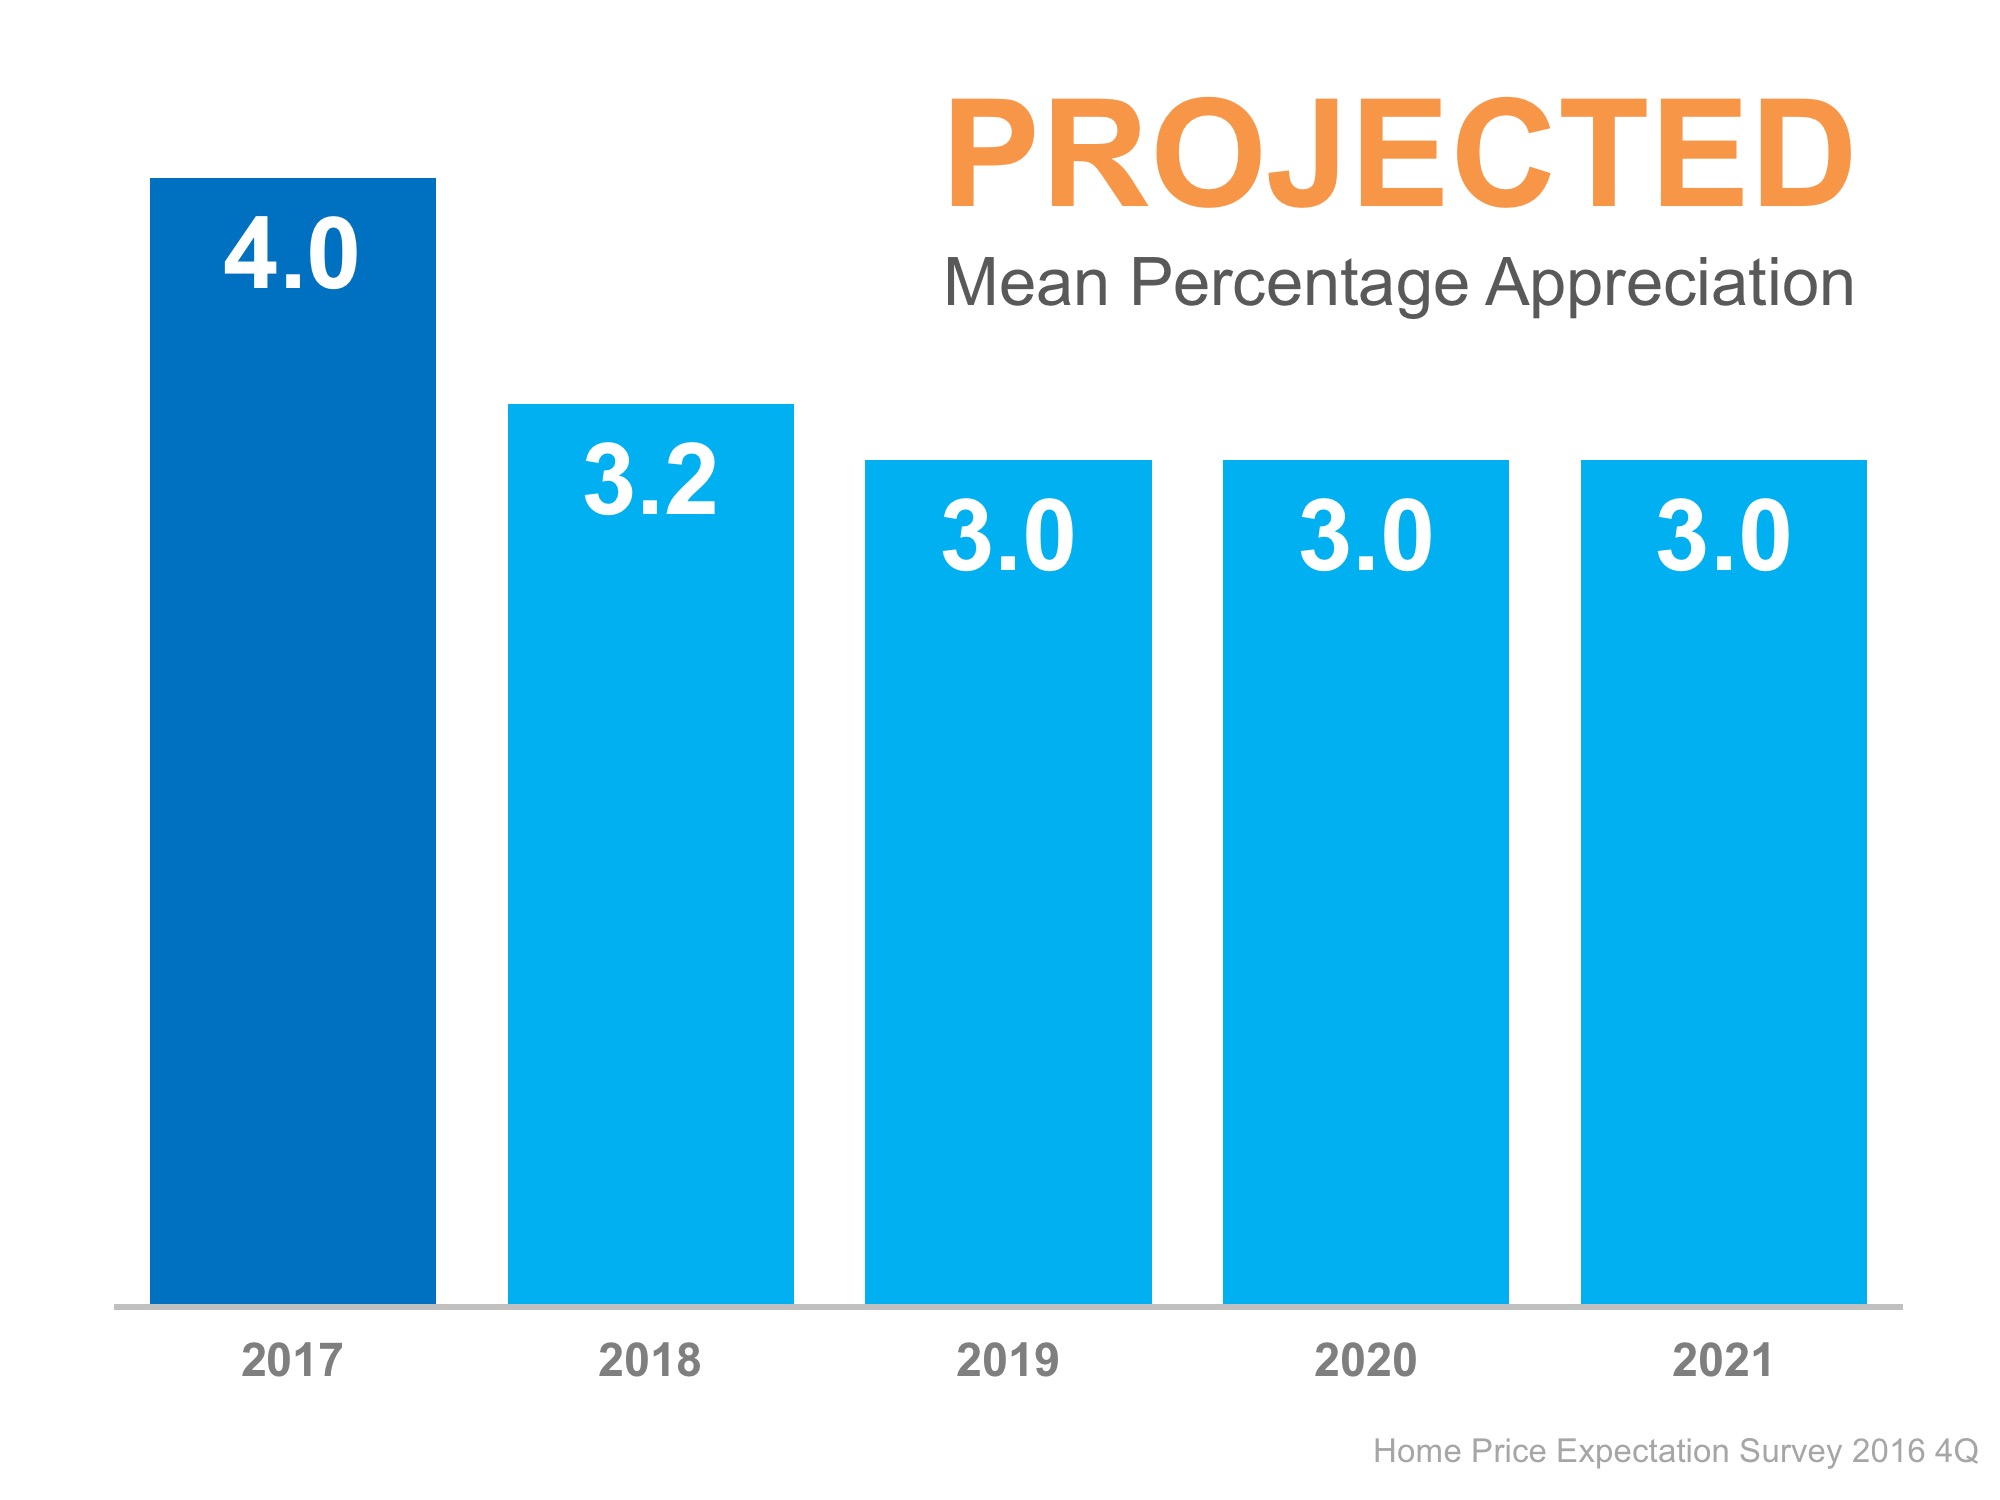
Home values will appreciate by 4.0% over the course of 2017, 3.2% in 2018 and 3.0% the next three years (as shown below). That means the average annual appreciation will be 3.24% over the next 5 years.
Home Prices: Where Will They Be in 5 Years? | MyKCM
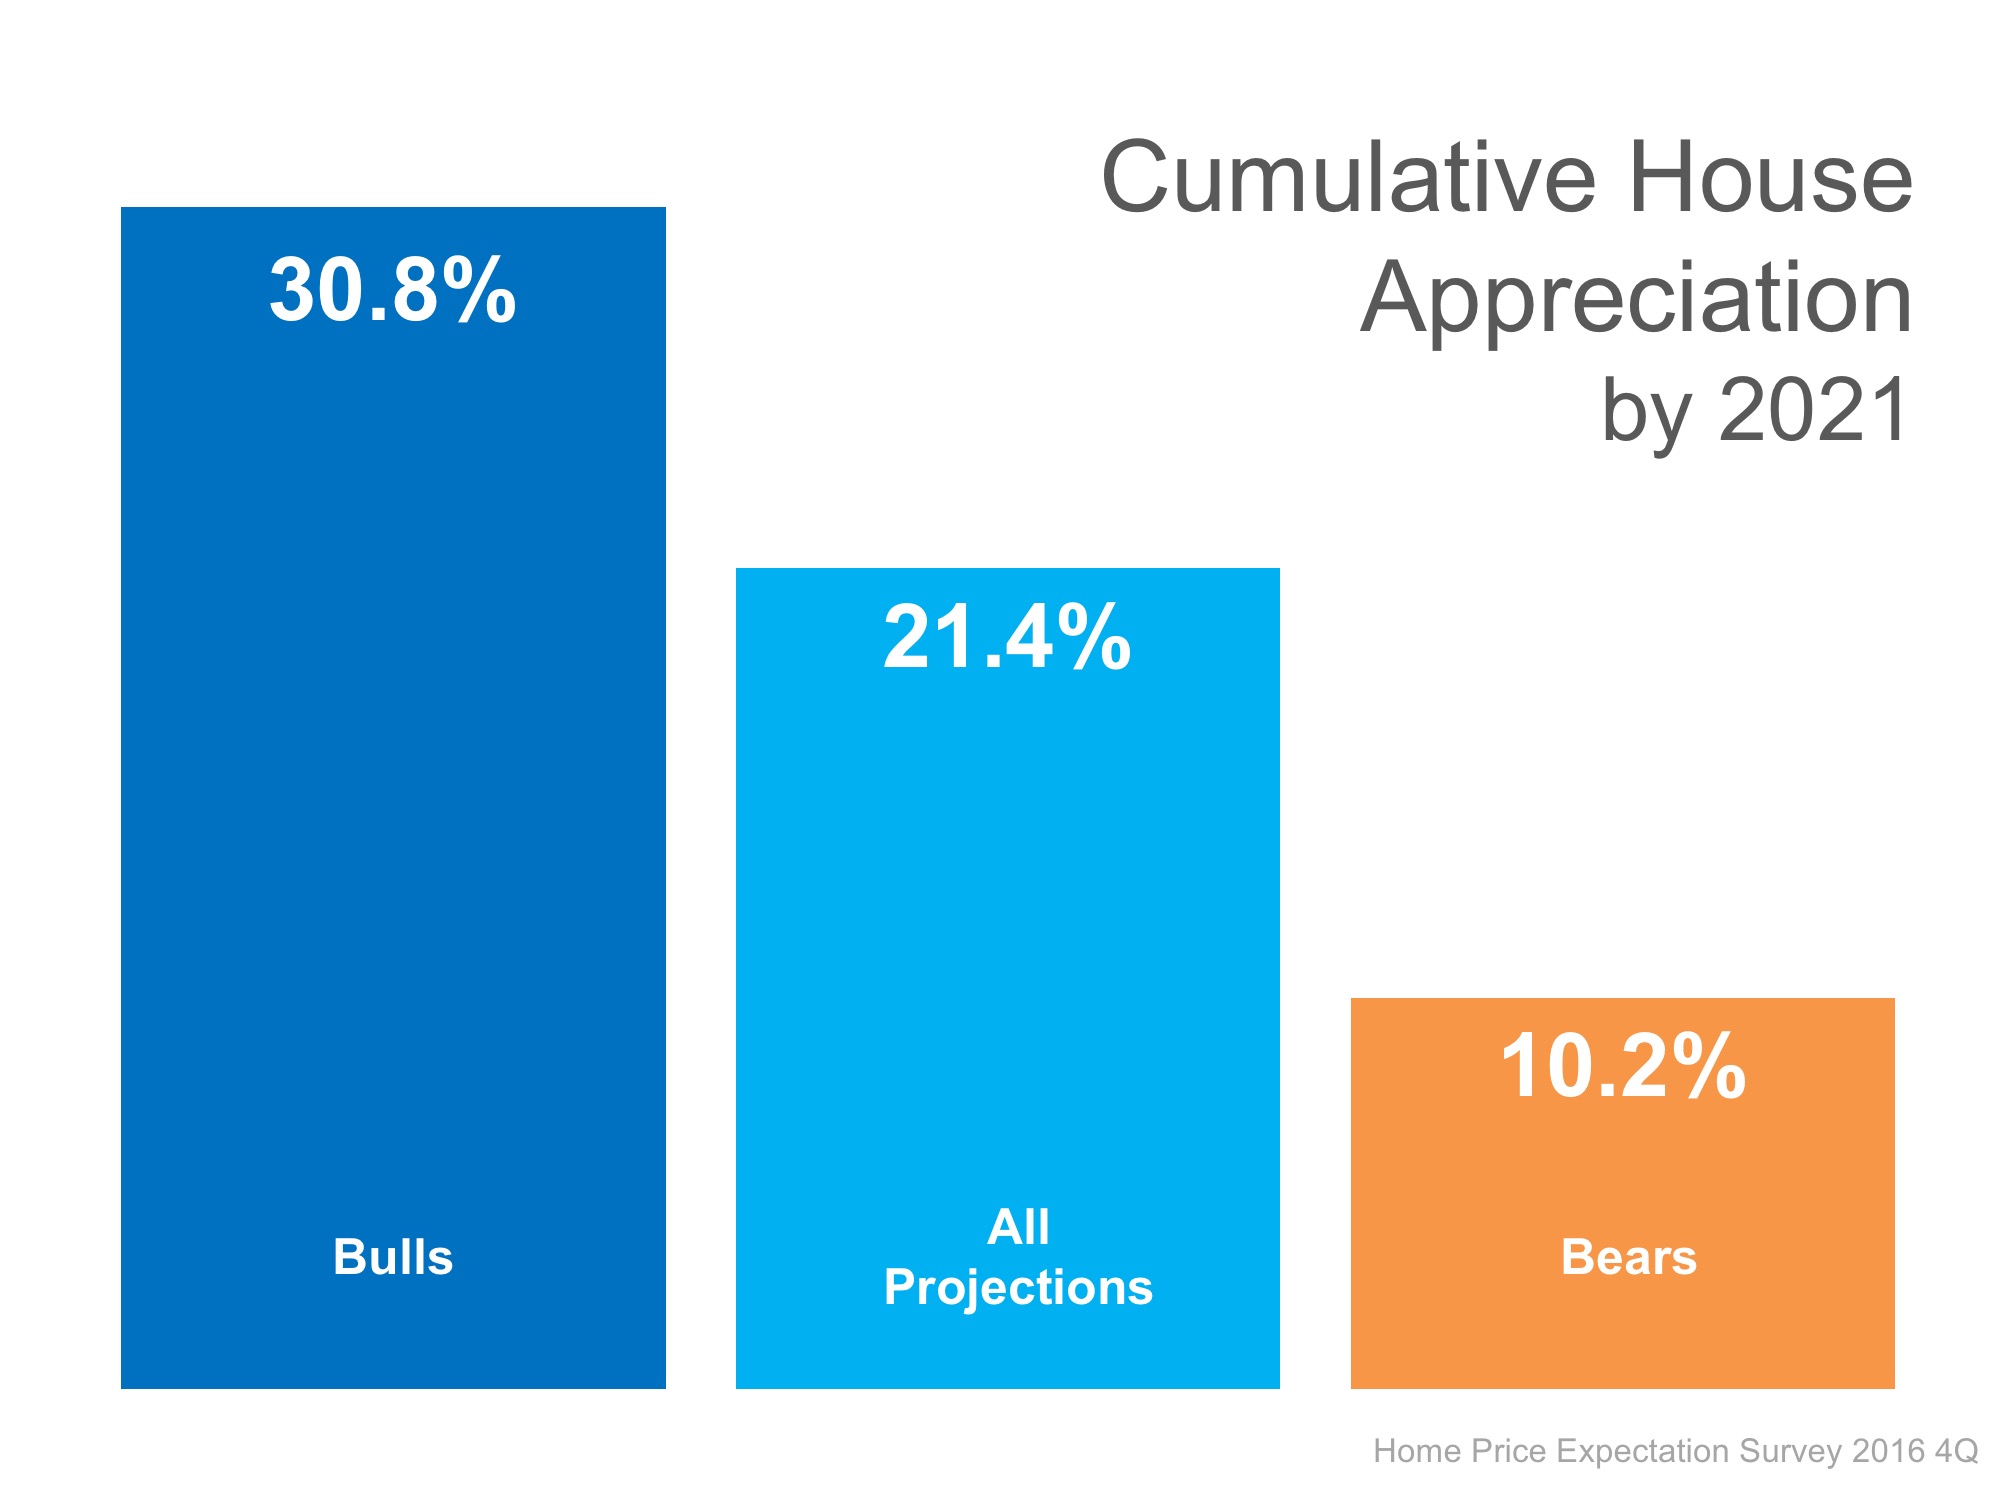
The prediction for cumulative appreciation ticked up from 18.7% to 21.4% by 2021. The experts making up the most bearish quartile of the survey are projecting a cumulative appreciation of 10.2%.
Home Prices: Where Will They Be in 5 Years? | MyKCM

Bottom Line

Individual opinions make headlines. We believe this survey is a fairer depiction of future values.

Tuesday, October 25, 2016

Mortgage interest rates remain low, while rents continue to rise...


Buying is Now 37.7% Cheaper Than Renting in the US


Buying is Now 37.7% Cheaper Than Renting in the US | MyKCM
The results of the latest Rent vs. Buy Report from Trulia show that homeownership remains cheaper than renting with a traditional 30-year fixed rate mortgage in the 100 largest metro areas in the United States.
The updated numbers actually show that the range is an average of 17.4% less expensive in Honolulu (HI), all the way up to 53.2% less expensive in Miami & West Palm Beach (FL), and 37.7% nationwide!

Other interesting findings in the report include:

  • Interest rates have remained low, and even though home prices have appreciated around the country, they haven’t greatly outpaced rental appreciation.
  • Home prices would have to appreciate by a range of over 23% in Honolulu (HI), up to over 45% in Ventura County (CA), to reach the tipping point of renting being less expensive than buying.
  • Nationally, rates would have to reach 9.1%, a 145% increase over today’s average of 3.7%, for renting to be cheaper than buying. Rates haven’t been that high since January of 1995, according to Freddie Mac.

Bottom Line

Buying a home makes sense socially and financially. If you are one of the many renters out there who would like to evaluate your ability to buy this year, let’s get together to help you find your dream home.

Tuesday, September 27, 2016

Unless you are in Dallas, Denver or Houston...the housing market is leaning favorably to buying a home over renting...


US Housing Market Moving Further into ‘Buy Territory’


US Housing Market Moving Further into ‘Buy Territory’ | MyKCM
According to the latest Beracha, Hardin & Johnson Buy vs. Rent (BH&J) Index, the U.S. housing market has continued to move deeper into buy territory, supporting the belief that housing markets across the country remain a sound investment.
The BH&J Index is a quarterly report that attempts to answer the question:

In today’s housing market, is it better to rent or buy a home?

The index examines the entire US housing market and then isolates 23 major cities for comparison. The researchers “measure the relationship between purchasing property and building wealth through a buildup in equity versus renting a comparable property and investing in a portfolio of stocks and bonds.” 
Ken Johnson, Ph.D., Real Estate Economist & Professor at Florida Atlantic University, and one of the index’s authors explains that:
“Housing prices, in general, continue to slow and when considered in light of the recent trends in the Buy vs. Rent Index signal that ownership remains an excellent investment for the majority of Americans.”
While 15 of the 23 metropolitan markets examined moved further into buy territory since last quarter, Dallas, Denver, and Houston are three of the major cities that are currently deep into rent territory. In these three markets, it is estimated that renting will top homeownership 7 out of 10 times.
Eli Beracha, Ph.D., Assistant Professor in the T&S Hollo School of Real Estate at FIU, believes that, in these three markets, the “strong odds in favor of renting to create more wealth should begin to have an impact on the demand for home ownership and from that, impact property prices in these areas.”
Simply put, home prices in these areas will begin to return to more normal levels once residents realize that renting may be a better choice, therefore bringing home affordability back as well.

Bottom Line

The majority of the country is strongly in buy territory. Buying a home makes sense socially and financially. Rents are predicted to increase substantially in the next year. Protect yourself from rising rents by locking in your housing cost with a mortgage payment now.
To Find Out More About the Study: The BH&J Index and other FAU real estate activities are sponsored by Investments Limited of Boca Raton. The BH&J Index is published quarterly and is available online at http://business.fau.edu/buyvsrent.

Monday, May 23, 2016

Rent vs Buy...do you know the true cost?

Rent-vs.-Buy-STMhttp://goo.gl/wgulrQ

Some Highlights:

  • The percentage of income needed to afford a median priced home is almost half the percentage of income needed to afford median rent.
  • Buying costs are significantly less than renting costs.
  • The percentage of income needed to afford a median priced home is less than the historic norm.

Tuesday, January 12, 2016

Thinking about signing a lease? You may want to think again...

The median asking rent is at its' highest point since 1988. 
 When Is It A Good Time To Rent? NOT Now! | Keeping Current Matters People often ask whether or not now is a good time to buy a home. No one ever asks when a good time to rent is. However, we want to make certain that everyone understands that today is NOT a good time to rent.
The Census Bureau recently released their third quarter median rent numbers. Here is a graph showing rent increases from 1988 until today:
Median Asking Rents | Keeping Current Matters
A recent Wall Street Journal article reports that rents rose “faster last year than at any time since 2007, a boon for landlords but one that has stoked concerns about housing affordability for renters.”
 The article also cited results from a recent Reis Inc report which revealed that average effective rents rose 4.6% in 2015, the biggest gain since before the recession. Over the past 15 years, rents have risen at a rate of 2.7% annually.

Where are rents headed?

Jonathan Smoke, Chief Economist at realtor.com recently warned that:
“Low rental vacancies and a lack of new rental construction are pushing up rents, and we expect that they’ll outpace home price appreciation in the year ahead.” 

Bottom Line

According to the WSJ article:
“In general, the higher rents go, the more difficult it will be for young people to save for down payments, making them likely to rent even longer.”
One way to protect yourself from rising rents is to lock in your housing expense by buying a home. If you are ready and willing to buy, meet with a local real estate professional who can help determine if you are able to today!

Tuesday, December 29, 2015

Rents are expected to rise in 2016.

Now may be the time for you to buy!


Don't Let Rising Rents Trap You! | Keeping Current Matters

There are many benefits to homeownership. One of the top ones is being able to protect yourself from rising rents and lock in your housing cost for the life of your mortgage.

Don’t Become Trapped

Jonathan Smoke, Chief Economist at realtor.com recently reported on what he calls a “Rental Affordability Crisis”. He warns that,
“Low rental vacancies and a lack of new rental construction are pushing up rents, and we expect that they’ll outpace home price appreciation in the year ahead.”
The Joint Center for Housing Studies at Harvard University recently released their 2015 Report on Rental Housing, in which they reported that 49% of rental households are cost-burdened, meaning they spend more than 30% of their income on housing. These households struggle to save for a rainy day and pay other bills, such as food and healthcare.

It’s Cheaper to Buy Than Rent

In Smoke’s article, he went on to say,
“Housing is central to the health and well-being of our country and our local communities. In addition, this (rental affordability) crisis threatens the future value of owned housing, as the burdensome level of rents will trap more aspiring owners into a vicious financial cycle in which they cannot save and build a solid credit record to eventually buy a home.”
 “While more than 85% of markets have burdensome rents today, it’s perplexing that in more than 75% of the counties across the country, it is actually cheaper to buy than rent a home. So why aren’t those unhappy renters choosing to buy?”

Know Your Options

Perhaps, you have already saved enough to buy your first home. HousingWire reported that analysts at Nomura believe:
“It’s not that Millennials and other potential homebuyers aren’t qualified in terms of their credit scores or in how much they have saved for their down payment.
It’s that they think they’re not qualified or they think that they don’t have a big enough down payment.” (emphasis added)
Many first-time homebuyers who believe that they need a large down payment may be holding themselves back from their dream home. As we reported last week, in many areas of the country, a first-time home buyer can save for a 3% down payment in less than two years. You may have already saved enough!

Bottom Line

Don’t get caught in the trap so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Have a professional help you determine if you are eligible to get a mortgage.

Thursday, December 10, 2015

Renting? As you head into 2016, you may want to reconsider...


The Residential Rental Market Heading into 2016 | Keeping Current Matters
Below are quotes from experts as well as industry reports & articles that cover the residential rental market in the U.S.

The experts…

Zillow Chief Economist Svenja Gudell:

"Make no mistake: Despite this recent slowdown in rental appreciation, the rental affordability crisis we've been enduring for the past few years shows no signs of easing, especially as income growth remains weak. It will take a lot more supply, and a lot more renters-turned-homeowners, to fully reverse this.”

Lawrence Yun, Chief Economist of the National Association of Realtors

“Rents and home prices are expected to exceed income growth into next year because of the insufficient creation of new home construction and the detrimental impact its inadequacy continues to have on housing costs in several markets.”

David Brickman, Executive Vice President of Freddie Mac Multifamily

"We know rents are rising faster than incomes, and now we have data to show that many renters don't have enough to pay all their debts each month, which is forcing them to make tradeoffs, such as cutting spending on other items.”

The reports and articles…

Zillow's 2016 Housing Market Predictions

“Rising rents won't let up in 2016, and will continue to set new records. The next year will bring the least affordable median rents ever.”

2015 rent.com Rental Market Report

“68% of property managers predict that rental rates will continue to rise in the next year by an average of 8%”

CNBC

“The primary reasons cited for the latest rises were increasing demand and low inventory. Vacancy rates for rental housing nationally dropped to a 20-year low of 6.8 percent in the second quarter…Rents and occupancies are currently hovering at historic highs as supply isn't keeping up with demand.”

 Bottom Line

If you are one of the many renters debating a home purchase, meet with a real estate professional in your area who can show you your options, before your rent goes up!

Monday, November 30, 2015

Renting to avoid a mortgage payment?

Some people rent in order to avoid the commitment of a mortgage payment. A renter is still paying a mortgage - it just happens to be for someone else. 


Rent vs. Buy: Either Way You're Paying A Mortgage | Keeping Current Matters
There are some people that have not purchased a home because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that, unless you are living with your parents rent free, you are paying a mortgage - either your mortgage or your landlord’s.
As The Joint Center for Housing Studies at Harvard University explains:
“Households must consume housing whether they own or rent. Not even accounting for more favorable tax treatment of owning, homeowners pay debt service to pay down their own principal while households that rent pay down the principal of a landlord plus a rate of return.  
That’s yet another reason owning often does—as Americans intuit—end up making more financial sense than renting.”
Christina Boyle, a Senior Vice President, Head of Single-Family Sales & Relationship Management at Freddie Mac, explains another benefit of securing a mortgage vs. paying rent:
“With a 30-year fixed rate mortgage, you’ll have the certainty & stability of knowing what your mortgage payment will be for the next 30 years – unlike rents which will continue to rise over the next three decades.”
As an owner, your mortgage payment is a form of ‘forced savings’ that allows you to have equity in your home that you can tap into later in life. As a renter, you guarantee your landlord is the person with that equity.
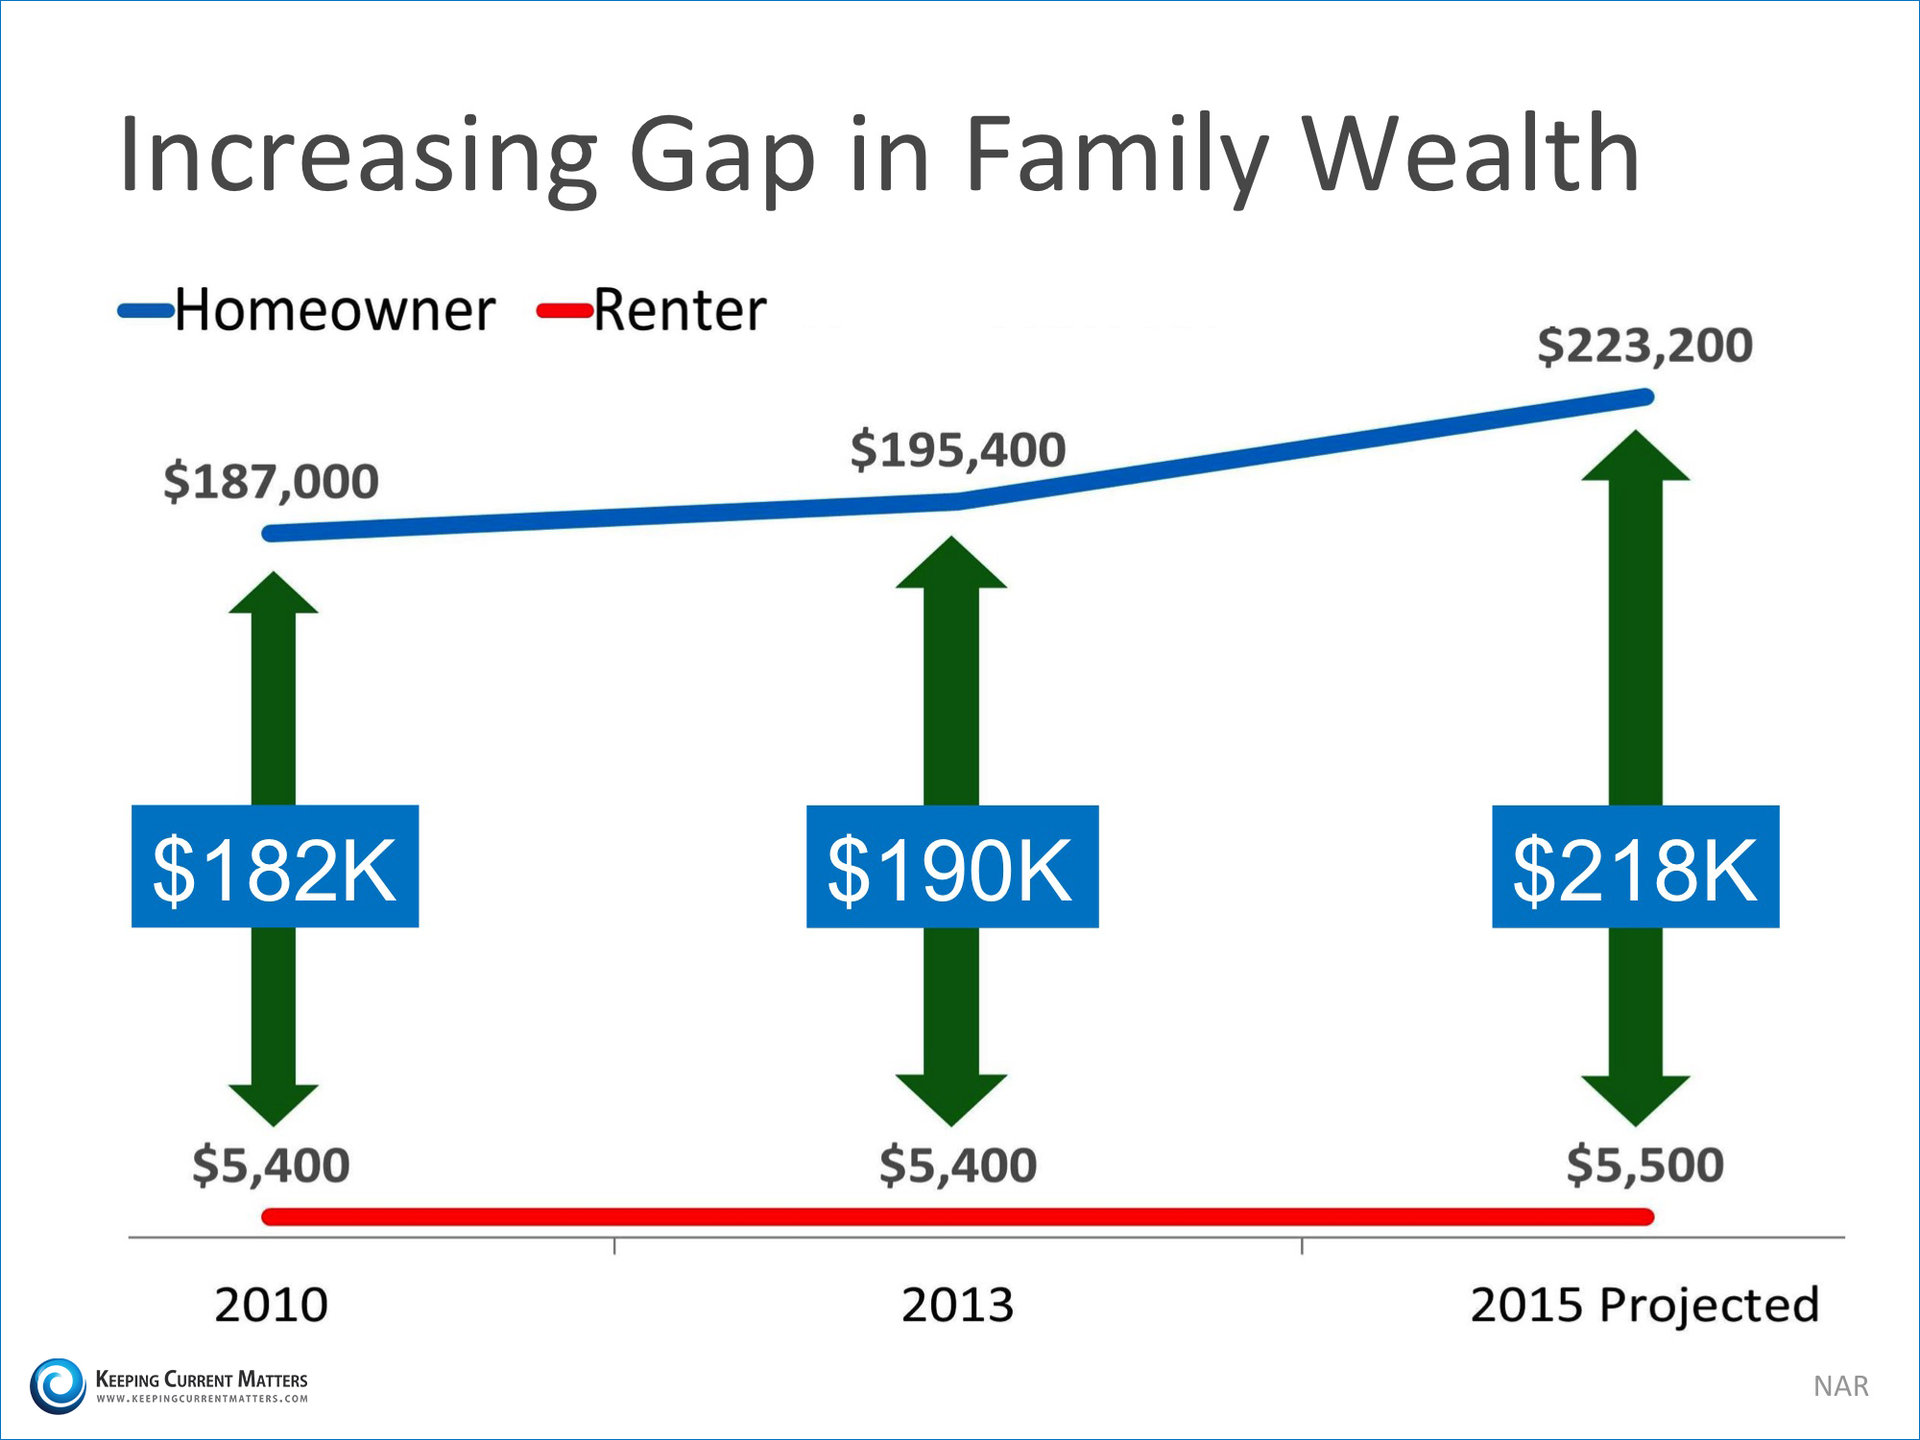
The graph below shows the widening gap in net worth between a homeowner and a renter:
Increasing Gap in Family Wealth | Keeping Current Matters

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, owning might make more sense than renting with home values and interest rates projected to climb.

Tuesday, July 21, 2015

Need a reason to buy a home, instead of renting one?

  Check out these Keeping Current Matters statistics...

Stop Paying Your Landlord's Mortgage | Keeping Current Matters
There are some people that have not purchased a home because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that, unless you are living with your parents rent free, you are paying a mortgage - either your mortgage or your landlord’s.
As The Joint Center for Housing Studies at Harvard University explains:
“Households must consume housing whether they own or rent. Not even accounting for more favorable tax treatment of owning, homeowners pay debt service to pay down their own principal while households that rent pay down the principal of a landlord plus a rate of return.  
That’s yet another reason owning often does—as Americans intuit—end up making more financial sense than renting.”
Christina Boyle, a Senior Vice President, Head of Single-Family Sales & Relationship Management at Freddie Mac, explains another benefit of securing a mortgage vs. paying rent:
“With a 30-year fixed rate mortgage, you’ll have the certainty & stability of knowing what your mortgage payment will be for the next 30 years – unlike rents which will continue to rise over the next three decades.”
As an owner, your mortgage payment is a form of ‘forced savings’ which allows you to have equity in your home that you can tap into later in life. As a renter, you guarantee the landlord is the person with that equity.
The graph below shows the widening gap in net worth between a homeowner and a renter:
Increasing Gap in Family Wealth | Keeping Current Matters

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, owning might make more sense than renting since home values and interest rates are projected to climb.

Monday, July 20, 2015

Should I sell, or should I rent...

Looking to move, but not sure if you should sell your current home, or rent it instead?  Read what Keeping Current Matters has to say...


Should I Rent My House Instead of Selling It?  | Keeping Current Matters
The results of Fannie Mae’s June 2015 National Housing Survey, were just released showing that more and more homeowners are warming up to the idea that now may be a great time to sell their home.
The amount of respondents that stated that now is a good time to sell rose three percentage points to a survey high of 52%; which may translate to a healthier market as more homes are listed in the coming months.
At the same time “the percentage of respondents who expect home rental prices to go up rose to 59% – a new survey high.” Doug Duncan, senior vice president and chief economist at Fannie Mae, gave this insight: “The expectation of higher rents is a natural outgrowth of increasing household formation by newly employed individuals putting upward pressure on rental rates.”
There is a chance that those who believe rental prices will rise may consider renting their house rather than selling it at this time.
However, if you have no desire to actually become an educated investor in this sector, you may be headed for more trouble than you were looking for. Are you ready to be a landlord?
Before renting your home, you should answer the following questions to make sure this is the right course of action for you and your family.

10 Questions to ask BEFORE renting your home

  1. How will you respond if your tenant says they can’t afford to pay the rent this month because of more pressing obligations? (This happens most often during holiday season and back-to-school time when families with children have extra expenses).
  2. Because of the economy, many homeowners cannot make their mortgage payment. What percentage of tenants do you think cannot afford to pay their rent?
  3. Have you interviewed experienced eviction attorneys in case a challenge does arise?
  4. Have you talked to your insurance company about a possible increase in premiums as liability is greater in a non-owner occupied home?
  5. Will you allow pets? Cats? Dogs? How big a dog?
  6. How will you actually collect the rent? By mail? In person?
  7. Repairs are part of being a landlord. Who will take tenant calls when necessary repairs come up?
  8. Do you have a list of craftspeople readily available to handle these repairs?
  9. How often will you do a physical inspection of the property?
  10. Will you alert your current neighbors that you are renting the house?

Bottom Line

Renting out residential real estate historically is a great investment. However, it is not without its challenges. Make sure you have decided to rent the house because you want to be an investor, not because you are hoping to get a few extra dollars by postponing a sale.