Showing posts with label buy vs rent. Show all posts

Wednesday, February 6, 2019

Is the lack of a sizable down payment holding you back from buying a home? Don't let it!

One More Time… You Do Not Need 20% Down to Buy a Home
One More Time... You Do Not Need 20% Down to Buy a Home | MyKCM
The largest obstacle renters face when planning to buy a home is saving for a down payment. This challenge is amplified by rising rents, which has eaten into the amount of money renters have leftover for savings each month after paying expenses.
In combination with higher rents, survey after survey has shown that non-homeowners (renters and those living rent-free with family or friends) believe they need to save upwards of 20% for their down payment!
According to the “Barriers to Accessing Homeownership” study commissioned in partnership between the Urban Institute, Down Payment Resource, and Freddie Mac, 39% of non-homeowners and 30% of those who already own a home believe they need more than a 20% down payment.
The percentage of those who are aware of low down payment programs (those under 5%) is surprisingly low at 12% for non-homeowners and 13% for homeowners.
In a recent Convergys Analytics report, they found that 49% of renters believe they need at least a 20% down payment.
The median down payment on loans approved in 2018 was only 5%! Those waiting until they have over 20% may already have enough saved to buy now!
There are over 45 million millennials (33%) who are mortgage ready right now, meaning their income, debt, and credit scores would all allow them to qualify for a mortgage today!

Bottom Line

If your five-year plan includes buying a home, let’s get together to determine what it will take to make that plan a reality. You may be closer to your dream than you realize!

Thursday, November 29, 2018

In a lot of markets buying a home is cheaper than renting.

Rents Are on The Rise: Don’t Get Caught in The Rental Trap!

Rents Are on The Rise: Don’t Get Caught in The Rental Trap! | MyKCM
There are many benefits to homeownership, but one of the top benefits is protecting yourself from rising rents by locking in your housing cost for the life of your mortgage.

Don’t Become Trapped 

A recent article by Apartment List addressed rising rents by stating:
Our national rent index is up 0.1 percent month-over-month, marking the sixth straight month of increasing rents. Year-over-year growth now stands at 1.2 percent.”
The article continues, explaining that:
Rents increased month-over-month in 62 of the nation’s 100 largest cities, down significantly from the 85 cities that saw rents rise last month. That said, rents are still up year-over-year in most of the nation’s largest markets — 77 of the 100 largest cities have seen rents increase over the past twelve months.”
Additionally, Urban Land Magazine explained that,
Currently, nearly half (47 percent) of renter households are cost burdened (i.e., paying more than 30 percent of income for housing), while 25 percent (totaling 11 million households) are severely cost burdened, paying over 50 percent of their total household income for rent.”
These households struggle to save for a rainy day and pay other bills, including groceries and healthcare.

It’s Cheaper to Buy Than Rent

As we have previously mentioned, the results of the latest Rent vs. Buy Report from Trulia show that homeownership remains cheaper than renting with a traditional 30-year fixed rate mortgage in the 100 largest metro areas in the United States.
The updated numbers show that the range is an average of 2% less expensive in Honolulu (HI), all the way up to 48.9% less expensive in Detroit (MI), and 26.3% nationwide!

Know Your Options

Perhaps you have already saved enough to buy your first home. A nationwide survey of about 1,166 renters found that 34% said they rent because they cannot afford to buy, 29% said they cannot afford to buy where they live, and nearly a quarter (24%) were saving to buy.
Many first-time homebuyers who believe that they need a large down payment may be holding themselves back from their dream homes. As we have reported before, in many areas of the country, a first-time homebuyer can save for a 3% down payment in less than two years. You may have already saved enough!

Bottom Line

Don’t get caught in the trap that so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Let’s get together to determine if you can qualify for a mortgage today!
Sunday, November 25, 2018

Don't believe everything you read - rent costs are up in a lot of area, making buying a home a better economic decision

75% of Renters Have Been Misinformed

75% of Renters Have Been Misinformed | MyKCM
Recently, multiple headlines have been written asserting that homeownership is less affordable today than at any other time in the last decade. Though the headlines are accurate, they lack context and lead too many Americans to believe that they can’t partake in a major part of the American Dream – owning a home.
In 2008, the housing market crashed and home values fell by as much as 60% in certain markets. This was the major trigger to the Great Recession we experienced from 2008 to 2010. To come back from that recession, mortgage interest rates were pushed down to levels that were never seen before.
For the last ten years, you could purchase a home at a dramatically discounted price and attain a mortgage at a historically low mortgage rate.
Affordability skyrocketed.
Now that home values have returned to where they should be, and mortgage rates are beginning to increase, it is less affordable to own a home than it was over the last ten years.
However, what is not being reported is that it is MORE AFFORDABLE to own a home today than at any other time since 1985 (when data was first collected on this point).
If you take out the years after the crash, affordability today is greater than it has been at almost any time in American history.
This has not been adequately reported which has led to many Americans believing that they cannot currently afford a home.
As an example, the latest edition of Freddie Mac’s Research: Profile of Today’s Renter reveals that 75% of renters now believe it is more affordable to rent than to own their own homes. This percentage is the highest ever recorded. The challenge is that this belief is incorrect. Study after study has proven that in today’s market, it is less expensive to own a home than it is to rent a home in the United States.
Thankfully, some are starting to see this situation and accurately report on it. The National Association of Realtors, in their 2019 Housing Forecast, mentions this concern:
“While the U.S. is experiencing historically normal levels of affordability, potential buyers may be staying out of the market because of perceived problems with affordability.”

Bottom Line

If you are one of the many renters who would like to own their own homes, let’s get together to find out if homeownership is affordable for you right now.

Monday, October 29, 2018

Wouldn't you rather build your own equity, as opposed to someone else's?

Rent or Buy: Either Way You’re Paying A Mortgage!

Rent or Buy: Either Way You’re Paying A Mortgage! | MyKCM

There are some people who have not purchased homes because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize, however, that unless you are living with your parents rent-free, you are paying a mortgage – either yours or your landlord’s.
As Entrepreneur Magazine, a premier source for small business, explained in their article, “12 Practical Steps to Getting Rich”:
“While renting on a temporary basis isn’t terrible, you should most certainly own the roof over your head if you’re serious about your finances. It won’t make you rich overnight, but by renting, you’re paying someone else’s mortgage. In effect, you’re making someone else rich.”
With home prices rising, many renters are concerned about their house-buying power. Mark Fleming, Chief Economist at First American, explained:
Over the last three years, renter house-buying power has increased fast enough to keep pace with house price appreciation, so the share of homes that a renter can afford to buy has remained the same since 2015.
Although mortgage rates are expected to rise, they are still low by historic standards, and real household incomes are the highest they have ever been. Assuming this trend continues, our measure of affordability, which takes into account income, interest rates, and house prices, indicates that homeownership is still within reach for renters.”
As an owner, your mortgage payment is a form of ‘forced savings’ which allows you to build equity in your home that you can tap into later in life. As a renter, you guarantee the landlord is the person building that equity.
Interest rates are still at historic lows, making it one of the best times to secure a mortgage and make a move into your dream home. Freddie Mac’s latest report shows that rates across the country were at 4.51% last week.

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, now may be the time to buy.

Wednesday, October 17, 2018

In a lot of markets buying a home is cheaper than renting.


Rents Are on The Rise: Don’t Get Caught in The Rental Trap!


Rents Are on The Rise: Don’t Get Caught in The Rental Trap! | MyKCM
There are many benefits to homeownership, but one of the top benefits is protecting yourself from rising rents by locking in your housing cost for the life of your mortgage.

Don’t Become Trapped 

A recent article by Apartment List addressed rising rents by stating:
Our national rent index is up 0.1 percent month-over-month, marking the sixth straight month of increasing rents. Year-over-year growth now stands at 1.2 percent.”
The article continues, explaining that:
Rents increased month-over-month in 62 of the nation’s 100 largest cities, down significantly from the 85 cities that saw rents rise last month. That said, rents are still up year-over-year in most of the nation’s largest markets — 77 of the 100 largest cities have seen rents increase over the past twelve months.”
Additionally, Urban Land Magazine explained that,
Currently, nearly half (47 percent) of renter households are cost burdened (i.e., paying more than 30 percent of income for housing), while 25 percent (totaling 11 million households) are severely cost burdened, paying over 50 percent of their total household income for rent.”
These households struggle to save for a rainy day and pay other bills, including groceries and healthcare.

It’s Cheaper to Buy Than Rent

As we have previously mentioned, the results of the latest Rent vs. Buy Report from Trulia show that homeownership remains cheaper than renting with a traditional 30-year fixed rate mortgage in the 100 largest metro areas in the United States.
The updated numbers show that the range is an average of 2% less expensive in Honolulu (HI), all the way up to 48.9% less expensive in Detroit (MI), and 26.3% nationwide!

Know Your Options

Perhaps you have already saved enough to buy your first home. A nationwide survey of about 1,166 renters found that 34% said they rent because they cannot afford to buy, 29% said they cannot afford to buy where they live, and nearly a quarter (24%) were saving to buy.
Many first-time homebuyers who believe that they need a large down payment may be holding themselves back from their dream homes. As we have reported before, in many areas of the country, a first-time homebuyer can save for a 3% down payment in less than two years. You may have already saved enough!

Bottom Line

Don’t get caught in the trap that so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Let’s get together to determine if you can qualify for a mortgage today!

Friday, August 3, 2018

If you are debating on whether to purchase a home, or continue to rent, take a minute to read this article. Research by Trulia shows that it really is cheaper to buy than rent (except for San Francisco!)

Buying Is Now 26.3% Cheaper Than Renting in the US

Buying Is Now 26.3% Cheaper Than Renting in the US | MyKCM
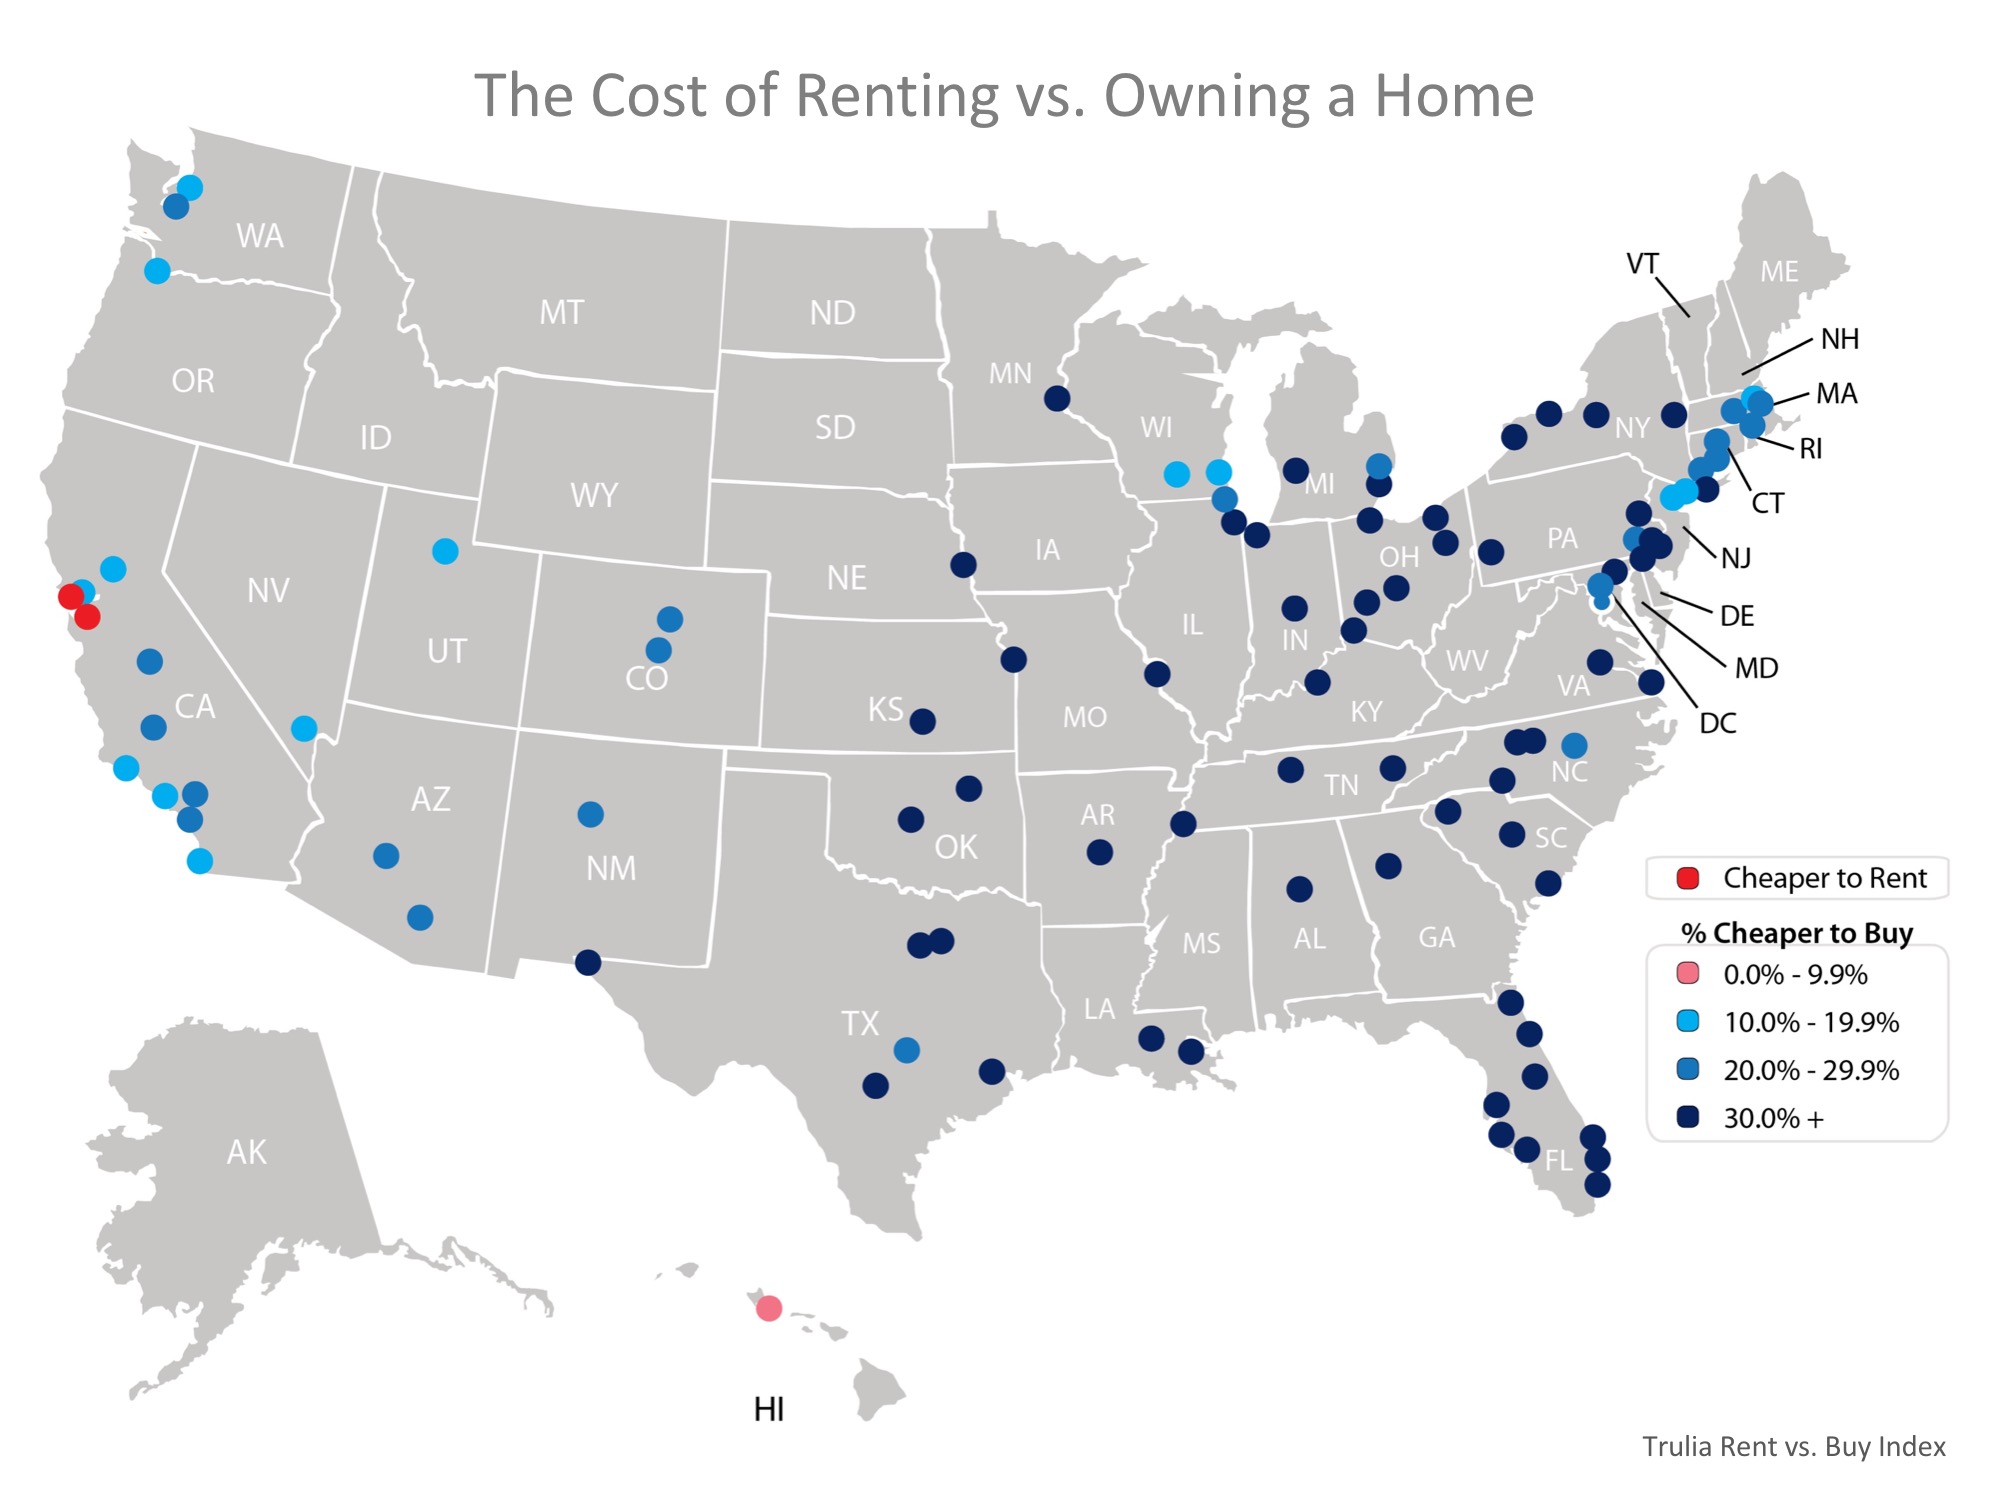
The results of the latest Rent vs. Buy Report from Trulia show that homeownership remains cheaper than renting, with a traditional 30-year fixed rate mortgage, in 98 of the 100 largest metro areas in the United States.
In the six years that Trulia has conducted this study, this is the first time that it was cheaper to rent than buy in any of the metropolitan areas.
It’s no surprise, however, that those two metros are San Jose and San Francisco, CA, where median home prices have jumped to over $1 million dollars this year. Home values in San Jose have risen 29% in the last year, while rents have remained relatively unchanged.
For the 98 metros where homeownership wins out, 97 of them show a double-digit advantage when buying. The range is an average of 2.0% less expensive in Honolulu (HI), all the way up to 48.9% in Detroit (MI), and 26.3% nationwide!
Below is a map of the 100 metros that were studied. The darker the blue dot on the metro, the cheaper it is to buy there.
Buying Is Now 26.3% Cheaper Than Renting in the US | MyKCM
In order to calculate the true cost of renting vs. buying, Trulia includes all assumed renting costs, including one-time costs (like security deposits), and compares them to the monthly costs of owning a home (insurance, mortgage payments, taxes, and maintenance) including one-time costs (down payments, closing costs, sale proceeds). They also assume that households stay in their home for seven years, put down a 20% down payment, and take out a 30-year fixed rate mortgage. The full methodology is included with the study results here.
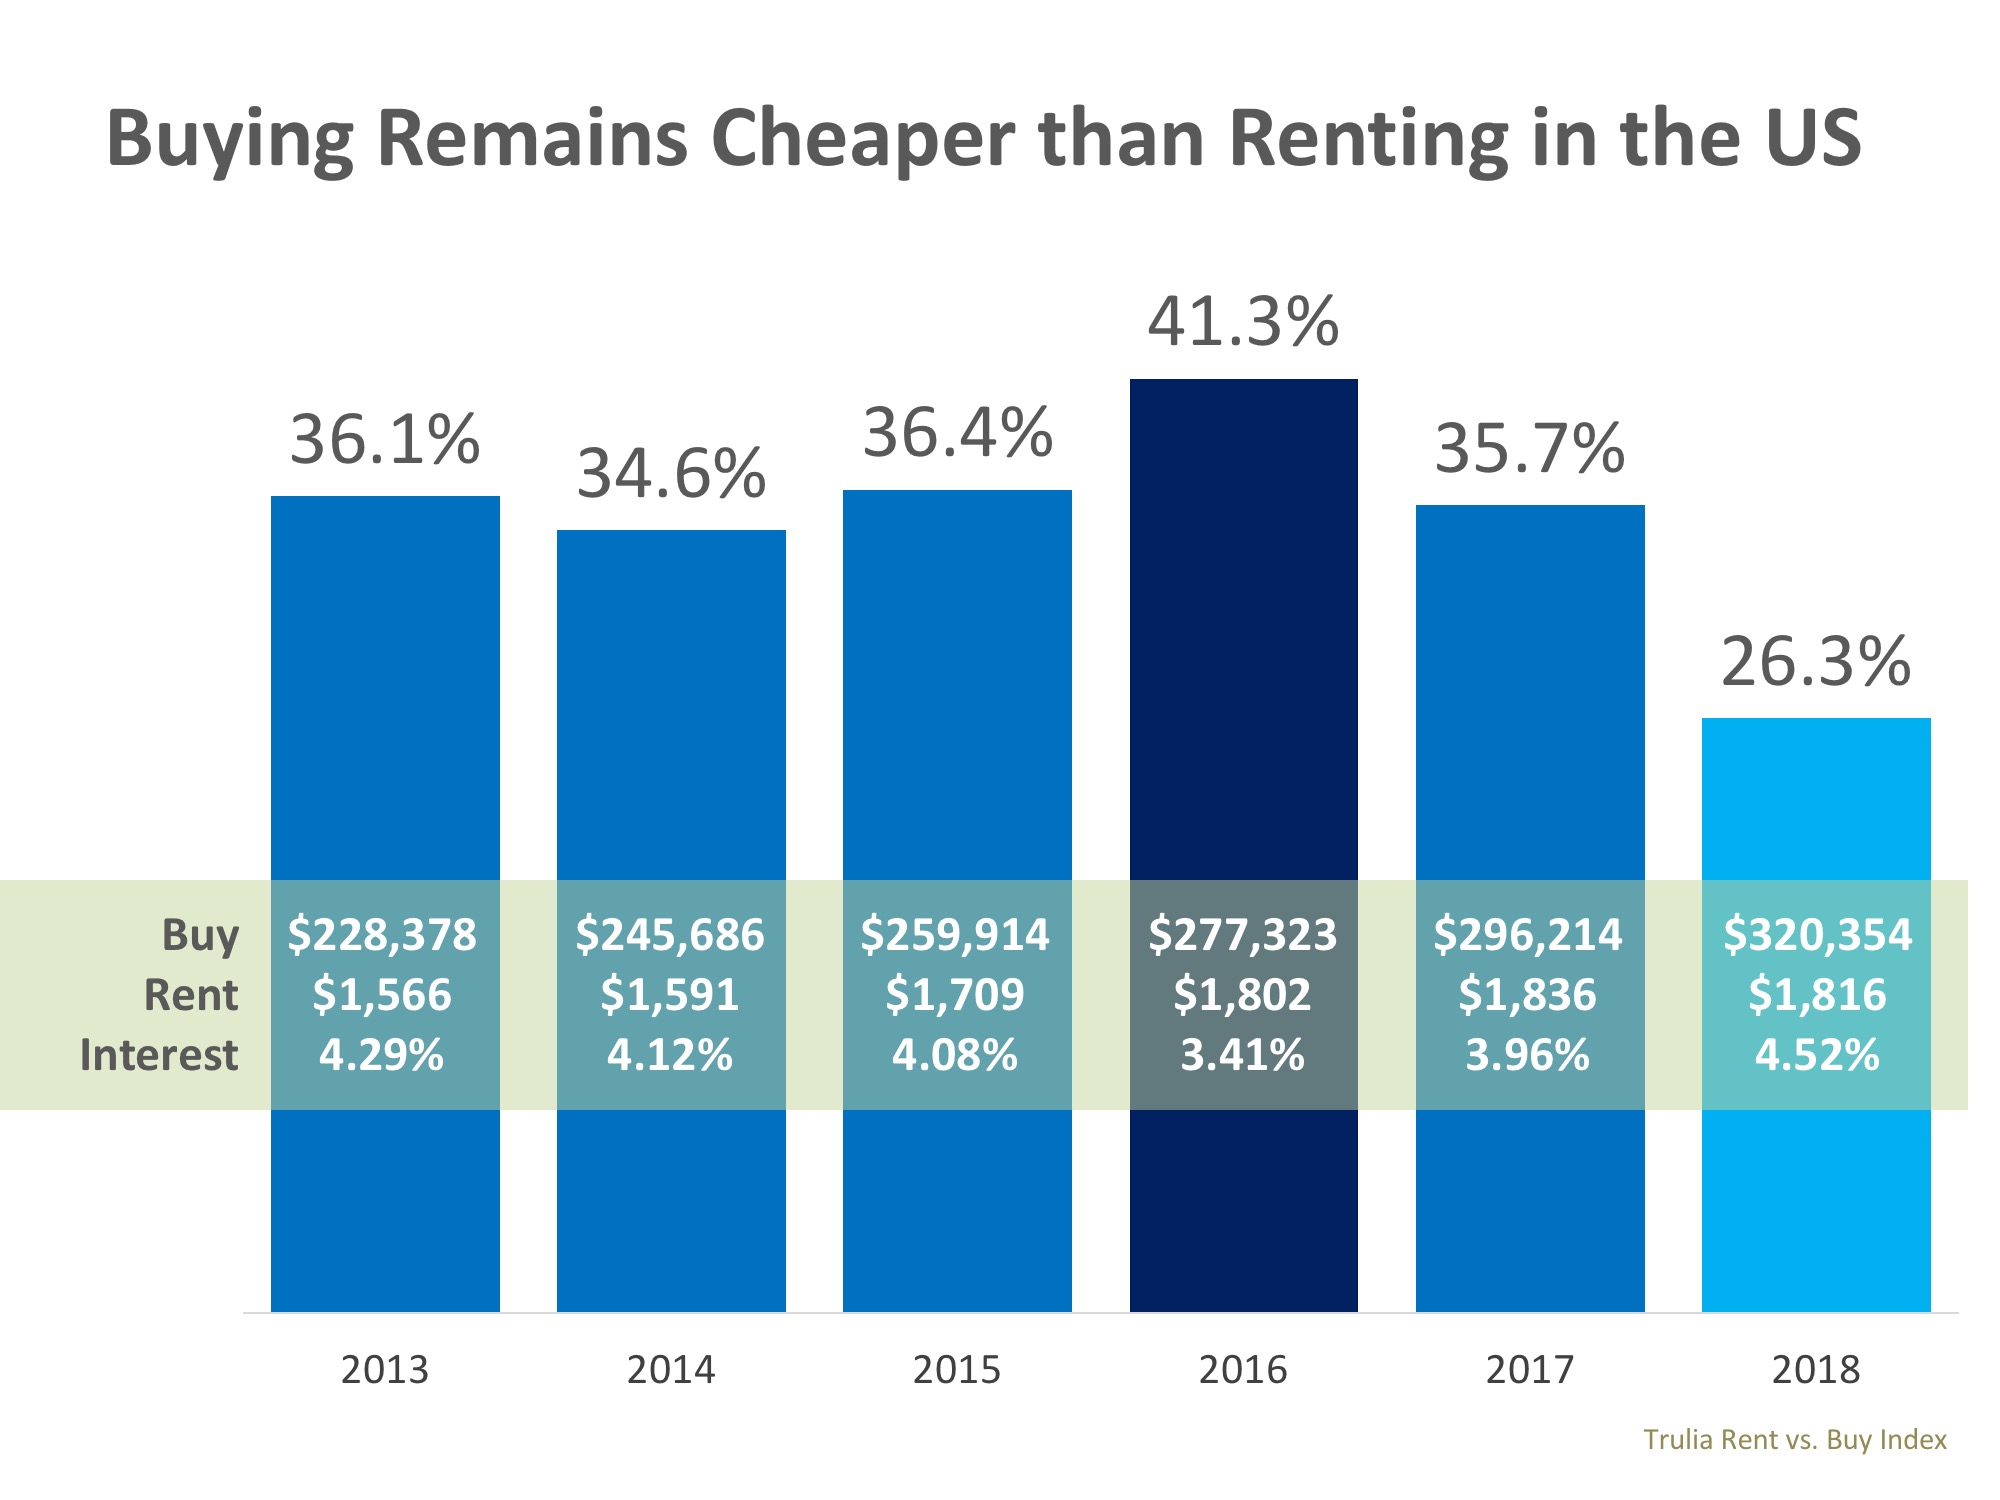
Below is a chart created with the data from the last six years of the study, showing the impact of the median home price, rental price, and 30-year fixed rate interest rate used to calculate the ‘cheaper to buy’ metric.
Buying Is Now 26.3% Cheaper Than Renting in the US | MyKCM
In 2016, when buying was 41.3% less expensive than renting, the average mortgage rate was the driving force behind the difference. Rates this year are the highest they have been in six years which has narrowed the gap, all while home price appreciation has also been driven up by a lack of homes for sale.
Cheryl Young, Trulia’s Chief Economist, had this to say,
“One point deserves emphasizing: The ultra-costly San Francisco Bay Area is not a harbinger for the nation as a whole. While renting may outweigh buying in San Jose and San Francisco, it is unlikely that renting will tip the scales nationally anytime soon.”

Bottom Line

Homeownership provides many benefits beyond the financial ones. If you are one of the many renters out there who would like to evaluate your ability to buy this year, let’s get together to find your dream home.

Thursday, December 14, 2017

If you choose to rent to avoid paying a mortgage, you still are doing that. It is just someone else's mortgage that you are paying...

Renting or Buying…Either Way, You're Paying Someone's Mortgage

Renting or Buying…Either Way, You're Paying Someone's Mortgage | MyKCM
There are some people who have not purchased homes yet because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that, unless you are living with your parents rent-free, you are paying a mortgage – either yours or your landlord’s.
As Entrepreneur Magazine, a premier source for small business, explained in their article, “12 Practical Steps to Getting Rich,”
“While renting on a temporary basis isn’t terrible, you should most certainly own the roof over your head if you’re serious about your finances. It won’t make you rich overnight, but by renting, you’re paying someone else’s mortgage. In effect, you’re making someone else rich.”
Christina Boyle, Senior Vice President and head of the Single-Family Sales & Relationship Managementorganization at Freddie Mac, explains another benefit of securing a mortgage vs. paying rent:
“With a 30-year fixed rate mortgage, you’ll have the certainty & stability of knowing what your mortgage payment will be for the next 30 years – unlike rents which will continue to rise over the next three decades.”
As an owner, your mortgage payment is a form of ‘forced savings’ which allows you to build equity in your home that you can tap into later in life. As a renter, you guarantee the landlord is the person with that equity.
Interest rates are still at historic lows, making it one of the best times to secure a mortgage and make a move into your dream home. Freddie Mac’s latest report shows that rates across the country were at 3.94% last week.

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, now may be the time to buy.

Tuesday, December 5, 2017

The cost of renting can be more than the cost of buying a home...

The Cost of Renting vs. Buying a Home [INFOGRAPHIC]

The Cost of Renting vs. Buying a Home [INFOGRAPHIC] | MyKCM

Some Highlights:

  • Historically, the choice between renting or buying a home has been a tough decision.
  • Looking at the percentage of income needed to rent a median-priced home today (29.2%) vs. the percentage needed to buy a median-priced home (15.8%), the choice becomes obvious.
  • Every market is different. Before you renew your lease again, find out if you can put your housing costs to work by buying this year!

Monday, November 27, 2017

Studies consistently show that homeowners have a greater net worth than renters.

Net Worth of Homeowners 44X Greater than Renters

Net Worth of Homeowners 44X Greater than Renters | MyKCM
Every three years, the Federal Reserve conducts their Survey of Consumer Finances in which they collect data across all economic and social groups. The latest survey data, covering 2013-2016 was released two weeks ago.
The study revealed that the 2016 median net worth of homeowners was $231,400 - a 15% increasesince 2013. At the same time, the median net worth of renters decreased by 5% ($5,200 today compared to $5,500 in 2013).
These numbers reveal that the net worth of a homeowner is over 44 times greater than that of a renter.

Owning a home is a great way to build family wealth

As we’ve said before, simply put, homeownership is a form of ‘forced savings.’ Every time you pay your mortgage, you are contributing to your net worth by increasing the equity in your home.
That is why, for the fourth year in a row, Gallup reported that Americans picked real estate as the best long-term investment. This year’s results showed that 34% of Americans chose real estate, followed by stocks at 26% and then gold, savings accounts/CDs, or bonds.

Greater equity in your home gives you options

If you want to find out how you can use the increased equity in your home to move to a home that better fits your current lifestyle, let’s get together to discuss the process.

Monday, October 9, 2017

A pet. That is one of the top reasons Millennials choose to purchase their own home. What drove you to do it?

Top 5 Reasons Why Millennials Choose to Buy [INFOGRAPHIC]

Top 5 Reasons Why Millennials Choose to Buy [INFOGRAPHIC] | MyKCM

Some Highlights:

  • “The majority of millennials said they consider owning a home more sensible than renting for both financial and lifestyle reasons — including control of living space, flexibility in future decisions, privacy and security, and living in a nice home.”
  • The top reason millennials choose to buy is to have control over their living space, at 93%.
  • Many millennials who rent a home or apartment prior to buying their own homes dream of the day that they will be able to paint the walls whatever color they'd like, or renovate an outdated part of their living space.

Thursday, September 28, 2017

Building equity, while owning a home, helps increase your personal wealth...

How Your Home’s Value Grows Your Family’s Wealth

How Your Home’s Value Grows Your Family’s Wealth | MyKCM
Over the next five years, home prices are expected to appreciate 3.64% per year on average and to grow by 18.4% cumulatively, according to Pulsenomics’ most recent Home Price Expectation Survey.

So, what does this mean for homeowners and their equity position?

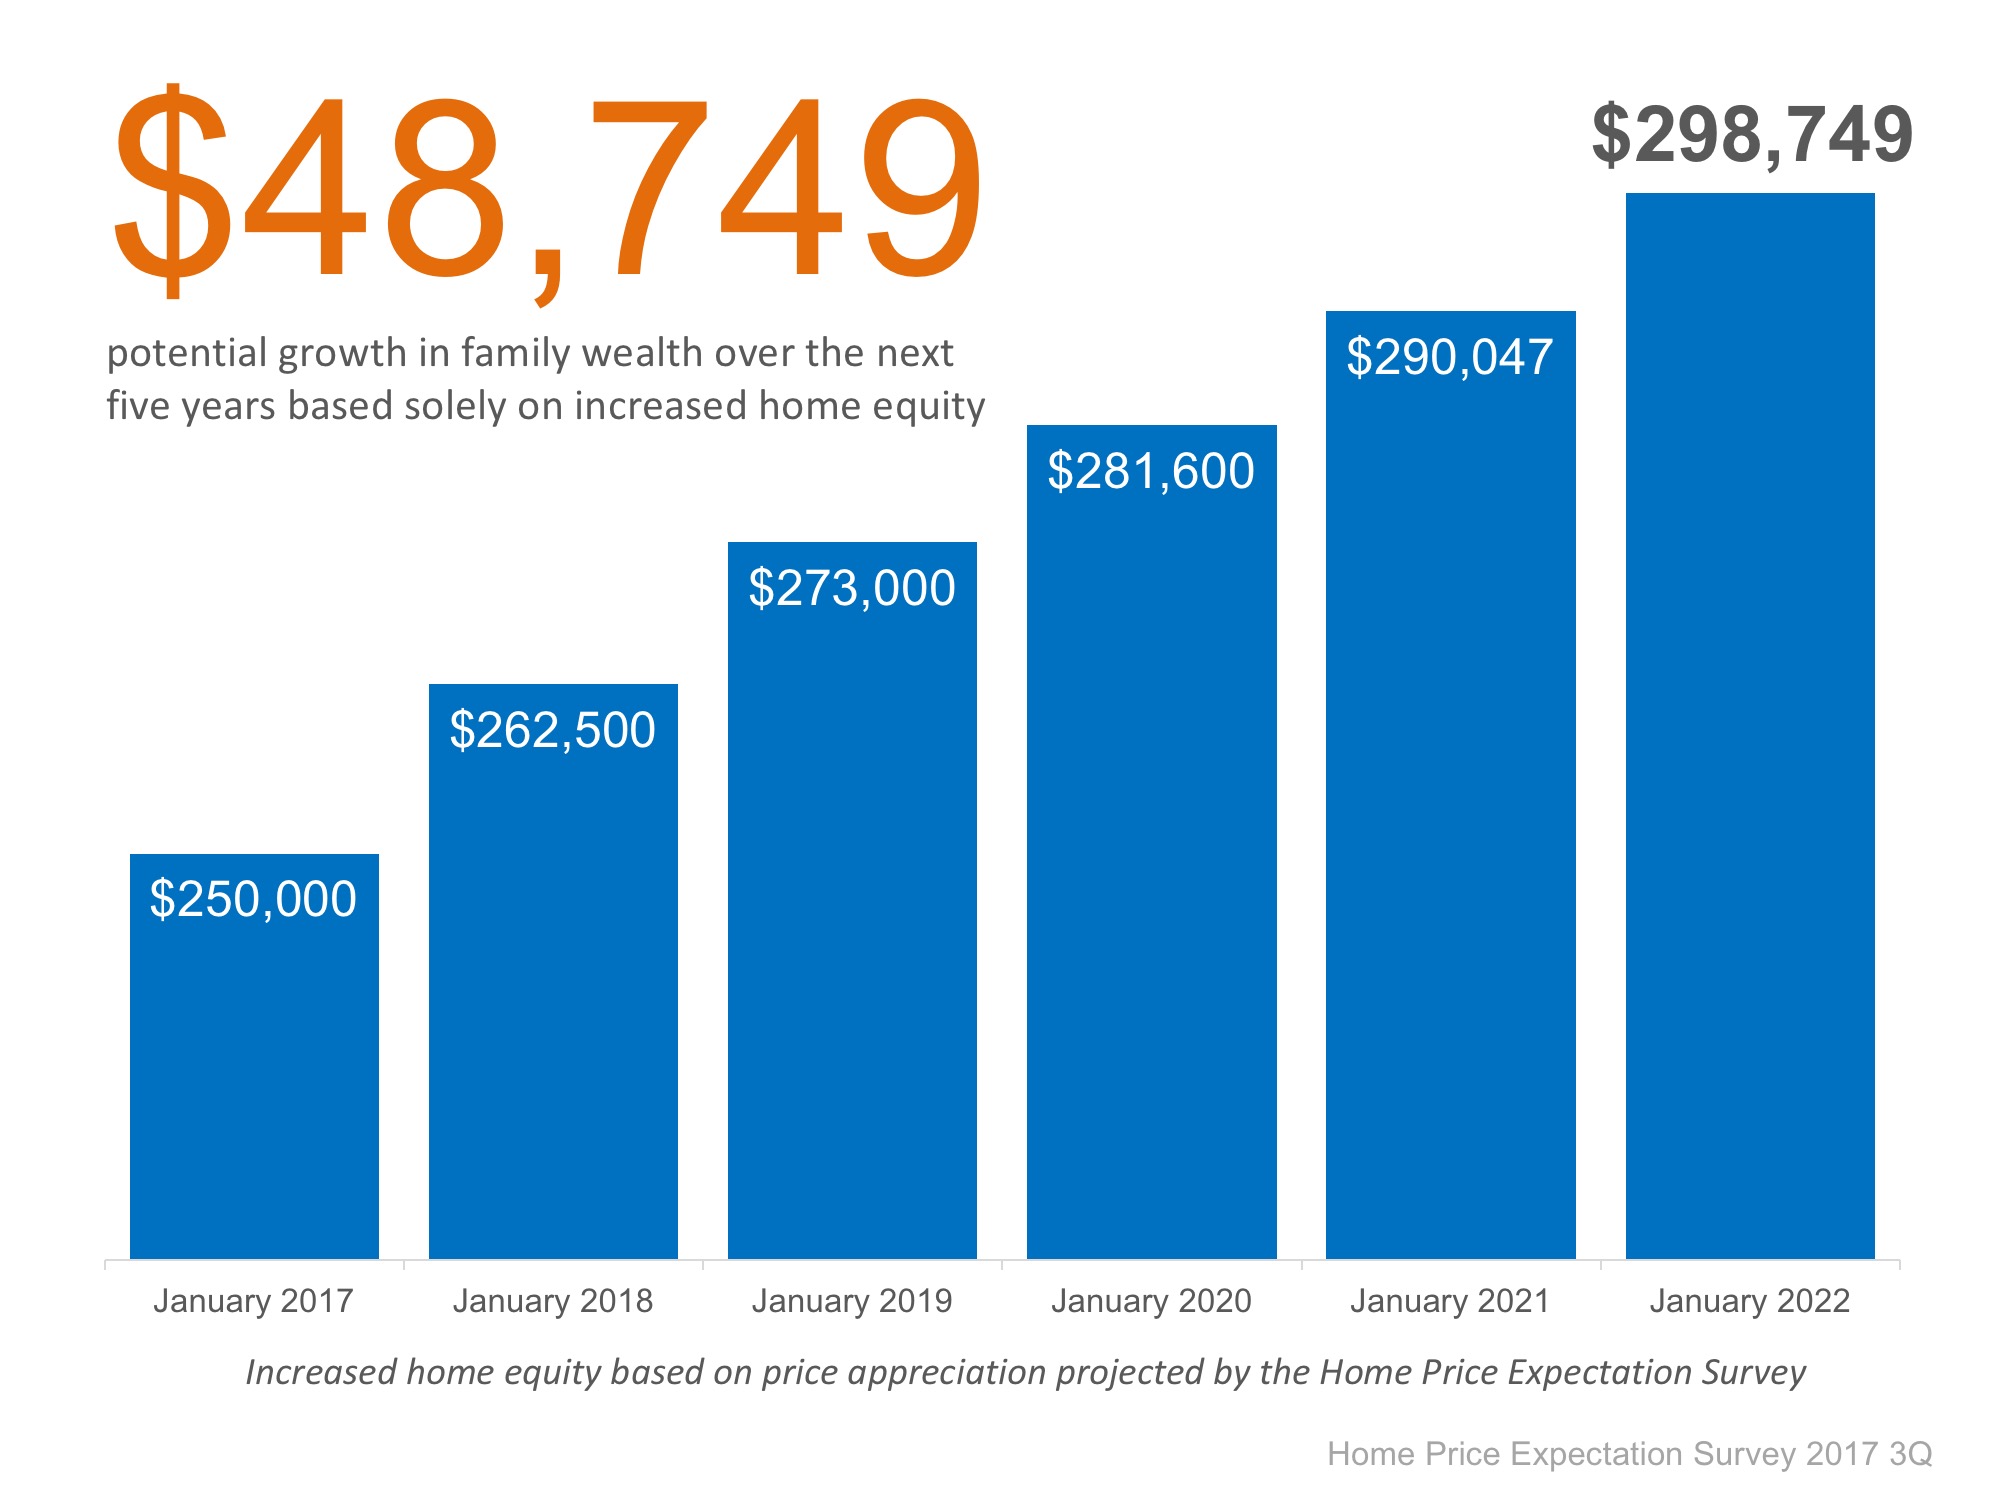
As an example, let’s assume a young couple purchased and closed on a $250,000 home in January. If we look at only the projected increase in the price of that home, how much equity will they earn over the next 5 years?
How Your Home’s Value Grows Your Family’s Wealth | MyKCM
Since the experts predict that home prices will increase by 5.0% this year alone, the young homeowners will have gained $12,500 in equity in just one year.
Over a five-year period, their equity will increase by nearly $49,000! This figure does not even take into account their monthly principal mortgage payments. In many cases, home equity is one of the largest portions of a family’s overall net worth.

Bottom Line

Not only is homeownership something to be proud of, but it also offers you and your family the ability to build equity you can borrow against in the future. If you are ready and willing to buy, find out if you are able to today!

Wednesday, September 27, 2017

More buyers are able to afford buying a home, simply because there are loans out there that don't require 10%+ down.

Number of Buyers Putting Down Less Than 10% Hits 7-Year High

Number of Buyers Putting Down Less Than 10% Hits 7-Year High | MyKCM
According to Black Knight Financial Service’s Mortgage Monitor Report, 1.5 million Americans have purchased a home with down payments under than 10% over the last 12 months. This is great news for buyers as this marks a 7-year high.
Many mortgage programs offered by agencies like Freddie Mac and Fannie Mae allow buyers to put down as low as 3% to purchase their dream homes. The strength of the housing market has aided buyers who used low-down-payment programs to buy. As a recent CNBC article points out,
“Defaults on recent low down payment loans, so far, are slow, but that is as much a factor of the good credit quality as it is the strength of the housing market. Home prices are rising incredibly fast, meaning those borrowers are gaining equity in their homes quickly.”
Low down payments aren’t just great for first-time homebuyers. These programs have allowed homeowners who want to capitalize on the equity they have in their homes to use the profit from their sale to pay off high-interest credit cards, fund education or even start a business.
According to a new Census Report, the Annual Survey of Entrepreneurs, home equity was used to start 7.3% of all businesses in the United States, which equates to over 284,000! The industries that saw the most growth from home equity are accommodation & food services, manufacturing and, retail trade.

Bottom Line

Gone are the days of ‘20% down or no mortgage.’ What could you build with the equity in your house? Let’s get together today to evaluate your ability to achieve your dreams today!

Monday, September 25, 2017

Yes, the higher your credit score the easier time you may have securing a mortgage. However, more than half of today's loans are approved for buyers with a FICO score below 750...

Don’t Disqualify Yourself… 52% of Approved Loans Have A FICO® Score Under 750

Don’t Disqualify Yourself… 52% of Approved Loans Have A FICO® Score Under 750 | MyKCM
The results of countless studies have shown that potential home buyers, and even current homeowners, have an inflated view of what is really required to qualify for a mortgage in today’s market.
One such study by the Wharton School of Business at the University of Pennsylvania revealed that many millennials have not yet considered purchasing homes simply because they don’t believe they can qualify for a mortgage.
A recent article about millennials by Realtor.com explained that:
About 72% of aspiring millennial buyers said they’re waiting because they can’t afford to buy…
The article also explained that 29% of millennials believe their credit scores are too low to buy.The problem here is the fact that they think they will be denied a mortgage is keeping them from even attempting to apply.
Ellie Mae’s Vice President Jonas Moe encouraged buyers to know their options before assuming that they won’t qualify for a mortgage:
“Many potential home buyers are ‘disqualifying’ themselves. You don’t need a 750 FICO® Score and a 20% down payment to buy.”

So, what credit score is necessary?

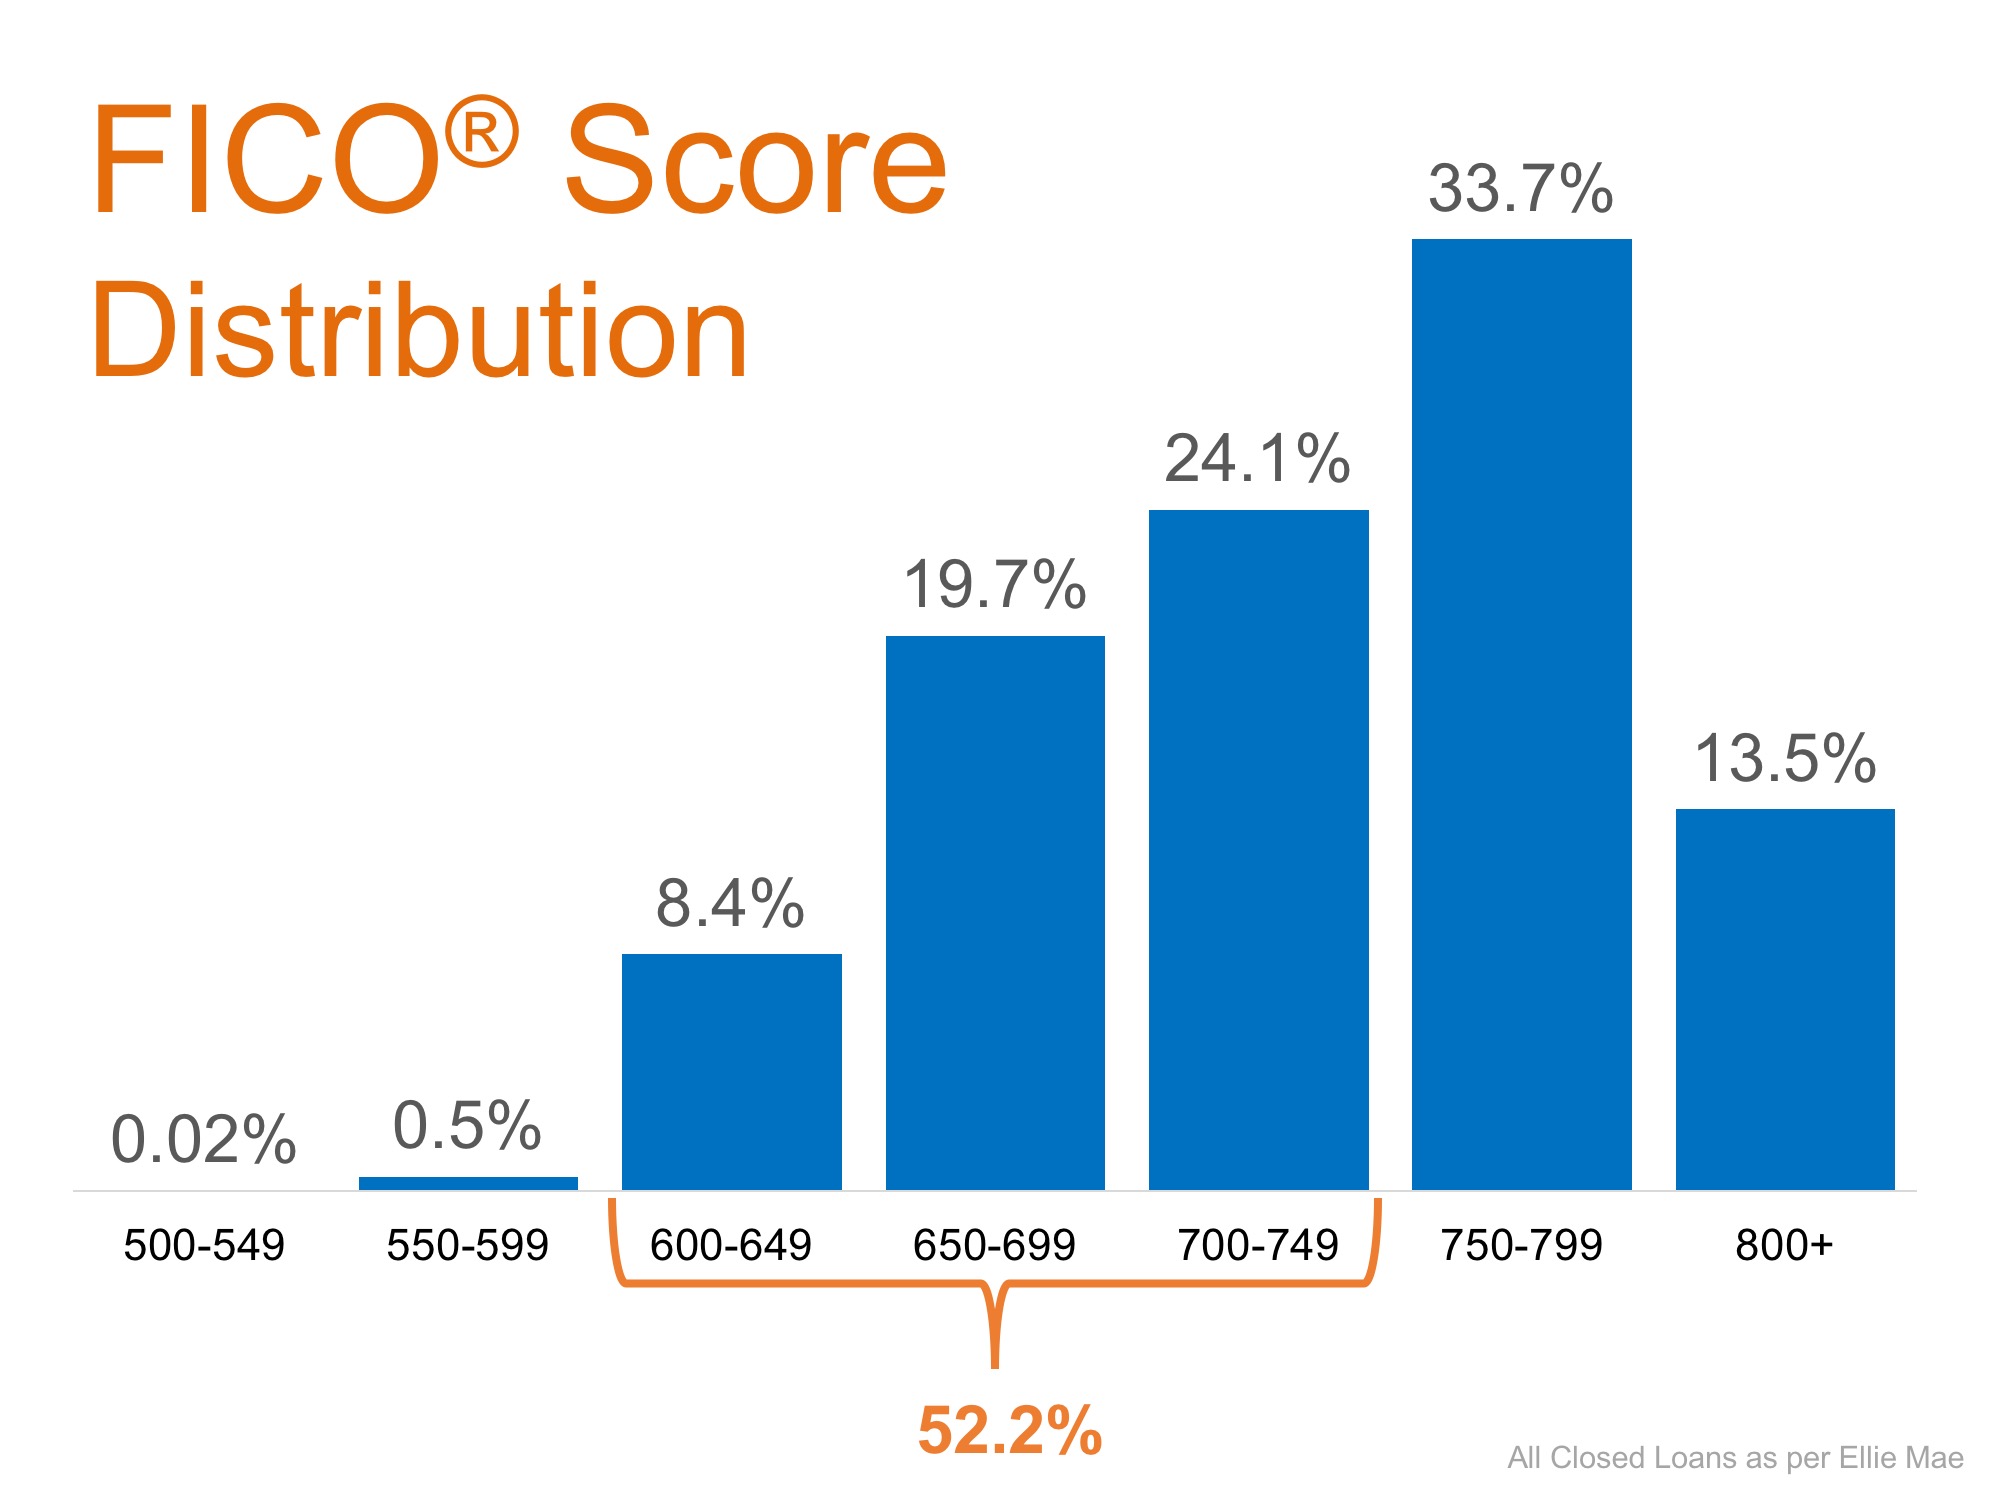
Below is a breakdown of the FICO® Score distribution of all closed (approved) loans in July from Ellie Mae’s latest Origination Report.
Don’t Disqualify Yourself… 52% of Approved Loans Have A FICO® Score Under 750 | MyKCM
Over 52% of all approved loans had a FICO® Score under 750. Many potential home buyers believe that they need a score over 780 to qualify.

Bottom Line

If owning a home of your own has always been your dream and you are ready and willing to buy, or if you are a homeowner who wants to move up, find out if you are able to! Let’s get together to determine if your dreams can become a reality sooner than you thought!

Tuesday, September 12, 2017

Buy a home and start building your net worth.

Homeowner’s Net Worth Is Still Greater Than a Renter’s

Homeowner’s Net Worth Is Still Greater Than a Renter’s | MyKCM
Every three years, the Federal Reserve conducts their Survey of Consumer Finances in which they collect data across all economic and social groups. The latest survey, which includes data from 2010-2013, reports that a homeowner’s net worth is 36 times greater than that of a renter ($194,500 vs. $5,400). 
The latest survey data, covering 2014-2016 will be released later this year. In the meantime, Lawrence Yun, the National Association of Realtors’ Chief Economist estimates that the gap has widened even further, to 45 times greater ($225,000 vs. $5,000)! 

Put Your Housing Cost to Work for You

As we’ve said before, simply put, homeownership is a form of ‘forced savings.’ Every time you pay your mortgage, you are contributing to your net worth. Every time you pay your rent, you are contributing to your landlord’s net worth.
The latest National Housing Pulse Survey from NAR reveals that 84% of consumers believe that purchasing a home is a good financial decision. William E. Brown comments:
“Despite the growing concern over affordable housing, this survey makes it clear that a strong majority still believe in homeownership and aspire to own a home of their own. Building equity, wanting a stable and safe environment, and having the freedom to choose their neighborhood remain the top reasons to own a home. 

Bottom Line

If you are interested in finding out if you could put your housing cost to work for you by purchasing a home, let’s get together and evaluate your ability to buy today!

Tuesday, August 29, 2017

Millennials are beginning to buy homes, which is a great boost for the first-time homebuyer market.

Millennial Homeownership Rate Increases

Millennial Homeownership Rate Increases | MyKCM
Recent headlines exclaimed the homeownership rate, as reported by the Census Bureau, rose again in the second quarter of 2017. What didn’t get much attention in the reports is that the homeownership rate for American households under the age of 35 increased a full percentage point from last quarter’s 34.3% to 35.3%. Millennials proved to have the highest increase of any age group.
This came as a surprise to some considering Millennials have come to be known as the “renter” generation. However, a new study by First American, 6 Trends Poised to Reshape Homeownership Demand, revealed reasons why homeownership numbers will continue to increase for Millennials.

Millennials are the most educated generation in the U.S.

Why does that matter? First American explains:
“Our model shows that, all other factors being equal, the likelihood of homeownership increases by 3 percent for those that earn a bachelor’s degree over those with a high school degree. The likelihood of homeownership jumps another 3 percent for those that earn a graduate degree.”
The more educated, the better the likelihood for homeownership. And, as we mentioned: Millennials are the most educated generation in the U.S.

Homes & marriage go together

Marriage is a key determinate in homeownership. According to an analysis by First American, the homeownership rate is 30% higher among married couples compared to non-married households.
Millennials have put off marriage in the pursuit of higher education. As this group ages, more and more will marry and purchase a home.

Parents buy houses

According to the study:
“The homeownership rate is 1.7% higher for households with one or two children compared to households with no children, and it is 5.4 percent higher for households with three or more children.”
The report goes on to say that as Millennials grow older there may be an increase in not just marriage but also in married couples with children. That will probably also create a “corresponding” increase in homeownership demand.

Wages and the economy

The study goes on to explain that recent gains in income growth and a strengthening economy will also help all generations (including Millennials) be more willing and able to purchase a new home.

Bottom Line

We guess the time has come to announce – Here come the Millennials!!

Monday, August 7, 2017

There are some exceptions, however it generally is better to buy than rent. Renting now? Start saving up for your downpayment.

Be Careful Not to Get Caught in The Rental Trap!

Be Careful Not to Get Caught in The Rental Trap! | MyKCM
There are many benefits to homeownership. One of the top benefits is being able to protect yourself from rising rents by locking in your housing cost for the life of your mortgage.

Don’t Become Trapped 

A recent article by ConsumerAffairs addressed the continuous rise in rents, stating:
“The cost of putting a roof over your head continues to go up. Not only are home prices still rising, but the cost of rent rose 0.5% in June.”
Additionally, in the Joint Center for Housing Studies at Harvard University’s 2017 State of the Nation’s Housing Report, it was revealed that,
“Despite a slight improvement from 2014, fully one-third of US households paid more than 30 percent of their incomes for housing in 2015. Renters continue to be more likely to face cost burdens…the number of cost-burdened renters (21 million) considerably outstrips the number of cost-burdened owners (18 million) even though nearly two-thirds of US households own their homes.”
These households struggle to save for a rainy day and pay other bills, including groceries and healthcare.

It’s Cheaper to Buy Than Rent 

As we have previously mentioned, the results of the latest Rent vs. Buy Report from Trulia shows that homeownership remains cheaper than renting with a traditional 30-year fixed rate mortgage in the 100 largest metro areas in the United States.
The updated numbers show that the range is an average of 3.5% less expensive in San Jose (CA), all the way up to 50.1% less expensive in Baton Rouge (LA), and 33.1% nationwide!

Know Your Options

Perhaps you have already saved enough to buy your first home. A nationwide survey of about 24,000 renters found that 80% of millennial renters plan to eventually buy a house, but 72% cite affordability as their primary obstacle. Aside from affordability, one in three millennial renters have concerns about their credit scores, and another 53% said that a down payment is an obstacle.
Many first-time homebuyers who believe that they need a large down payment may be holding themselves back from their dream homes. As we have reported before, in many areas of the country, a first-time home buyer can save for a 3% down payment in less than two years. You may have already saved enough!

Bottom Line

Don’t get caught in the trap that so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Let’s get together to determine if you can qualify for a mortgage now!

Thursday, July 27, 2017

More than 70% of first time home buyers put down less than 20% this spring. Looking to buy? Don't get caught up in these myths...

Home Buying Myths Slayed [INFOGRAPHIC]

Home Buying Myths Slayed [INFOGRAPHIC] | MyKCM

Some Highlights:

  • Interest rates are still below historic numbers.
  • 88% of property managers raised their rent in the last 12 months!
  • The credit score requirements for mortgage approval continue to fall.

Tuesday, July 25, 2017

Owning a home offers a multitude of benefits...

The 5 Greatest Benefits of Homeownership

The 5 Greatest Benefits of Homeownership | MyKCM
Recently, Freddie Mac reported on the benefits of homeownership. According to their report, here are the five benefits that “should be at the top of everyone’s list.”
  1. Homeownership can help you build equity over time.
  2. Your monthly payments will remain stable.
  3. You may have some tax benefits.
  4. You can take pride in ownership.
  5. Homeownership improves your community.
Let’s expand on each of Freddie Mac’s points:

Homeownership can help you build equity over time.

Every three years, the Federal Reserve conducts a Survey of Consumer Finances in which they collect data across all economic and social groups. The latest survey, which includes data from 2010-2013, reports that a homeowner’s net worth is 36 times greater than that of a renter ($194,500 vs. $5,400).
In a Forbes article, the National Association of Realtors’ (NAR) Chief Economist Lawrence Yun reported that now the net worth gap is 45 times greater.

Your monthly payments will remain stable.

When you purchase a home with a fixed rate mortgage, the majority of the payment (principle and interest) remain constant. On the other hand, rents continue to skyrocket. Your housing expense is much more stable if you own instead of rent.

You may have some tax benefits.

According to the Tax Policy Center’s Briefing Book -“A citizen’s guide to the fascinating (though often complex) elements of the federal Tax System” – there are several tax advantages to homeownership.
Here are four items from the Briefing Book:
  • Mortgage Interest Deduction
  • Property Tax Deduction
  • Imputed Rent
  • Profits from Home Sale

You can take pride in ownership.

Most surveys show that a major factor in purchasing a home is the freedom you have to design the home the way you want. From paint colors to yard accessories, you don’t need a landlord’s permission to make the house feel like a home.

Homeownership improves your community.

The National Association of Realtors recently released a study titled ‘Social Benefits of Homeownership and Stable Housing.’ The study explained:
“Homeownership does create social capital and provide residents with a platform from which to connect and interact with neighbors…Owning a home means owning part of a neighborhood, and a homeowner’s feelings of commitment to the home can arouse feelings of commitment to the neighborhood, which, in turn, can produce interactions with neighbors.”

Bottom Line

There are many benefits to homeownership. That is why it is still a critical piece of the American Dream.

Thursday, July 13, 2017

Renting isn't always the cheaper alternative...

The Cost of Renting vs. Buying in the US [INFOGRAPHIC]

The Cost of Renting vs. Buying in the US [INFOGRAPHIC] | MyKCM

Some Highlights:

  • Historically, the choice between renting or buying a home has been a tough decision.
  • Looking at the percentage of income needed to rent a median-priced home today (29.2%) vs. the percentage needed to buy a median-priced home (15.8%), the choice becomes obvious.
  • Every market is different. Before you renew your lease again, find out if you can put your housing costs to work by buying this year!

Tuesday, June 27, 2017

We hear this time and time again, homeowners tend to have a higher personal wealth than renters...

Homeownership Is a Good Financial Investment!

Homeownership Is a Good Financial Investment! | MyKCM
According to a recent report by Trulia“buying is cheaper than renting in 100 of the largest metro areas by an average of 33.1%.” The report may have some people thinking about buying a home instead of signing another lease extension, but does that make sense from a financial perspective?
Ralph McLaughlin, Trulia’s Chief Economist explains:
“Owning a home is one of the most common ways households build long-term wealth, as it acts like a forced savings account. Instead of paying your landlord, you can pay yourself in the long run through paying down a mortgage on a house.”
The article listed five reasons why owning a home makes financial sense:
  1. Mortgage payments can be fixed while rents go up.
  2. Equity in your home can be a financial resource later.
  3. You can build wealth without paying capital gains.
  4. A mortgage can act as a forced savings account.
  5. Overall, homeowners can enjoy greater wealth growth than renters.

Bottom Line

Before you sign another lease, let’s get together and discuss all your options.