Showing posts with label net worth. Show all posts

Friday, January 26, 2018

Owning a home vs renting can yield 44 times the personal net worth over time


The Cost of NOT Owning Your Home

The Cost of NOT Owning Your Home | MyKCM
Owning a home has great financial benefits, yet many continue to rent! Today, let’s look at the financial reasons why owning a home of your own has been a part of the American Dream for as long as America has existed.
Zillow recently reported that:
“In reality, buying or renting a home is an intensely personal decision, with emotional and even financial considerations that go beyond whether to invest in this one (admittedly large) asset. Looking strictly at housing market numbers, there is a concrete point at which buying a home makes more financial sense than renting it.”

What proof exists that owning is financially better than renting?

1. We recently highlighted the top 5 financial benefits of homeownership:
  • Homeownership is a form of forced savings.
  • Homeownership provides tax savings.
  • Homeownership allows you to lock in your monthly housing cost.
  • Buying a home is cheaper than renting.
  • No other investment lets you live inside of it.
2. Studies have shown that a homeowner’s net worth is 44x greater than that of a renter.
3. Just a few months ago, we explained that a family that purchased an average-priced home at the beginning of 2017 could build more than $48,000 in family wealth over the next five years.
4. Some argue that renting eliminates the cost of taxes and home repairs, but every potential renter must realize that all the expenses the landlord incurs are already baked into the rent payment– along with a profit margin!!

Bottom Line

Owning a home has always been, and will always be, better from a financial standpoint than renting.

Monday, December 18, 2017

No doubt about it, home ownership has financial benefits over renting...

5 Reasons Homeownership Makes ‘Cents’

5 Reasons Homeownership Makes ‘Cents’ | MyKCM
The American Dream of homeownership is alive and well. Recent reports show that the US homeownership rate has rebounded from recent lows and is headed in the right direction. The personal reasons to own differ for each buyer, but there are many basic similarities.
Today we want to talk about the top 5 financial reasons you should own your own home.
  1. Homeownership is a form of forced savings – Paying your mortgage each month allows you to build equity in your home that you can tap into later in life for renovations, to pay off high-interest credit card debt, or even send a child to college. As a renter, you guarantee that your landlord is the person with that equity.
  2. Homeownership provides tax savings – One way to save on taxes is to own your own home. You may be able to deduct your mortgage interest, property taxes, and profits from selling your home, but make sure to always check with your accountant first to find out which tax advantages apply to you in your area.
  3. Homeownership allows you to lock in your monthly housing cost – When you purchase your home with a fixed-rate mortgage, you lock in your monthly housing cost for the next 5, 15, or 30 years. Interest rates have remained around 4% all year, marking some of the lowest rates in history. The value of your home will continue to rise with inflation, but your monthly costs will not.
  4. Buying a home is cheaper than renting – According to the latest report from Trulia, it is now 37.4% less expensive to buy a home of your own than to rent in the US. That number varies throughout the country but ranges from 6% cheaper in San Jose, CA to 57% cheaper in Detroit, MI.
  5. No other investment lets you live inside of it – You can choose to invest your money in gold or the stock market, but you will still need somewhere to live. In a home that you own, you can wake up every morning knowing that your investment is gaining value while providing you a safe place to live.

Bottom Line

Before you sign another lease, let’s get together to help you better understand all your options.

Monday, November 27, 2017

Studies consistently show that homeowners have a greater net worth than renters.

Net Worth of Homeowners 44X Greater than Renters

Net Worth of Homeowners 44X Greater than Renters | MyKCM
Every three years, the Federal Reserve conducts their Survey of Consumer Finances in which they collect data across all economic and social groups. The latest survey data, covering 2013-2016 was released two weeks ago.
The study revealed that the 2016 median net worth of homeowners was $231,400 - a 15% increasesince 2013. At the same time, the median net worth of renters decreased by 5% ($5,200 today compared to $5,500 in 2013).
These numbers reveal that the net worth of a homeowner is over 44 times greater than that of a renter.

Owning a home is a great way to build family wealth

As we’ve said before, simply put, homeownership is a form of ‘forced savings.’ Every time you pay your mortgage, you are contributing to your net worth by increasing the equity in your home.
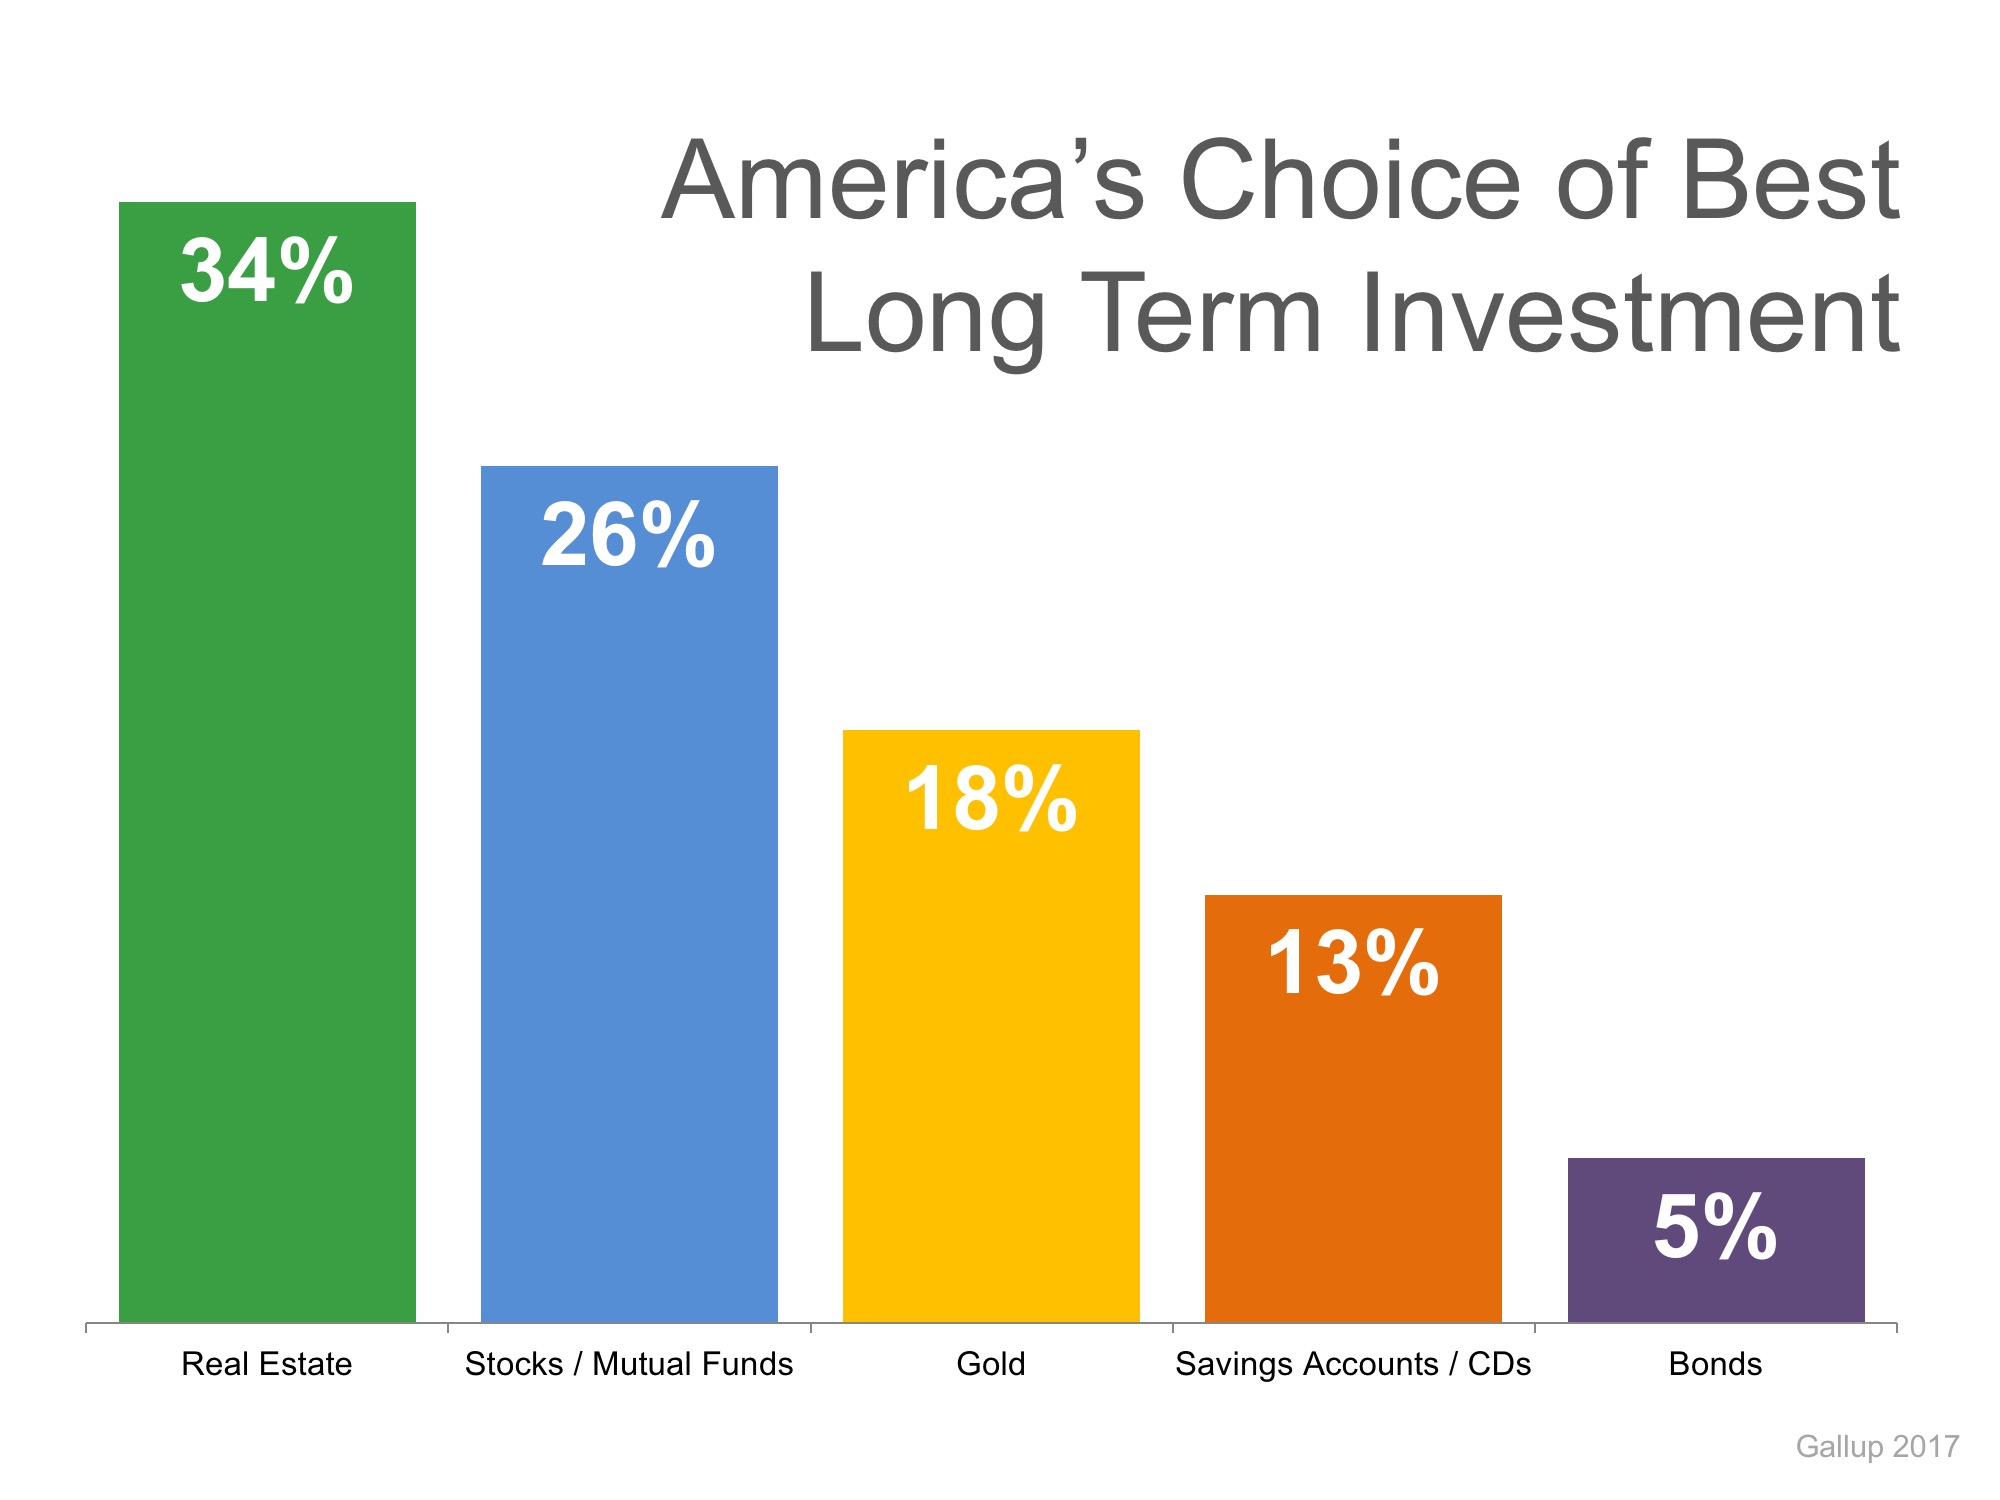
That is why, for the fourth year in a row, Gallup reported that Americans picked real estate as the best long-term investment. This year’s results showed that 34% of Americans chose real estate, followed by stocks at 26% and then gold, savings accounts/CDs, or bonds.

Greater equity in your home gives you options

If you want to find out how you can use the increased equity in your home to move to a home that better fits your current lifestyle, let’s get together to discuss the process.

Monday, October 9, 2017

A pet. That is one of the top reasons Millennials choose to purchase their own home. What drove you to do it?

Top 5 Reasons Why Millennials Choose to Buy [INFOGRAPHIC]

Top 5 Reasons Why Millennials Choose to Buy [INFOGRAPHIC] | MyKCM

Some Highlights:

  • “The majority of millennials said they consider owning a home more sensible than renting for both financial and lifestyle reasons — including control of living space, flexibility in future decisions, privacy and security, and living in a nice home.”
  • The top reason millennials choose to buy is to have control over their living space, at 93%.
  • Many millennials who rent a home or apartment prior to buying their own homes dream of the day that they will be able to paint the walls whatever color they'd like, or renovate an outdated part of their living space.

Monday, October 2, 2017

Home values have increased, which means your equity has as well...


Homeowners: Do You Know Your Home’s Value?


Homeowners: Do You Know Your Home’s Value? | MyKCM
The latest edition of CoreLogic’s Home Price Index shows that nationally, home prices have appreciated 6.7% over the last year and 0.9% month-over-month. The release of the report included this headline,

“National Home Prices Now 50% Above March 2011 Bottom”

The real estate market has come a long way since 2011, which is great news for homeowners!
Nearly 79% of homeowners with a mortgage in the US now have significant equity in their homes (defined as over 20%), according to the latest Equity Report. The challenge is that not every homeowner knows how much their home’s value has appreciated.
Homeowners in Denver, CO lead the way with 8.7% appreciation over the last year, while owners in Washington and Utah have experienced a 3% increase in values since the start of this year!
Nationally, CoreLogic forecasts that home values will increase another 5.0% by this time next year.
Bill Banfield, VP of Capital Markets at Quicken Loans, recently explained the importance of knowing the conditions in your area,
“With home values constantly changing, and the rates of change varying across the country, this is one more way to show how important it is for homeowners to stay aware of their local housing market.”

Bottom Line

Do you know what your house is worth? Have you stayed put because you are nervous you won’t have enough equity to buy your dream home? Let’s get together to perform an equity analysis and give you the freedom to achieve your dreams.

Monday, August 7, 2017

There are some exceptions, however it generally is better to buy than rent. Renting now? Start saving up for your downpayment.

Be Careful Not to Get Caught in The Rental Trap!

Be Careful Not to Get Caught in The Rental Trap! | MyKCM
There are many benefits to homeownership. One of the top benefits is being able to protect yourself from rising rents by locking in your housing cost for the life of your mortgage.

Don’t Become Trapped 

A recent article by ConsumerAffairs addressed the continuous rise in rents, stating:
“The cost of putting a roof over your head continues to go up. Not only are home prices still rising, but the cost of rent rose 0.5% in June.”
Additionally, in the Joint Center for Housing Studies at Harvard University’s 2017 State of the Nation’s Housing Report, it was revealed that,
“Despite a slight improvement from 2014, fully one-third of US households paid more than 30 percent of their incomes for housing in 2015. Renters continue to be more likely to face cost burdens…the number of cost-burdened renters (21 million) considerably outstrips the number of cost-burdened owners (18 million) even though nearly two-thirds of US households own their homes.”
These households struggle to save for a rainy day and pay other bills, including groceries and healthcare.

It’s Cheaper to Buy Than Rent 

As we have previously mentioned, the results of the latest Rent vs. Buy Report from Trulia shows that homeownership remains cheaper than renting with a traditional 30-year fixed rate mortgage in the 100 largest metro areas in the United States.
The updated numbers show that the range is an average of 3.5% less expensive in San Jose (CA), all the way up to 50.1% less expensive in Baton Rouge (LA), and 33.1% nationwide!

Know Your Options

Perhaps you have already saved enough to buy your first home. A nationwide survey of about 24,000 renters found that 80% of millennial renters plan to eventually buy a house, but 72% cite affordability as their primary obstacle. Aside from affordability, one in three millennial renters have concerns about their credit scores, and another 53% said that a down payment is an obstacle.
Many first-time homebuyers who believe that they need a large down payment may be holding themselves back from their dream homes. As we have reported before, in many areas of the country, a first-time home buyer can save for a 3% down payment in less than two years. You may have already saved enough!

Bottom Line

Don’t get caught in the trap that so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Let’s get together to determine if you can qualify for a mortgage now!

Monday, July 31, 2017

Rising property values means that homeowners are building equity, which translates into greater financial stability.

Rising Home Prices Mean Great News for Homeowners

Rising Home Prices Mean Great News for Homeowners | MyKCM
Recently there has been a lot of talk about home prices and if they are accelerating too quickly. As we mentioned before, in some areas of the country, seller supply (homes for sale) cannot keep up with the number of buyers who are out looking for homes, which has caused prices to rise.
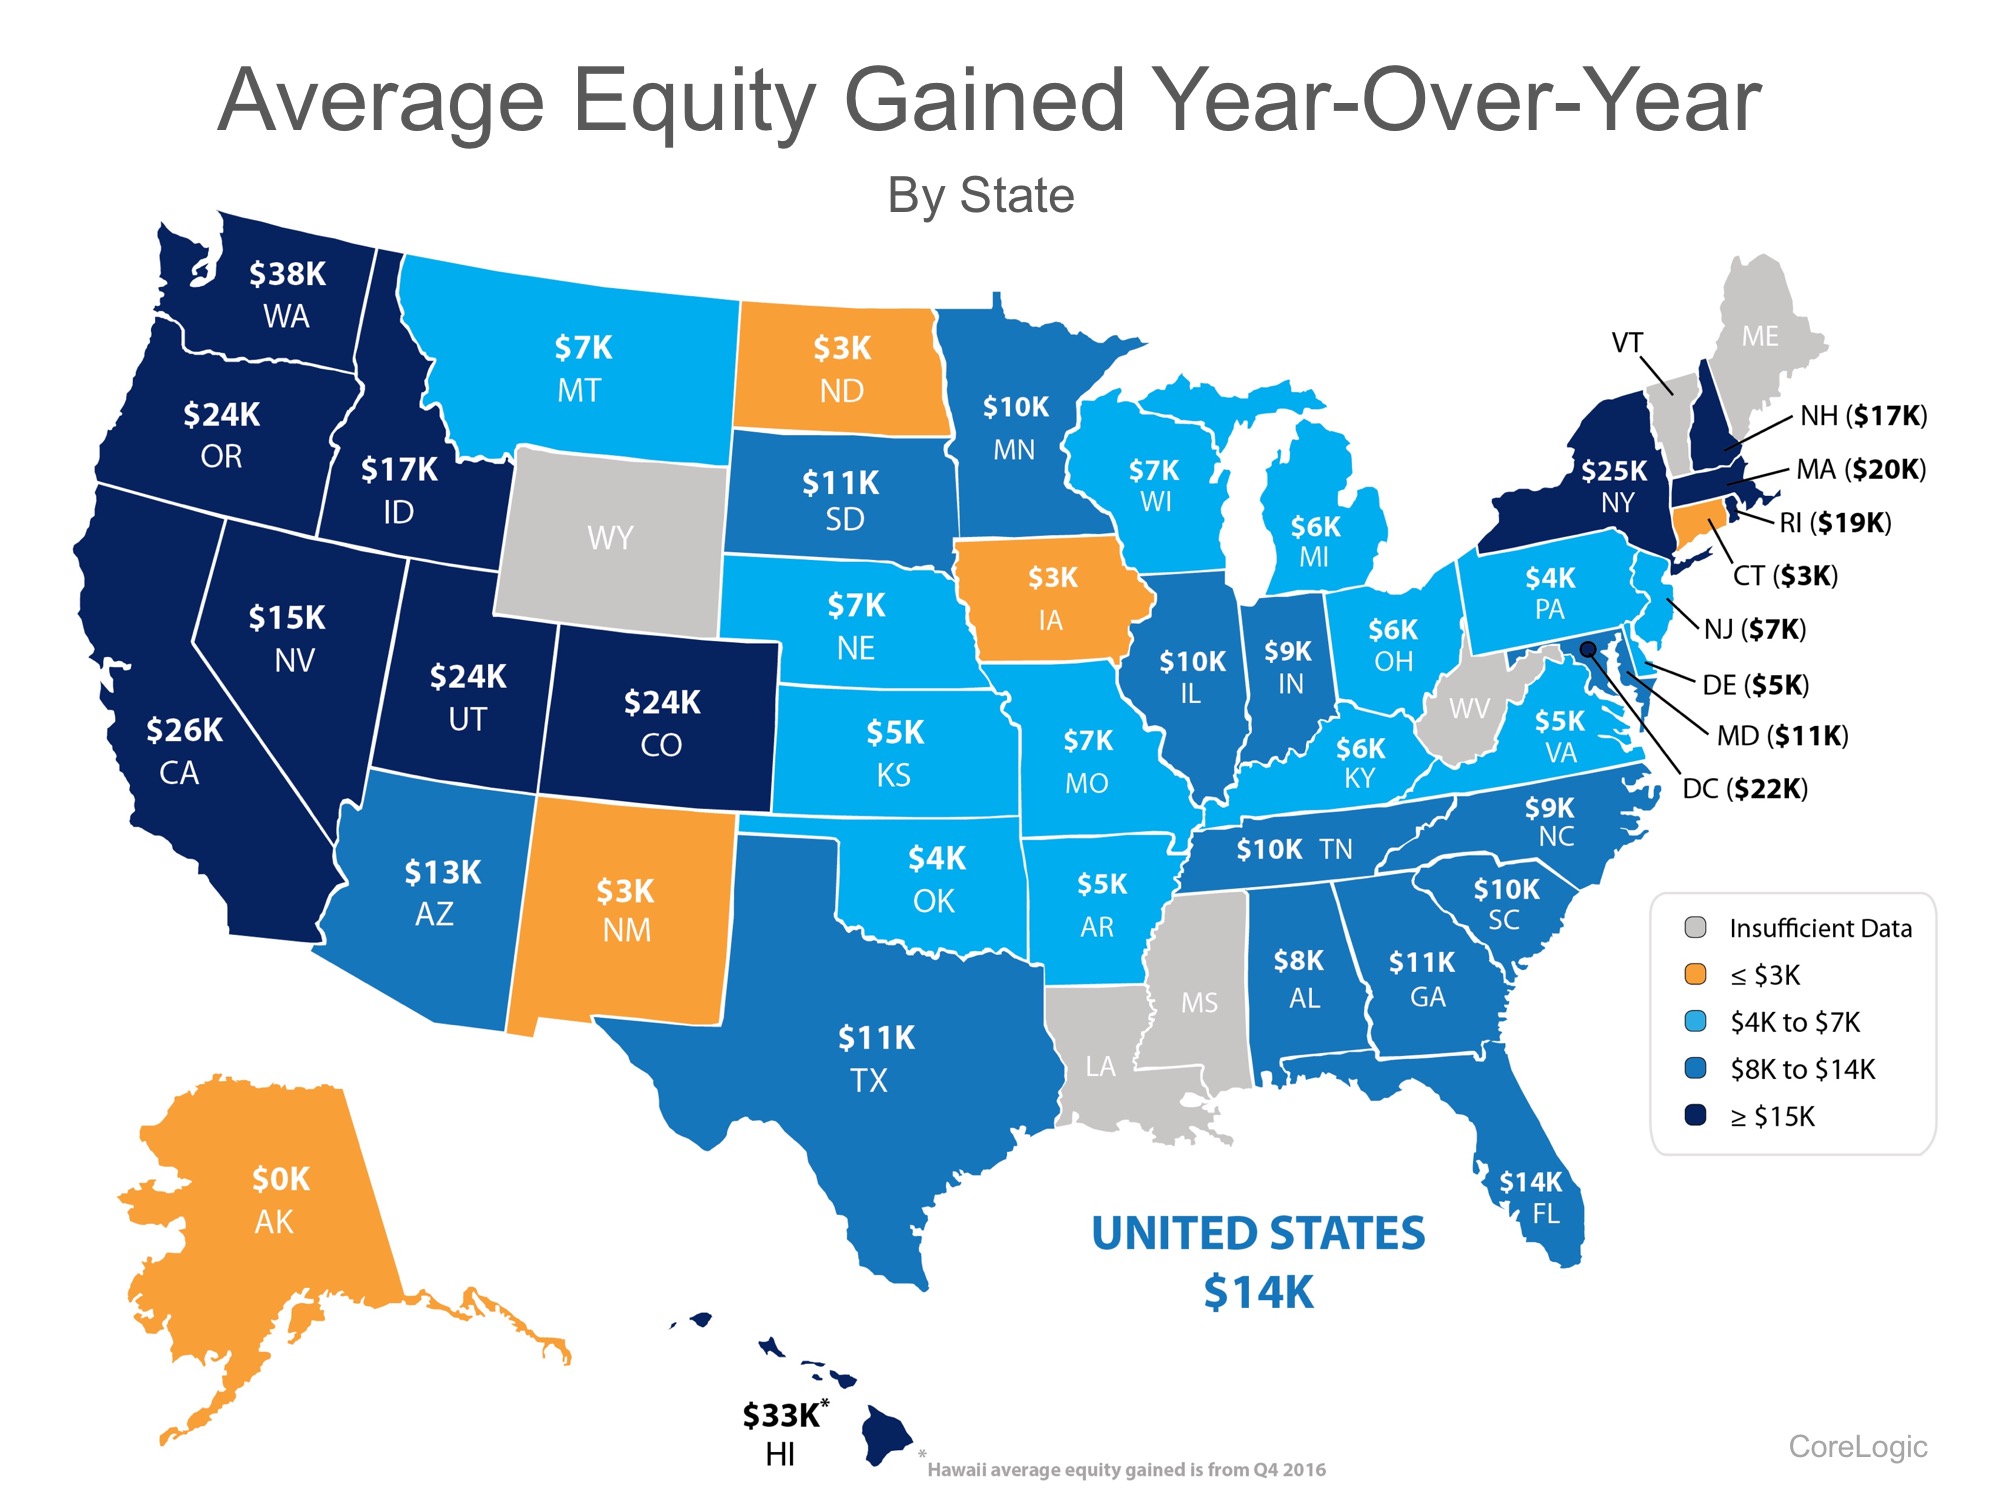
The great news about rising prices, however, is that according to CoreLogic’s Homeowner Equity Report, the average American household gained over $14,000 in equity over the course of the last year, largely due to home value increases.
The map below was created using the same report from CoreLogic and shows the average equity gain per mortgaged home during the 1st quarter of 2017 (the latest data available).
Rising Home Prices Mean Great News for Homeowners | MyKCM
For those who are worried that we are doomed to repeat 2006 all over again, it is important to note that homeowners are investing their new-found equity in their homes and themselves, not in depreciating assets.
The added equity is helping families put their children through college, invest in starting small businesses, pay off their mortgages sooner and even move up to the home that will better suit their needs now.

Bottom Line

If you are a homeowner looking to take advantage of your home equity by moving up to your dream home, let’s get together to discuss your options!

Tuesday, July 11, 2017

Do you have home equity planned into your retirement?

The Importance of Home Equity in Retirement Planning

The Importance of Home Equity in Retirement Planning | MyKCM
We often discuss the difference in family wealth between homeowner households and renter households. Much of that difference is the result of the equity buildup that homeowners experience over the time that they own their home. In a report recently released by the nonpartisan Employee Benefit Research Institute (EBRI), they reveal how valuable equity can be in retirement planning.
Craig Copeland, Senior Research Associate at EBRI, recently authored a report, Importance of Individual Account Retirement Plans and Home Equity in Family Total Wealth, in which he reveals:
“Individual account retirement plan assets, plus home equity, represent almost all of what families have to use for retirement expenses outside of Social Security and traditional pensions. Those families without individual account assets typically have very low overall assets, so they have almost nothing to draw from for retirement expenses.”
The report echoed the findings of a working paper, Home Equity Patterns among Older American Households, authored by Barbara Butrica and Stipica Mudrazija of Urban Institute. Fannie Mae highlighted these findings for their blog The Home Story this past winter, quoting Butrica and Mudrazija:
 “For most adults near traditional retirement age, a home is their most valuable asset — dwarfing retirement accounts, other financial assets, and other nonfinancial assets. Although relatively few retirees tap into their home equity, having it provides financial security… In fact, many retirement security experts argue that the conventional three-legged stool of retirement resources — Social Security, pensions, and savings — is incomplete because it ignores the home.”
USAToday interviewed two area experts to comment on the EBRI report. Randy Bruns, a private wealth adviser with HighPoint Planning Partners, agreed with the findings:
“Social Security and home equity are major pieces of the retirement puzzle.”
Wade Pfau, Professor of Retirement Income at The American College of Financial Services and author of Reverse Mortgages: How to use Reverse Mortgages to Secure Your Retirement, said having the equity without a plan to use it won’t help:
“Home equity is a very important asset for American retirees, and so it is important to think about how to make best use of home equity in retirement planning.”

Bottom Line

Whether you use the equity in your home through a reverse mortgage or by selling and downsizing to a less expensive home, it should be a crucial piece of your retirement planning.

Friday, June 30, 2017

The housing market continues to see an increase in the number of homeowners that now have positive equity in their homes...

Do You Know How Much Equity You Have in Your Home?

Do You Know How Much Equity You Have in Your Home? | MyKCM
CoreLogic’s latest Equity Report revealed that 91,000 properties regained equity in the first quarter of 2017. This is great news for the country, as 48.2 million of all mortgaged properties are now in a positive equity situation.
Price Appreciation = Good News for Homeowners
Frank Nothaft, CoreLogic’s Chief Economist, explains:
One million borrowers achieved positive equity over the last year, which means risk continues to steadily decline as a result of increasing home prices.”
Frank Martell, President and CEO of CoreLogic, believes this is a great sign for the market in 2017 as well, as he had this to say:
Homeowner equity increased by $766 billion over the last year, the largest increase since Q2 2014. The rising cushion of home equity is one of the main drivers of improved mortgage performance. Since home equity is the largest source of homeowner wealth, the increase in home equity also supports consumer balance sheets, spending and the broader economy.”

This is great news for homeowners! But, do they realize that their equity position has changed?

According to the Fannie Mae’s Home Purchase Sentiment Index (HPSI), more homeowners are beginning to realize that they may have more equity than they first thought.
This is only the second time in the survey’s history that the net share of those saying it’s a good time to sell surpassed the net share of those saying it’s a good time to buy.

78.8% of homeowners have significant equity (more than 20%) in their homes today!

This means that many Americans with a mortgage have an opportunity to take advantage of today’s seller’s market. With a sizeable equity position, many homeowners could easily move into a housing situation that better meets their current needs (moving to a larger home or downsizing).
Doug Duncan, Senior Vice President and Chief Economist at Fannie Mae spoke out on this issue:
“High home prices have led many consumers to give us the first clear indication we’ve seen in the National Housing Survey’s seven-year history that they think it’s now a seller’s market. However, we continue to see a lack of housing supply as many potential sellers are unwilling or unable to put their homes on the market…” 

Bottom Line

If you are one of the many Americans who is unsure of how much equity you have built in your home, don’t let that be the reason you fail to move on to your dream home in 2017! Let’s get together to evaluate your situation!

Friday, June 2, 2017

Want to build greater personal net worth? Studies show that owning real estate will help you achieve that goal faster than people who don't own real estate....

Do You Know the Cost of NOT Owning Your Home?

Do You Know the Cost of NOT Owning Your Home? | MyKCM
Owning a home has great financial benefits, yet many continue renting! Today, let’s look at the financial reasons why owning a home of your own has been a part of the American Dream for as long as America has existed.
Zillow recently reported that:
“With Rents continuing to climb and interest rates staying low, many renters find themselves gazing over the homeownership fence and wondering if the grass really is greener. Leaving aside, for the moment, the difficulties of saving for a down payment, let’s focus on the monthly expenses of owning a home: it turns out that renters currently paying the median rent in many markets could afford to buy a higher-quality property than the typical (read: median-valued) home without increasing their monthly expenses.”

What proof exists that owning is financially better than renting?

1. The latest Rent Vs. Buy Report from Trulia pointed out the top 5 financial benefits of homeownership:
  • Mortgage payments can be fixed while rents go up.
  • Equity in your home can be a financial resource later.
  • You can build wealth without paying capital gain.
  • A mortgage can act as a forced savings account
  • Overall, homeowners can enjoy greater wealth growth than renters.
2. Studies have shown that a homeowner’s net worth is 45x greater than that of a renter.
3. Just a few months ago, we explained that a family buying an average priced home at the beginning of 2017 could build more than $42,000 in family wealth over the next five years.
4. Some argue that renting eliminates the cost of taxes and home repairs, but every potential renter must realize that all the expenses the landlord incurs are already baked into the rent paymentalong with a profit margin!!

Bottom Line

Owning a home has always been, and will always be, better from a financial standpoint than renting.
Wednesday, May 31, 2017

According to Gallup - real estate remains the best long-term investment...

Gallup: Real Estate is Best Long-Term Investment 4 Years Running

Gallup: Real Estate is Best Long-Term Investment 4 Years Running | MyKCM
Every year, Gallup surveys Americans to determine their choice for the best long-term investment. Respondents are given a choice between real estate, stocks/mutual funds, gold, savings accounts/CDs, or bonds.
For the fourth year in a row, Real Estate has come out on top as the best long-term investment! This year’s results showed that 34% of Americans chose real estate, followed by stocks at 26%. The full results are shown in the chart below.
Gallup: Real Estate is Best Long-Term Investment 4 Years Running | MyKCM
The study makes it a point to draw attention to the contrast of the sentiment over the last four years compared to that of 2011-2012, when gold took the top slot with 34% of the votes. Real estate and stocks took second and third place, respectively, while still in recovery from the Great Recession.

Bottom Line

As the real estate market has recovered, so has the belief of the American people in the stability of housing as a long-term investment.

Monday, May 8, 2017

What is PMI? Can you avoid paying it? How can it impact your borrowing power?

Get All the Facts about PMI

Get All the Facts about PMI | MyKCM
When it comes to buying a home, whether it is your first time or your fifth, it is always important to know all the facts. With the large number of mortgage programs available that allow buyers to purchase a home with a down payment below 20%, you can never have too much information about Private Mortgage Insurance (PMI).

What is PMI?

Freddie Mac defines PMI as:
“An insurance policy that protects the lender if you are unable to pay your mortgage. It's a monthly fee, rolled into your mortgage payment, that is required for all conforming, conventional loans that have down payments less than 20%.
Once you've built equity of 20% in your home, you can cancel your PMI and remove that expense from your mortgage payment.”
As the borrower, you pay the monthly premiums for the insurance policy, and the lender is the beneficiary. Freddie Mac goes on to explain that:
“The cost of PMI varies based on your loan-to-value ratio – the amount you owe on your mortgage compared to its value – and credit score, but you can expect to pay between $30 and $70 per month for every $100,000 borrowed.” 
According to the National Association of Realtors, the average down payment for all buyers last year was 10%. For first-time buyers, that number dropped to 6%, while repeat buyers put down 14% (no doubt aided by the sale of their home). This just goes to show that for a large number of buyers last year, PMI did not stop them from buying their dream homes.
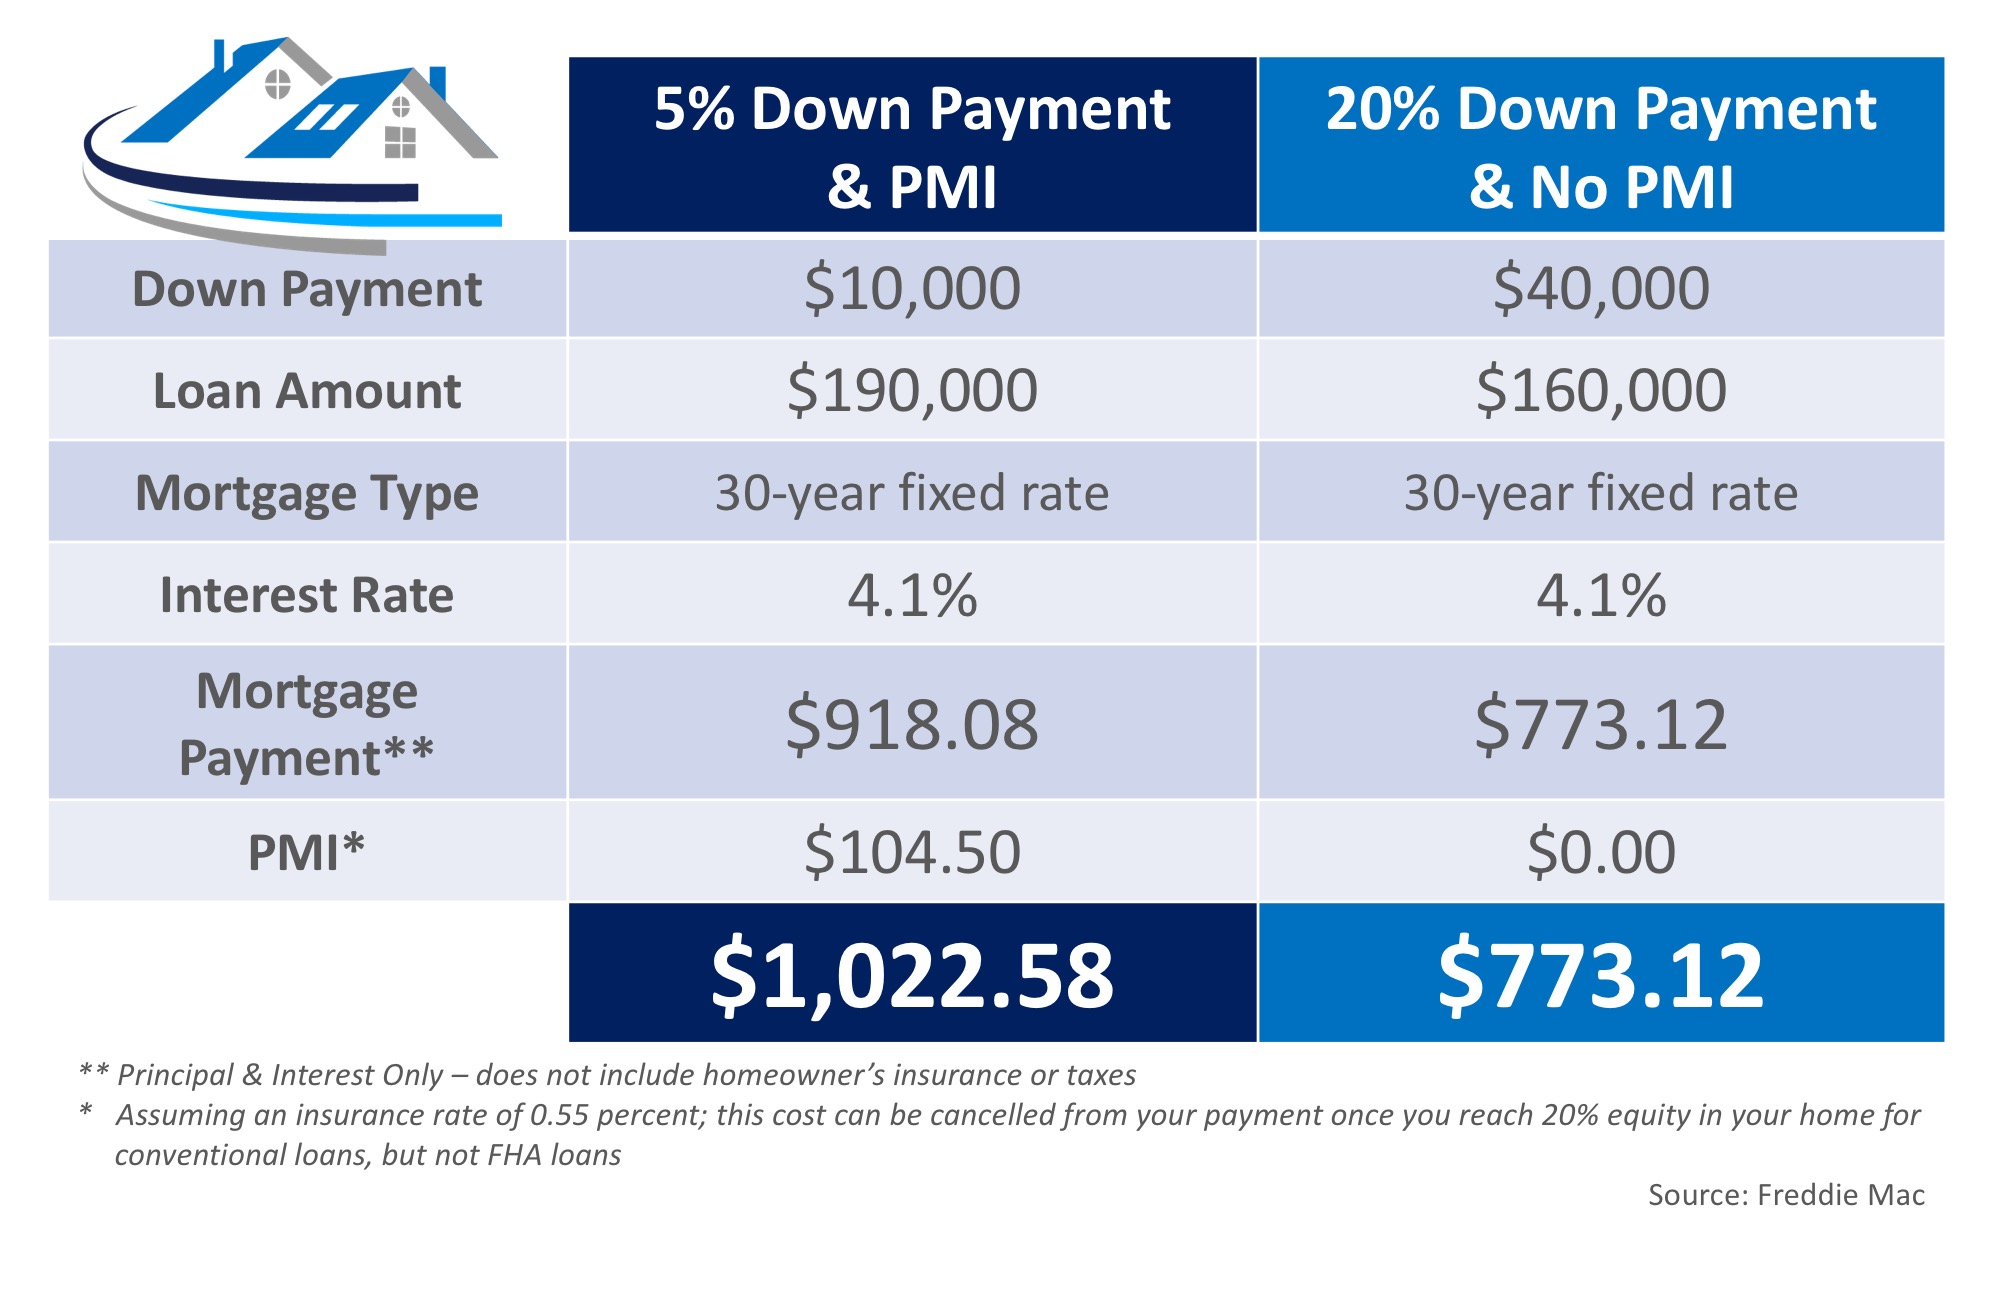
Here’s an example of the cost of a mortgage on a $200,000 home with a 5% down payment & PMI, compared to a 20% down payment without PMI:
Get All the Facts about PMI | MyKCM

The larger the down payment you can make, the lower your monthly housing cost will be, but Freddie Mac urges you to remember:
“It's no doubt an added cost, but it's enabling you to buy now and begin building equity versus waiting 5 to 10 years to build enough savings for a 20% down payment.”

Bottom Line

If you have questions about whether you should buy now or wait until you’ve saved a larger down payment, let’s get together to discuss our market’s conditions and to help you make the best decision for you and your family.

Wednesday, May 3, 2017

Real estate experts are still convinced that owning a home is a great investment, as long as you do these two things...

Real Estate Mogul: Here’s Why You Should Buy

Real Estate Mogul: Here’s Why You Should Buy | MyKCM
Real Estate mogul, Sean Conlon, host of The Deed: Chicago on CNBC, was recently asked the question, should you buy? Or should you rent a house?
Conlon responded:
“I am a true believer that you save every penny and you buy your first house… and that is still the fastest path to wealth in this country.”
Conlon went on to suggest that first-time buyers put down 10-20% “if they can make it work,” and to remain in their home at least 4-5 years to see a return on their investment.

Who is Sean Conlon, and why should you listen to his advice?

Within a few years of working in the real estate industry, Conlon had established himself as one of the leading agents in the United States and has founded 3 billion-dollar brokerages dealing in residential, commercial and investment sales. Since immigrating to America from the United Kingdom in 1990, he believes very strongly in the American Dream and the role that homeownership plays in achieving it. Conlon is quoted on his website as saying:
“I treat people the way I would like to be treated if I went in to buy a house and I work harder than anybody I know. I think if you do that in America, you will always succeed.”

Bottom Line

Homeownership is an investment you can leverage against in the future that not only provides shelter and safety but also helps you build your family’s wealth. If you are debating whether or not to purchase a home this year, let’s get together to discuss the opportunities available in today’s market!

Tuesday, April 25, 2017

There is a new housing crisis in town - rising rents that are affecting rental housing affordability.

Careful…Don’t Get Caught in the Rental Trap!

Careful…Don’t Get Caught in the Rental Trap! | MyKCM
There are many benefits to homeownership. One of the top benefits is being able to protect yourself from rising rents by locking in your housing cost for the life of your mortgage.

Don’t Become Trapped 

Jonathan Smoke, Chief Economist at realtor.comreported on what he calls a “Rental Affordability Crisis.” He warns that,
“Low rental vacancies and a lack of new rental construction are pushing up rents, and we expect that they’ll outpace home price appreciation in the year ahead.”
In the Joint Center for Housing Studies at Harvard University's 2016 State of the Nation’s Housing Report, they revealed that The number of cost-burdened households rose to 21.3 million. Even more troubling, the number with severe burdens (paying more than 50% of income for housing) jumped to a record 11.4 million. These households struggle to save for a rainy day and pay other bills, such as food and healthcare.

It’s Cheaper to Buy Than Rent 

In Smoke’s article, he went on to say,
“Housing is central to the health and well-being of our country and our local communities. In addition, this (rental affordability) crisis threatens the future value of owned housing, as the burdensome level of rents will trap more aspiring owners into a vicious financial cycle in which they cannot save and build a solid credit record to eventually buy a home.”
“While more than 85% of markets have burdensome rents today, it’s perplexing that in more than 75% of the counties across the country, it is actually cheaper to buy than rent a home. So why aren’t those unhappy renters choosing to buy?”

Know Your Options

Perhaps you have already saved enough to buy your first home. HousingWire reported that analysts at Nomura believe:
"It’s not that Millennials and other potential homebuyers aren’t qualified in terms of their credit scores or in how much they have saved for their down payment. 
It’s that they think they’re not qualified or they think that they don’t have a big enough down payment.” (emphasis added)
Many first-time homebuyers who believe that they need a large down payment may be holding themselves back from their dream home. As we have reported before, in many areas of the country, a first-time home buyer can save for a 3% down payment in less than two years. You may have already saved enough!

Bottom Line

Don’t get caught in the trap so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Let’s get together to determine if you can qualify for a mortgage now!

Monday, April 24, 2017

Millennials are beginning to buy homes, for very smart reasons...

Why Millennials Choose to Buy [INFOGRAPHIC]

Why Millennials Choose to Buy [INFOGRAPHIC] | MyKCM

Some Highlights:

  • “The majority of millennials said they consider owning a home more sensible than renting for both financial and lifestyle reasons — including control of living space, flexibility in future decisions, privacy and security, and living in a nice home.”
  • At 93%, the top reason Millennials choose to buy is to have control over their living space.
  • Many Millennials who rent a home or apartment prior to buying their own homes dream of the day that they will be able to paint the walls whatever color they'd like, or renovate an outdated part of their living space.

Tuesday, April 11, 2017

Hey Millennials! Do you know that if you continue to rent, you decrease your personal wealth potential considerably?

Millionaire to Millennials: Buy Now!

Millionaire to Millennials: Buy Now! | MyKCM
Self-made millionaire David Bach was quoted in a CNBC article explaining that "the single biggest mistake millennials are making" is not purchasing a home because buying real estate is "an escalator to wealth.”
Bach went on to explain:
"If millennials don't buy a home, their chances of actually having any wealth in this country are little to none. The average homeowner to this day is 38 times wealthier than a renter."
In his bestselling book, “The Automatic Millionaire,” Bach does the math:
"As a renter, you can easily spend half a million dollars or more on rent over the years ($1,500 a month for 30 years comes to $540,000), and in the end wind up just where you started — owning nothing. Or you can buy a house and spend the same amount paying down a mortgage, and in the end wind up owning your own home free and clear!"

Who is David Bach?

Bach is a self-made millionaire who has written nine consecutive New York Times bestsellers. His book, “The Automatic Millionaire,” spent 31 weeks on the New York Times bestseller list. He is one of the only business authors in history to have four books simultaneously on the New York Times, Wall Street Journal, BusinessWeek and USA Today bestseller lists.
He has been a contributor to NBC’s Today Show appearing more than 100 times, has been a regular on ABC, CBS, Fox, CNBC, CNN, Yahoo, The View, and PBS, and has been profiled in many major publications, including The New York Times, BusinessWeek, USA Today, People, Reader’s Digest, Time, Financial Times, The Washington Post, The Wall Street Journal, Working Woman, Glamour, Family Circle, Redbook, Huffington Post, Business Insider, Investors’ Business Daily, and Forbes.

Bottom Line

Whenever a well-respected millionaire gives investment advice, people usually clamor to hear it. This millionaire gave simple advice – if you don’t yet live in your own home, go buy one.

Wednesday, March 8, 2017

Over the next 5 years, nationally, home values are expected to hit an annual average appreciate of 3.22%. That's good news for the housing industry.

Where Are the Home Prices Heading in the Next 5 Years?

Where Are the Home Prices Heading in the Next 5 Years? | MyKCM
Today, many real estate conversations center on housing prices and where they may be headed. That is why we like the Home Price Expectation Survey.
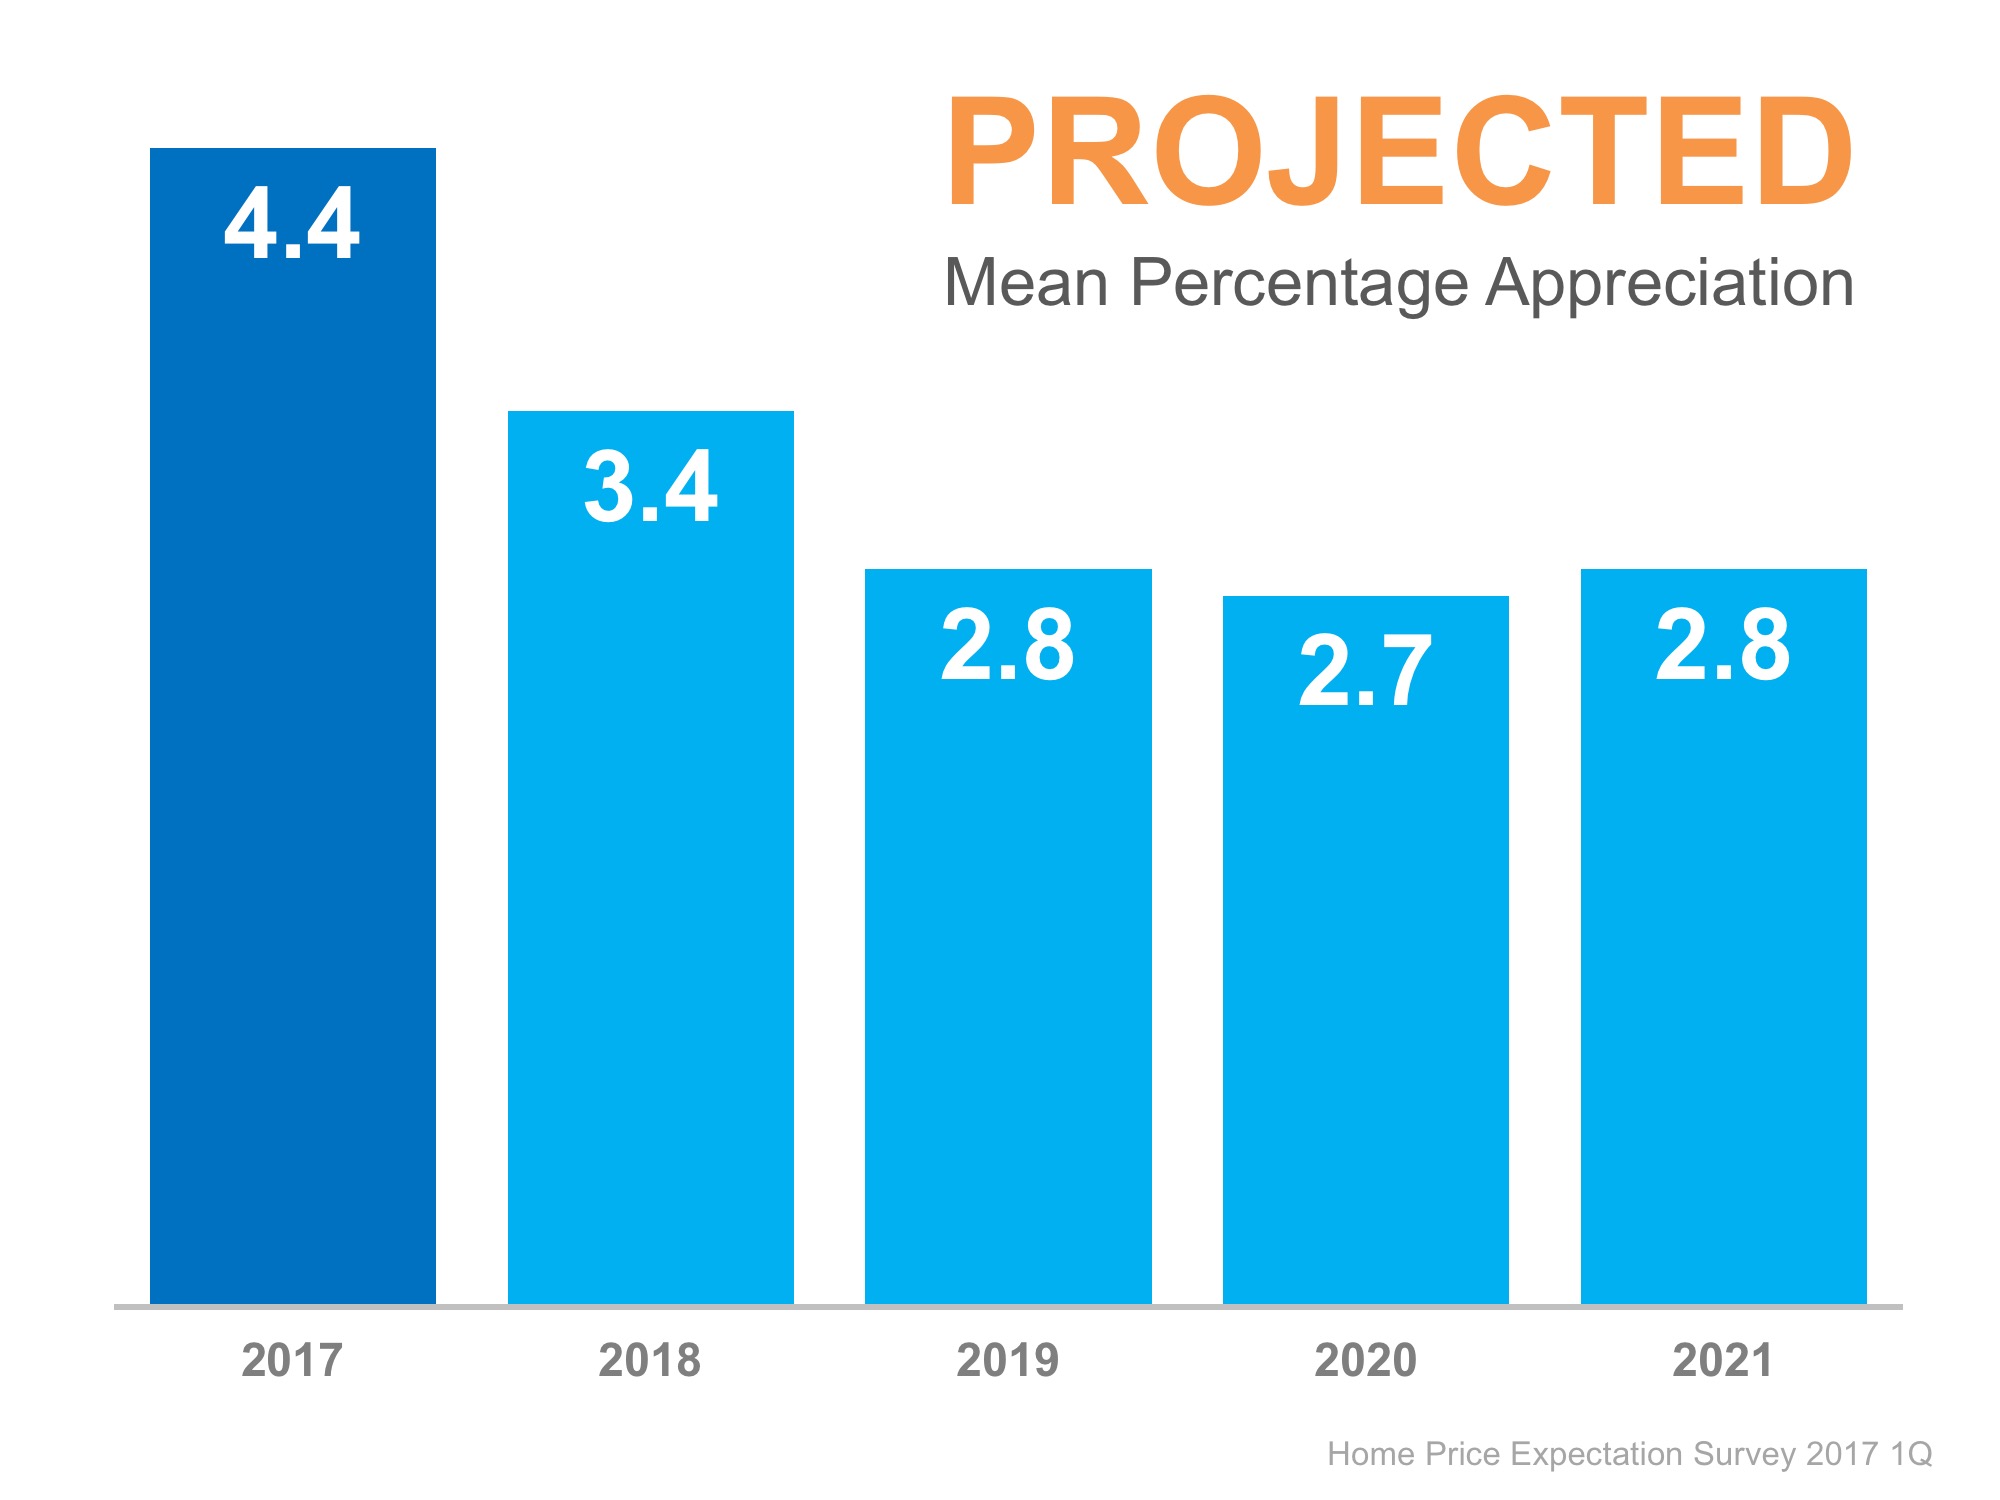
Every quarter, Pulsenomics surveys a nationwide panel of over one hundred economists, real estate experts, and investment & market strategists about where they believe prices are headed over the next five years. They then average the projections of all 100+ experts into a single number.

The results of their latest survey:

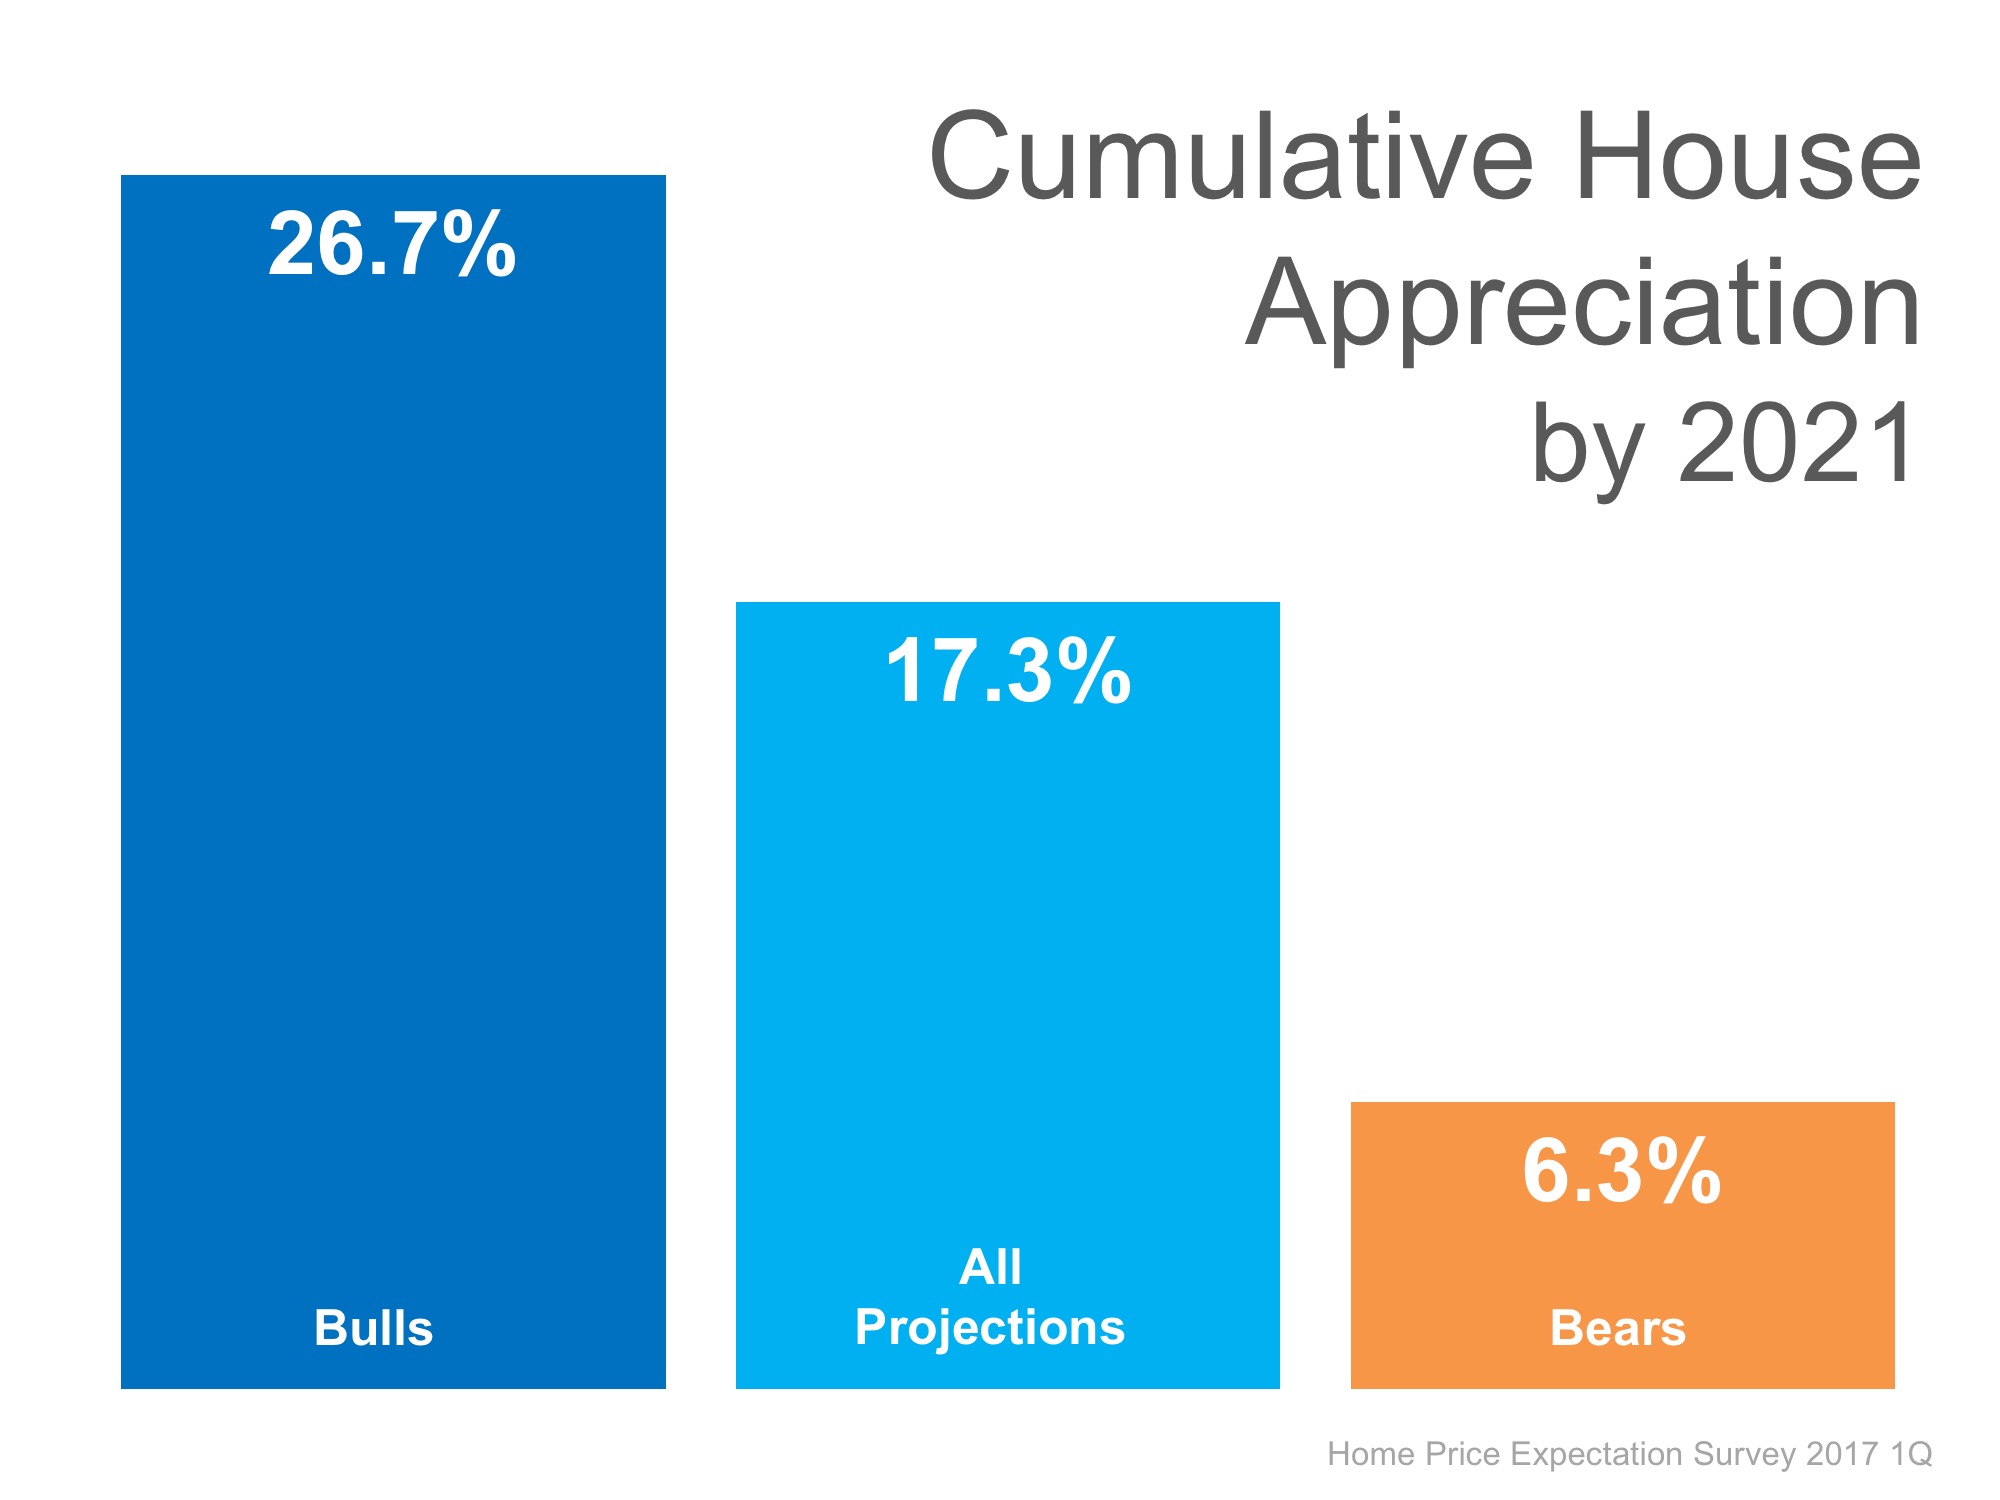
Home values will appreciate by 4.4% over the course of 2017, 3.4% in 2018, 2.8% in 2019, 2.7% in 2020, and 2.8% in 2021. That means the average annual appreciation will be 3.22% over the next 5 years.
Where Are the Home Prices Heading in the Next 5 Years? | MyKCM
The prediction for cumulative appreciation fell from 21.4% to 17.3% by 2021. The experts making up the most bearish quartile of the survey are projecting a cumulative appreciation of 6.3%.
Where Are the Home Prices Heading in the Next 5 Years? | MyKCM

Bottom Line

Individual opinions make headlines. We believe this survey is a fairer depiction of future values.

Tuesday, March 7, 2017

Did you know that homeowners have been shown to have better overall health and higher self-esteem, because they own a house?

The Impact of Homeownership on Family Health

The Impact of Homeownership on Family Health | MyKCM
The National Association of Realtors recently released a study titled 'Social Benefits of Homeownership and Stable Housing.’ The study confirmed a long-standing belief of most Americans:
“Owning a home embodies the promise of individual autonomy and is the aspiration of most American households. Homeownership allows households to accumulate wealth and social status, and is the basis for a number of positive social, economic, family and civic outcomes.”
Today, we want to cover the section of the report that quoted several studies concentrating on the impact homeownership has on the health of family members. Here are some of the major findings on this issue revealed in the report:
  • There is a strong positive relationship between living in poor housing and a range of health problems, including respiratory conditions such as asthma, exposure to toxic substances, injuries and mental health. Homes of owners are generally in better condition than those of renters.
  • Findings reveal that increases in housing wealth were associated with better health outcomes for homeowners.
  • Low-income people who recently became homeowners reported higher life satisfaction, higher self-esteem, and higher perceived control over their lives.
  • Homeowners report higher self-esteem and happiness than renters. For example, homeowners are more likely to believe that they can do things as well as anyone else, and they report higher self-ratings on their physical health even after controlling for age and socioeconomic factors.
  • Renters who become homeowners not only experience a significant increase in housing satisfaction but also obtain a higher satisfaction even in the same home in which they resided as renters.
  • Social mobility variables, such as the family financial situation and housing tenure during childhood and adulthood, impacted one’s self-rated health.
  • Homeowners have a significant health advantage over renters, on average. Homeowners are 2.5 percent more likely to have good health. When adjusting for an array of demographic, socioeconomic, and housing–related characteristics, the homeowner advantage is even larger at 3.1 percent.

Bottom Line

People often talk about the financial benefits of homeownership. As we can see, there are also social benefits of owning your own home.

Friday, February 24, 2017

Homeowners tend to be more involved on a social and civic level, than renters. Stability has its' benefits!

The Impact of Homeownership on Civic Involvement

The Impact of Homeownership on Civic Involvement | MyKCM
The National Association of Realtors recently released a study titled 'Social Benefits of Homeownership and Stable Housing.’ The study confirmed a long-standing belief of most Americans:
“Owning a home embodies the promise of individual autonomy and is the aspiration of most American households. Homeownership allows households to accumulate wealth and social status, and is the basis for a number of positive social, economic, family and civic outcomes.”
Today, we want to cover the section of the report that quoted several studies concentrating on the impact homeownership has on the civic participation of family members. Here are some of the major findings on this issue revealed in the report:
  • Homeowners have a much greater financial stake in their neighborhoods than renters. With the median national home price in 2015 at $223,900, even a 5% decline in home values will translate into a loss of more than $11,195 for a typical homeowner.
  • Because owners tend to remain in their homes longer, they add a degree of stability to their neighborhood.
  • Homeowners also reap the financial gains of any appreciation in the value of their home, so they also tend to spend more time and money maintaining their residence, which also contributes to the overall quality of the surrounding community.
  • Homeowners were found to be more politically active than renters with 77% of homeowners saying they had at some point voted in local elections compared with 52% of renters.
  • There seems to be a greater awareness of the political process among homeowners. About 38% of homeowners knew the name of their local school board representative, compared with only 20% of renters.
  • There is a higher incidence of membership in voluntary organizations and church attendance among homeowners.
  • Homeownership does create social capital and provide residents with a platform from which to connect and interact with neighbors.
  • Owning a home means owning part of a neighborhood, and a homeowner’s feelings of commitment to the home can arouse feelings of commitment to the neighborhood, which, in turn, can produce interactions with neighbors.

Bottom Line

People often talk about the financial benefits of homeownership. As we can see, there are also social benefits of owning your own home.

Friday, February 10, 2017

Do you know the top 2 reasons Americans buy homes instead of renting them?

Homeownership Offers Stability & Wealth Creation

Homeownership Offers Stability & Wealth Creation | MyKCM
The most recent Housing Pulse Survey released by the National Association of Realtors revealed that the two major reasons Americans prefer owning their own home instead of renting are:
  1. They want the opportunity to build equity.
  2. They want a stable and safe environment.

Building Equity

In a recent article by The Mortgage Reports, they report that “buying and owning a home is the essence of ‘The American Dream.’ Each month, your housing payments go toward owning your home instead of renting it; building your personal wealth and assets instead of someone else’s.
History has shown that homeownership is a clear path to wealth-building, with homeowners boasting a net worth [that is] multiples higher than the net worth of renters.”  

Family Stability 

Does owning your home really create a more stable environment for your family?
survey of property managers conducted by rent.com disclosed two reasons tenants should feel less stable with their housing situation:
  • 68% of property managers predict that rental rates will continue to rise in the next year by an average of 8%.
  • 53% of property managers said that they were more likely to bring in a new tenant at a higher rate than to negotiate and renew a lease with a current tenant they already know.
We can see from these survey results that renting will provide anything but a stable environment in the near future.

Bottom Line

Homeowners enjoy a more stable environment, and at the same time are given the opportunity to build their family’s net worth.