Showing posts with label foreclosure. Show all posts

Wednesday, April 5, 2017

Analysts reveal that foreclosures peaked in 2010, and have been on a consistent decline since then.

The Foreclosure Crisis: 10 Years Later
The Foreclosure Crisis: 10 Years Later | MyKCM
CoreLogic recently released a report entitled, United States Residential Foreclosure Crisis: 10 Years Later, in which they examined the years leading up to the crisis all the way through to present day.
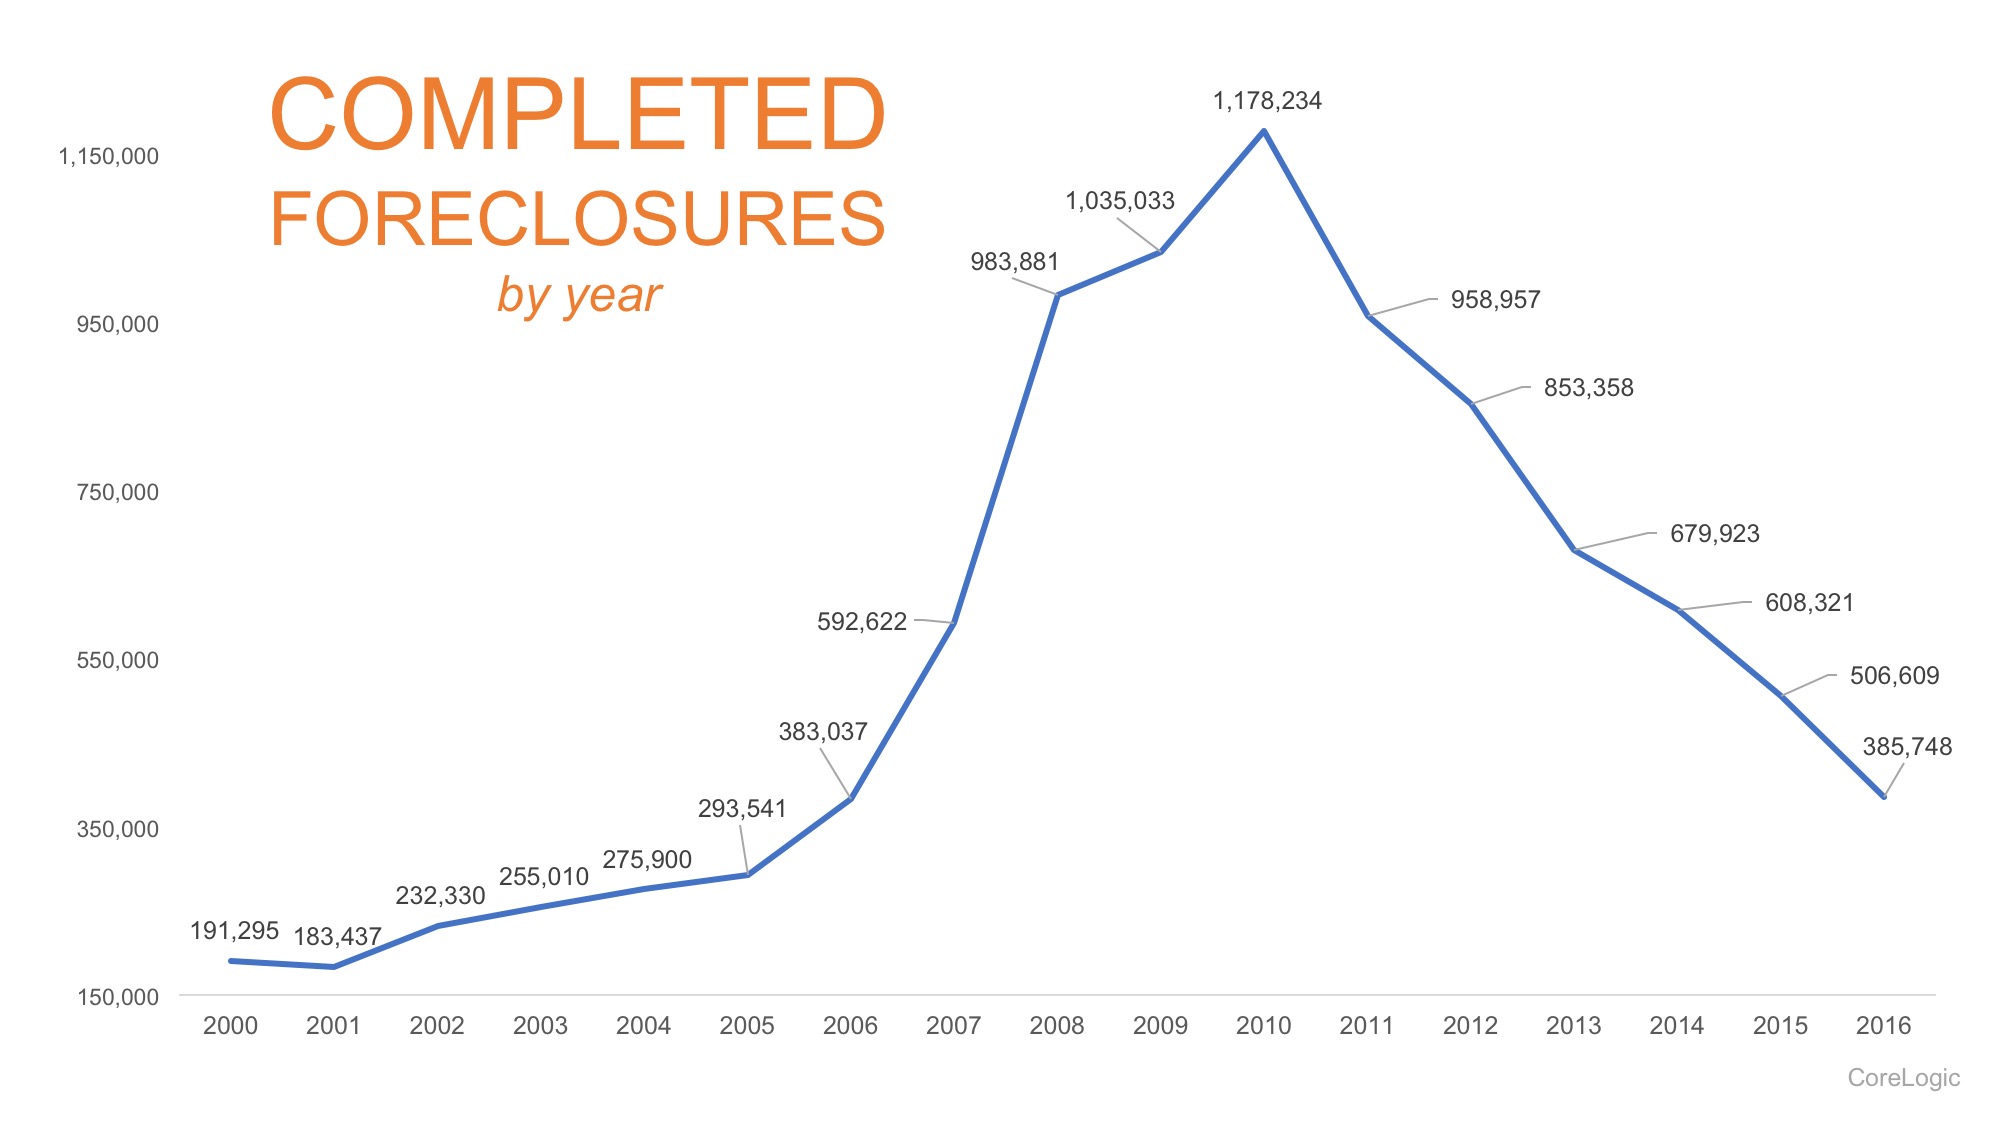
With a peak in 2010 when nearly 1.2 million homes were foreclosed on, over 7.7 million families lost their homes throughout the entire foreclosure crisis.
Dr. Frank Nothaft, Chief Economist for CoreLogic, had this to say,
“The country experienced a wild ride in the mortgage market between 2008 and 2012, with the foreclosure peak occurring in 2010. As we look back over 10 years of the foreclosure crisis, we cannot ignore the connection between jobs and homeownership. A healthy economy is driven by jobs coupled with consumer confidence that usually leads to homeownership.”
Since the peak, foreclosures have been steadily on the decline by nearly 100,000 per year all the way through the end of 2016, as seen in the chart below.
The Foreclosure Crisis: 10 Years Later | MyKCM
If this trend continues, the country will be back to 2005 levels by the end of 2017.

Bottom Line

As the economy continues to improve, and employment numbers increase, the number of completed foreclosures should continue to decrease.

Tuesday, November 15, 2016

Foreclosures are at their lowest point in 8 years, buyer availability is at its' highest point in 8 years. Combined, that means a shortage of inventory in the market...


A Lack of Listings Remains 'Huge' Challenge in the Market


A Lack of Listings Remains ‘Huge’ Challenge in the Market | MyKCM
The housing crisis is finally in the rearview mirror as the real estate market moves down the road to a complete recovery. Home values are up, home sales are up, and distressed sales (foreclosures & short sales) are at their lowest mark in over 8 years. This has been, and will continue to be, a great year for real estate.
However, there is one thing that may cause the industry to tap the brakes: a lack of housing inventory. According to the National Association of Realtors (NAR), buyer traffic and demand continues to be the strongest it has been in years. The supply of homes for sale has not kept up with this demand and has driven prices up in many areas as buyers compete for their dream home.
Traditionally, the winter months create a natural slowdown in the market. Jonathan Smoke, Chief Economist at realtor.com, points to low interest rates as one of the many reasons why buyers are still out in force looking for a home of their own.
“Overall, the fundamental trends we have been seeing all year remain solidly in place as we enter the traditionally slower sales season, and pent-up demand remains substantial as buyers seek to get a home under contract while rates remain so low.”
NAR’s Chief Economist, Lawrence Yun, points out that the inventory shortage we are currently experiencing isn’t a new challenge by any means:
"Inventory has been extremely tight all year and is unlikely to improve now that the seasonal decline in listings is about to kick in. Unfortunately, there won't be much relief from new home construction, which continues to be grossly inadequate in relation to demand."

Bottom Line

Healthy labor markets and job growth have created more and more buyers who are not just ready and willing to buy but are also able to. If you are debating whether or not to put your home on the market this year, now is the time to take advantage of the demand in the market.

Monday, October 31, 2016

Prepare yourself properly, before you begin the home buying process, and you will find that it isn't scary at all!


Taking the Fear out of the Mortgage Process


Taking the Fear out of the Mortgage Process | MyKCM
A considerable number of potential buyers shy away from jumping into the real estate market due to their uncertainty about the buying process. A specific cause for concern tends to be mortgage qualification.

For many, the mortgage process can be scary, but it doesn’t have to be!

In order to qualify in today’s market, you’ll need to have saved for a down payment (the average down payment on all loans was 11% last month, with many buyers putting down 3% or less), a stable income and good credit history.
Throughout the entire home buying process, you will interact with many different professionals, all of which perform necessary roles. These professionals are also valuable resources for you.
Once you’re ready to apply, here are 5 easy steps that Freddie Mac suggests to follow:
  1. Find out your current credit history & score – even if you don’t have perfect credit, you may already qualify for a loan. The average FICO Score of all closed loans in September was 731, according to Ellie Mae.
  2. Start gathering all of your documentation – income verification (such as W-2 forms or tax returns), credit history, and assets (such as bank statements to verify your savings).
  3. Contact a professional – your real estate agent will be able to recommend a loan officer that can help you develop a spending plan, as well as determine how much home you can afford.
  4. Consult with your lender – he or she will review your income, expenses, and financial goals in order to determine the type and amount of mortgage you qualify for.
  5. Talk to your lender about pre-approval – a pre-approval letter provides an estimate of what you might be able to borrow (provided your financial status doesn’t change), and demonstrates to home sellers that you are serious about buying!

Bottom Line

Do your research, reach out to professionals, stick to your budget, and be sure that you are ready to take on the financial responsibilities of becoming a homeowner.

Friday, September 23, 2016

Good news for the housing market - preforeclosure levels are back to what they were before the housing crisis hit...


Foreclosure Rate Drops to Pre-Crisis Levels


Foreclosure Rate Drops to Pre-Crisis Levels [INFOGRAPHIC] | MyKCM
Some Highlights:
  • Only 2.9% of homes are in serious delinquency, down 17.1% from July 2015.
  • This is the 57th consecutive month with a year-over-year decline.
  • The national foreclosure rate has returned to August 2007 levels, at only 0.9%.